World Bank Says Corruption Costs Kenya 2% of GDP Annually as 2026 Growth Forecast Rises to 4.6%
Ready
Kenya's economy is projected to grow 4.6% in 2026, up from the World Bank's previous 4.3% forecast, but a new assessment estimates that corruption and collusion add approximately two percentage points of GDP to the annual fiscal deficit. With public debt at 70.6% of GDP, interest payments absorbing about one third of government revenue and poverty affecting more than 43% of the population, the findings connect weaknesses in public financial management to Kenya's borrowing costs, investment conditions and household welfare.
Kenya's economy is expected to grow faster than previously forecast in 2026, but a new World Bank assessment estimates that corruption and collusion are adding approximately two percentage points of GDP to the country's annual fiscal deficit, increasing borrowing requirements and limiting the government's ability to translate economic growth into improvements in living standards.
The World Bank has raised its 2026 economic growth forecast for Kenya from 4.3% to 4.6%, reflecting stronger activity in industry and services during the first half of the year. However, its latest Kenya Economic Update, released on 4 November 2026, presents a considerably less favourable assessment of the country's public finances, estimating that corruption and collusion impose a fiscal burden equivalent to approximately 2% of gross domestic product annually.
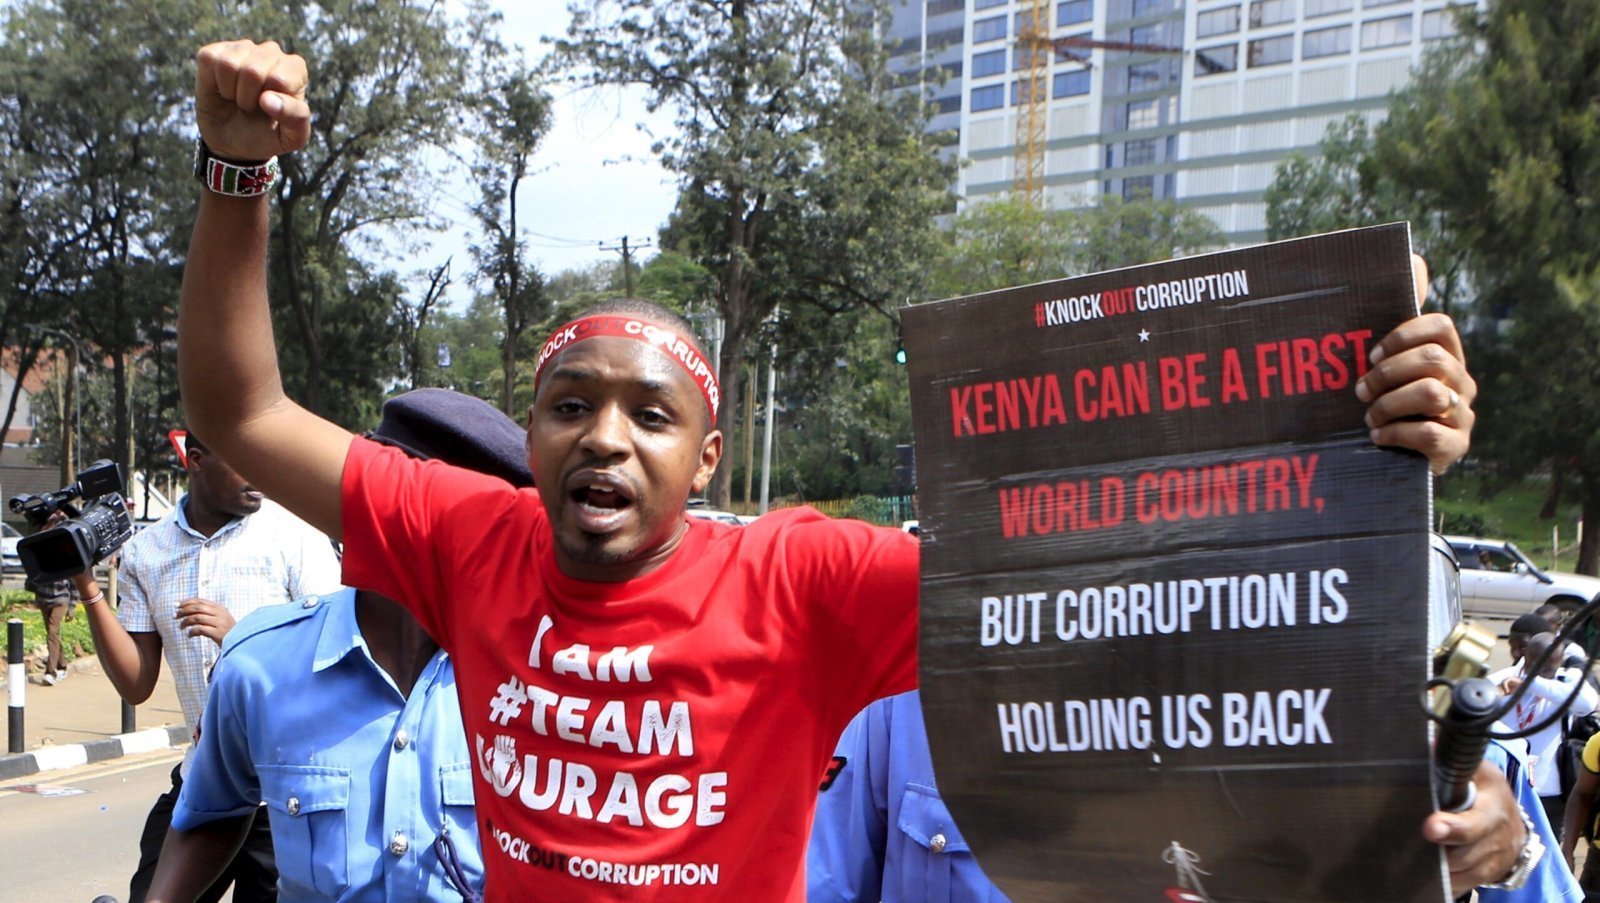
The estimate provides a financial measure of a problem that has frequently dominated Kenya's political debate without being consistently examined through its consequences for public expenditure, borrowing and economic productivity. According to the World Bank, governance weaknesses contribute to higher government spending, reduced revenue collection and additional financing requirements, creating costs that continue to accumulate through interest payments on public debt.
The findings come as Kenya manages public debt estimated at approximately 70.6% of GDP, with interest payments consuming about one-third of government revenue. The country remains at high risk of debt distress, while the Bank estimates that 43.3% of the population lived below the international poverty line of $3 per person per day in 2025, measured using 2021 purchasing power parity.
These figures expose a persistent problem in Kenya's economic management. The country continues to record positive economic growth and attract investment across several sectors, but a substantial share of government revenue is already committed to financing past expenditure. Weaknesses in the management of public resources increase those obligations and reduce the fiscal capacity available to support new investment.
How Corruption Adds to Kenya's Borrowing Requirements
The World Bank's estimate of a fiscal cost equivalent to 2% of GDP requires careful interpretation. It does not mean that an amount equal to 2% of Kenya's annual economic output has been independently identified as stolen public money. The figure represents the Bank's estimate of the broader fiscal consequences associated with corruption and collusion, including inefficient expenditure, revenue losses and the additional borrowing required to finance the resulting deficit.
The distinction is economically consequential because corruption can impose costs far beyond the immediate value of a fraudulent transaction. Where public procurement is manipulated, a government may pay more for roads, railways, hospitals, energy infrastructure or public services than would have been necessary under competitive contracting. Where tax administration is compromised, revenue that should have entered the Treasury may be lost through evasion, collusion or irregular exemptions. Where project selection is influenced by political or private interests rather than economic returns, public capital can be committed to investments that deliver less value than alternative uses of the same resources.
These effects accumulate within the government's fiscal accounts. Expenditure remains high, revenue falls below its potential, and the gap must be financed through borrowing, spending reductions or additional taxation.
For Kenya, which already faces substantial debt servicing obligations, the consequences are particularly expensive. Additional borrowing creates future interest payments, while concerns about fiscal management can influence the risk premiums demanded by lenders. The resulting financing costs can persist long after the original procurement decision or revenue loss occurred.
The relationship between corruption and public debt is therefore more extensive than the direct diversion of public funds. A government can incur substantial additional liabilities through overpriced contracts, inefficient projects and financing decisions that fail to deliver economic returns proportionate to their costs.
The World Bank's findings suggest that improvements in governance could contribute directly to fiscal consolidation. However, the precise amount of potential savings would depend on which weaknesses are corrected, how quickly reforms are implemented and whether lower expenditure or stronger revenue collection produces measurable changes in the deficit.
Kenya's Public Debt Has Become a Constraint on Economic Policy
Kenya's debt position provides the financial context for the World Bank's governance assessment. With public debt estimated at approximately 70.6% of GDP, the country has limited room to absorb additional borrowing without increasing pressure on its fiscal position. Interest payments already consume around one third of government revenue, leaving a smaller proportion of available resources for public services, infrastructure maintenance and new development expenditure.
A debt ratio alone does not determine whether a country can sustain its obligations. The composition of debt, interest rates, repayment schedules, currency exposure, revenue collection and economic growth all influence sustainability. Kenya's challenge is that its substantial debt stock is accompanied by expensive financing and significant demands on government revenue.
The World Bank continues to classify Kenya as being at high risk of debt distress. This assessment reflects the vulnerability of the country's public finances to borrowing costs, revenue shortfalls and other economic pressures.
The estimated fiscal cost of corruption becomes particularly relevant under these conditions. When a government is already devoting a large share of revenue to interest payments, inefficient expenditure can create additional debt obligations that compete with future spending priorities.
The consequences also extend to the private sector. Heavy domestic government borrowing can place pressure on financing conditions by increasing competition for available capital. Businesses seeking credit for expansion, equipment or working capital may face higher borrowing costs, particularly where financial institutions consider government securities an attractive alternative to private lending.
The scale of this effect depends on monetary conditions, banking sector liquidity and investor demand for government debt. Nevertheless, the relationship illustrates why fiscal governance is relevant to business investment and employment, rather than solely to public administration.
Kenya's economic performance will depend partly on its ability to improve the productivity of public expenditure while reducing the financing burden associated with its existing debt.
Growth Forecast Raised to 4.6%, but Household Gains Remain Limited
Despite the governance concerns, the World Bank has become more optimistic about Kenya's immediate economic performance. Its November 2026 assessment raises the country's growth forecast to 4.6% from an earlier projection of 4.3%, reflecting stronger activity during the first half of the year. Industry and services contributed to the improvement, helping compensate for slower growth in agriculture.
The revised projection indicates that Kenya's economy is performing better than the Bank previously anticipated, although growth remains below the government's expectation of at least 5%.
The World Bank projects growth of approximately 4.4% in 2027 and 4.8% in 2028, suggesting continued expansion but not a rapid acceleration capable of resolving the country's fiscal and employment challenges on its own.
The outlook is also exposed to political and fiscal risks associated with Kenya's August 2027 general election. Election periods can influence investor confidence, tourism activity and government spending decisions. Additional expenditure commitments or weaker fiscal discipline could complicate efforts to reduce borrowing requirements.
The more difficult economic question concerns how much of Kenya's growth translates into improvements in household income and employment. According to the figures accompanying the latest assessment, employment growth slowed from 4% in 2024 to 3.8% in 2025, while formal employment accounted for approximately 16.2% of total jobs.
The limited share of formal employment is particularly relevant to Kenya's fiscal position. A labour market dominated by informal employment constrains the government's ability to expand income tax collection through payroll systems and makes it more difficult for many workers to access predictable earnings, social protection and formal credit.
Informal businesses can contribute substantially to economic activity, but many operate with limited capital, low productivity and irregular income. Strong GDP growth does not necessarily produce equivalent improvements in household welfare where new economic activity is concentrated in sectors that employ relatively few workers or where productivity gains do not translate into higher earnings.
The World Bank estimates that Kenya's poverty rate will decline only marginally from 43.3% in 2025 to approximately 43% in 2026, using the international poverty threshold of $3 per day in 2021 purchasing power parity terms.
That projected reduction of 0.3 percentage points indicates that stronger economic growth is not expected to produce a substantial immediate decline in poverty.
The figures also show why economic performance cannot be assessed through GDP growth alone. Employment quality, household purchasing power, the distribution of income and the cost of essential services determine how much of the expansion reaches ordinary Kenyans.
Tanzania's Lower Debt and Faster Growth Provide a Regional Comparison
Kenya's latest economic assessment also provides an opportunity to compare the fiscal positions of East Africa's two largest economies, Kenya and Tanzania. The World Bank's October 2026 Tanzania Economic Update projects economic growth of approximately 6.1% in 2026, compared with its newly revised 4.6% forecast for Kenya. Tanzania's public debt is estimated at approximately 49% of GDP, considerably below Kenya's 70.6%.
| Economic indicator | Kenya | Tanzania |
| Projected GDP growth, 2026 | 4.6% | 6.1% |
| Public debt as a share of GDP | 70.6% | Approximately 49% |
| Estimated annual fiscal cost associated with corruption | Approximately 2% of GDP | No directly comparable estimate established |
The comparison places the two economies in different fiscal positions. Tanzania is projected to grow faster in 2026 while carrying a substantially lower public debt burden relative to the size of its economy.
The difference in debt ratios amounts to approximately 21.6 percentage points of GDP. This gives Tanzania a different starting position when considering new borrowing, although debt sustainability also depends on revenue mobilisation, financing terms, foreign exchange exposure and the economic returns generated by public investment.
The figures do not establish that Tanzania has lower corruption losses than Kenya. The World Bank's estimated 2% fiscal cost has not been reproduced for Tanzania using an equivalent methodology, and comparing governance performance requires consistent measurements across both countries.
The more defensible comparison concerns fiscal capacity. Kenya's higher debt burden and substantial interest obligations restrict the resources available for new expenditure, while Tanzania's lower debt ratio provides a different set of financing conditions for public investment.
The countries also differ in economic structure, domestic revenue mobilisation, financial market development and the composition of government borrowing. Those differences influence how quickly economic growth can strengthen public finances.
For investors and businesses operating across East Africa, the comparison is relevant because fiscal pressures affect taxation, government payment obligations, infrastructure expenditure, interest rates and the predictability of economic policy.
A country with faster economic growth and lower debt does not automatically offer better investment conditions across every sector. However, the combination can create greater fiscal flexibility where public expenditure is managed efficiently and borrowing is directed towards investments with credible economic returns.
Kenya's Governance Reforms Face a Test of Measurable Results
Kenya has introduced measures intended to improve public financial management, procurement transparency and accountability.
These include electronic government procurement reforms and legislation addressing conflicts of interest. The World Bank's June 2026 financing operation also supported improvements in public financial management and government cash management.
Such measures are intended to reduce opportunities for irregular contracting, improve the monitoring of government expenditure and strengthen the systems through which public funds are authorised and disbursed.
Their economic value, however, will depend on implementation. Electronic procurement can improve transparency by creating records of tenders, bids, contract awards and payments. Its effectiveness depends on whether public institutions consistently use the system, whether procurement information is accessible for scrutiny and whether irregularities produce consequences for responsible officials and contractors.
Conflict of interest legislation can establish clearer obligations for public officials, but the effectiveness of those rules depends on disclosure requirements, independent verification and enforcement. Similarly, improvements in cash management can reduce unnecessary borrowing and help governments plan expenditure more efficiently, but only where spending institutions comply with budgetary controls and financial reporting requirements.
The World Bank's estimated fiscal cost provides a potential benchmark against which reform outcomes can be assessed. If governance weaknesses are contributing to additional expenditure and borrowing, successful reforms should eventually be reflected in better procurement outcomes, improved revenue collection, lower fiscal pressures or a combination of these results.
The challenge is that fiscal improvements cannot always be attributed to a single reform. Economic growth, tax policy changes, interest rates, exchange rates and expenditure decisions can all influence government revenue and borrowing requirements. Assessing progress will therefore require more detailed evidence than the adoption of new legislation or digital administrative systems.
Kenya's experience also demonstrates why governance reform is closely connected to economic competitiveness. Businesses require predictable public procurement, fair competition, reliable regulation and confidence that government decisions are made according to established rules.
Where public contracts are influenced by political connections or collusion, firms that compete on price, quality and technical competence can be disadvantaged. This weakens incentives for productive investment and can discourage businesses from participating in government procurement.
The effects are especially consequential for smaller domestic enterprises that lack the financial resources or political access available to larger competitors.
Kenya's Economic Outlook Depends on More Than Faster GDP Growth
The World Bank's November assessment presents an economy with improving near term growth prospects but persistent weaknesses in public finance management. The revised 4.6% growth forecast suggests that Kenya's industry and services sectors continue to support economic expansion. However, public debt of approximately 70.6% of GDP, substantial interest payments and a poverty rate above 43% demonstrate the limits of growth that does not sufficiently strengthen fiscal capacity or household incomes.
The estimated annual fiscal cost associated with corruption and collusion adds another dimension to the country's debt challenge. It suggests that Kenya's financing pressures arise partly from the efficiency with which public resources are collected and spent, alongside borrowing costs, revenue constraints and wider economic conditions.
For the government, this creates a measurable economic case for procurement reform, stronger expenditure controls and improved accountability. Reducing avoidable fiscal costs could lower borrowing requirements and preserve resources for investment, although the scale of actual savings will depend on implementation and enforcement.
Kenya's economic prospects will continue to depend on private investment, export performance, productivity and the ability of businesses to create employment. The World Bank's findings indicate that improvements in public financial management could support those objectives by reducing unnecessary expenditure and the financing pressures associated with it.
The country's next phase of economic growth will therefore be assessed against two related outcomes: whether GDP continues to expand, and whether stronger governance allows a greater share of public resources to support productive investment, employment and household welfare.
FAQ
How much does corruption cost Kenya annually, according to the World Bank? The World Bank estimates that corruption and collusion add approximately two percentage points of GDP to Kenya's annual fiscal deficit through higher public expenditure, revenue losses and associated borrowing requirements.
Does the 2% estimate mean Kenya loses 2% of GDP directly to theft? No. The estimate measures broader fiscal consequences associated with corruption and collusion. It should not be interpreted as an independently audited amount of public money stolen.
What is Kenya's economic growth forecast for 2026? The World Bank raised its November 2026 forecast to 4.6%, from an earlier projection of 4.3%, reflecting stronger activity in industry and services.
How much public debt does Kenya have relative to GDP? The latest World Bank assessment places Kenya's public debt at approximately 70.6% of GDP.
How much of Kenya's government revenue goes towards interest payments? Interest payments absorb approximately one third of government revenue, according to the figures accompanying the November 2026 assessment.
What is Kenya's poverty rate? The World Bank estimates that 43.3% of Kenyans lived below the international poverty line of $3 per person per day in 2025, using 2021 purchasing power parity. The rate is projected to decline marginally to approximately 43% in 2026.
How does Kenya's economic outlook compare with Tanzania's? The World Bank projects 2026 growth of 4.6% for Kenya and approximately 6.1% for Tanzania. Kenya's public debt is estimated at 70.6% of GDP, compared with approximately 49% for Tanzania. These indicators do not establish a comparable ranking of corruption losses.
What reforms could reduce Kenya's corruption related fiscal costs? The World Bank identifies improvements in procurement transparency, expenditure management, conflict of interest controls and public financial management as relevant measures. Their effectiveness depends on implementation, oversight and enforcement.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
