East Africa’s Fuel Map Is Being Redrawn as Lamu, Mombasa and Tanga Compete for the Same Hinterland
Ready
Kenya is combining a proposed mega-refinery in Lamu with Mombasa’s established petroleum network, while Tanzania is positioning Tanga as both a refined-fuel gateway and the export terminal for Ugandan crude. Rwanda’s use of both corridors shows that the contest will be decided by cost, reliability and infrastructure rather than political loyalty.
The arrival of the MT Sea Wolf at Mombasa’s Kipevu Oil Terminal on September 29 looked like a routine petroleum delivery. Its cargo, however, carried considerably more strategic weight than its 40,000 tonnes of petrol and diesel.
It was Rwanda National Energy Company’s first government-backed fuel shipment through Kenya. The delivery activated a new framework giving the landlocked country access to Mombasa’s terminals, Kenya Pipeline Company’s storage and transportation network, and longer periods in which to hold strategic stocks.
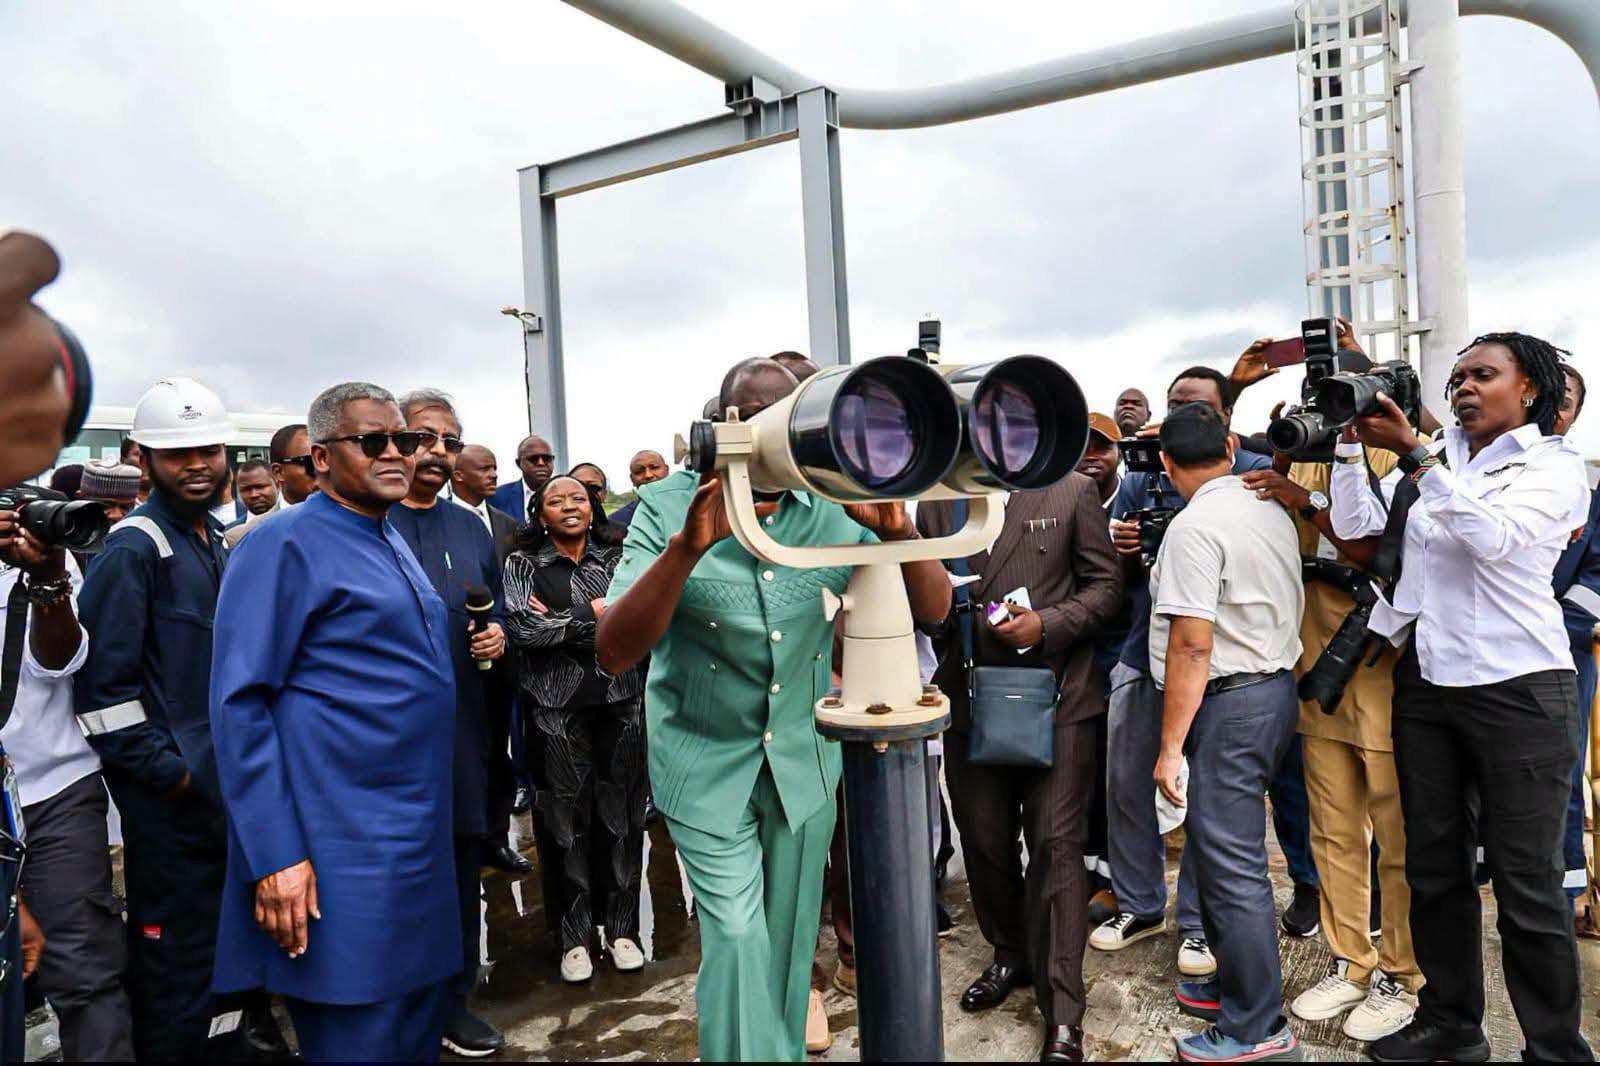
A day later, attention moved north to Lamu, where Kenya and Dangote Industries held a ceremonial launch of a proposed $16 billion refinery capable of processing 700,000 barrels of crude oil a day.
Taken together, the two developments reveal a larger contest over East Africa’s energy economy. Lamu wants to become the region’s refining and petrochemical centre. Mombasa is defending its position as the most developed petroleum-import and distribution gateway. Tanga, meanwhile, is emerging as Tanzania’s northern energy hub, handling Rwanda-bound refined products while preparing to export Ugandan crude through the East African Crude Oil Pipeline.
This is not simply a contest between ports. It is a competition over transit revenue, storage, pipelines, industrial investment, foreign exchange and control of the supply chains serving East Africa’s landlocked economies.
Lamu is the largest wager and the least certain
Dangote’s Lamu refinery will be among the largest industrial projects ever undertaken in East Africa. The planned facility is intended to process 700,000 barrels a day, stimulate petrochemicals and bitumen production, and create more than 50,000 jobs. Regional governments have been offered a combined 30% equity interest, while completion is targeted for 2030.
The scale reflects a clear market opportunity. East Africa consumes an estimated 20 million to 30 million tonnes of petroleum products annually and continues to depend heavily on imported refined fuel. That dependence exposes regional economies to shipping disruptions, exchange-rate pressure and geopolitical instability in the Middle East.
Yet the Lamu ceremony should not be mistaken for proof that full construction is underway.
A Kenyan court has ordered the preservation of parts of the proposed site while it considers claims brought by local residents. Questions also remain about environmental approval, compensation, crude supply, financing and the supporting infrastructure required to operate a refinery of this size. The ceremonial groundbreaking can proceed, but substantive work could be constrained by the court order.
The project’s location has also changed rapidly. In April, East African governments were discussing a regional refinery at Tanzania’s Port of Tanga, with crude potentially sourced from Uganda, South Sudan, Kenya and the Democratic Republic of Congo. By September, Dangote’s attention had shifted decisively to Lamu.
That movement underlines how fluid regional infrastructure commitments can be. A refinery announcement is not yet a financing close, a crude-supply contract or an operating plant.
Mombasa already possesses what Lamu is trying to build: a network
Where Lamu represents future industrial capacity, Mombasa’s advantage is infrastructure that already exists.
Kenya Pipeline Company operates a 1,342-kilometre network with reported annual capacity of 14 billion litres and storage capacity exceeding 1.1 billion litres. That system gives Mombasa the ability to receive imported fuel, hold it and move it inland without depending entirely on road tankers.
Under the Rwanda agreement, volumes moving through Kenya could increase roughly tenfold. Kenyan and Rwandan accounts place the longer-term target at more than 500 million litres annually, potentially reaching 600 million litres. Rwanda has also secured an extension of the storage period for its products in Kenya Pipeline Company facilities from 35 days to as many as 90 days during an initial two-year period.
This flexibility matters as much as distance. A fuel corridor is competitive only when cargo can be discharged without long delays, stored safely, financed affordably and released according to demand.
Mombasa’s proposition is therefore larger than the port itself. It includes Kipevu Oil Terminal 2, inland pipelines, storage depots, regulatory arrangements and an established logistics industry. The maiden Rwanda cargo demonstrates that these assets can be offered as an integrated regional service.
For Kenya, the prize is the recovery of petroleum-transit business that had increasingly moved through Tanzania. For Rwanda, it is greater negotiating leverage and protection against disruption on any single route.
Tanga is no longer a minor alternative
Describing Rwanda’s return to Mombasa as a complete loss for Tanzania would be misleading.
Rwanda opened its government-backed Tanga route first. Rwanda National Energy Company and Gulf Bulk Petroleum Tanzania signed their agreement on July 3, followed later that month by a maiden cargo of 40,000 tonnes of refined petroleum products. The Mombasa route supplements that arrangement rather than automatically replacing it.
Tanga has also undergone substantial physical expansion. Tanzania Ports Authority lists the port with a depth of up to 13 metres and an annual capacity of approximately three million metric tonnes, compared with about 750,000 tonnes before the recent improvements.
Its strategic importance will increase further when the East African Crude Oil Pipeline becomes operational. The 1,443-kilometre heated pipeline will transport Ugandan crude from Hoima to the Chongoleani marine terminal near Tanga.
EACOP reported overall completion of 92.7% at the end of August. Tanzanian officials expect pipeline filling to begin in December 2026, with the first export cargo from Tanga targeted for February 2027.
Tanga is consequently developing two distinct roles: importing refined products for Tanzania and neighbouring markets while exporting crude oil from Uganda. Few ports in the region will occupy both sides of the petroleum trade.
Its challenge is to convert those assets into a coherent logistics system. Port depth and headline capacity are not enough. Tanzania must provide competitive storage, predictable clearance, reliable road and rail connections, efficient border processing and transparent charges throughout the journey to Rwanda and other inland markets.
Rwanda is building options, not choosing sides
The most important actor in the emerging contest may be neither Kenya nor Tanzania. It is Rwanda.
As a landlocked economy dependent on imported petroleum, Rwanda has little reason to commit itself permanently to one gateway. Maintaining access to Tanga, Dar es Salaam and Mombasa improves resilience and strengthens Kigali’s bargaining position with ports, storage operators, transporters and oil-marketing companies.
The two routes can also serve different purposes. Mombasa offers an extensive pipeline and storage system. Tanga provides access through Tanzania’s northern corridor and is developing around a major crude-export terminal. Dar es Salaam remains Rwanda’s principal gateway for much of its general cargo.
Fuel will flow through whichever corridor offers the best combination of total landed cost, delivery time, credit terms, storage flexibility and reliability. Political statements may influence agreements, but commercial performance will determine recurring volumes.
This explains why the contest should not be read as a zero-sum diplomatic dispute. Rwanda’s strategy is diversification. Kenya and Tanzania are competing to earn a larger share of its business, not necessarily to eliminate the other route.
Refining could alter the balance, but only after delivery
If the Lamu refinery becomes operational, Kenya’s competitive proposition would change fundamentally.
Mombasa currently helps distribute imported refined products. Lamu would potentially allow Kenya to refine crude within the region and supply neighbouring markets directly. Combined with Kenya’s pipeline and storage infrastructure, that could give the country influence across refining, marine logistics and inland distribution.
Tanzania retains important advantages. Tanga will be connected directly to Uganda’s producing oil fields through EACOP. The port is closer to parts of the Great Lakes market, and the government has already invested in expanding its capacity. Tanzania also has land, natural gas, industrial zones and access to southern corridor markets that could support downstream manufacturing.
The strategic question is whether Tanzania remains primarily a transit and crude-export location or develops more domestic value addition around petroleum, gas, fertiliser, chemicals, plastics and logistics services.
A refinery of Lamu’s proposed scale may eventually serve the entire region. It could also make it harder to justify competing facilities unless East African demand grows fast enough to support them. Governments will need to separate regional industrial logic from prestige-led infrastructure planning.
What Tanzania must do next
Tanzania’s strongest response would not be another oversized announcement. It would be to make Tanga demonstrably competitive.
That requires publishing comparable performance data: vessel turnaround time, storage charges, cargo dwell time, border clearance, road transit time and total cost to Kigali. Importers cannot make decisions based only on descriptions of new cranes, deeper channels or improved berths.
The country must also connect its investments. Tanga Port, EACOP, oil-storage facilities, road and rail infrastructure, industrial land and special economic zones should be presented as parts of one energy and manufacturing corridor.
A dedicated petroleum-handling berth, expanded commercial storage and faster connections to inland markets would make the Rwanda arrangement easier to scale. Clear rules for private investment and long-term storage would further strengthen the port’s position.
Tanzania should also avoid treating Rwanda’s use of Mombasa as a political rejection. Competitive infrastructure markets require clients to have alternatives. The appropriate response is better service, stronger commercial terms and consistent delivery.
A contest that could benefit the region
East Africa’s energy market is large enough to support several important gateways. Redundancy can protect countries when war, shipping disruption, port congestion or infrastructure failure affects one route. Competition can also lower logistics costs and pressure operators to improve service.
The greater risk is duplication without coordination: governments building expensive infrastructure around optimistic demand projections while failing to secure crude, financing, customers or environmental approval.
The real scorecard will therefore not be the number of ceremonies held or agreements signed. It will be the amount of fuel handled, the cost paid by consumers, the reliability of supply and the share of value retained within East Africa.
Mombasa has the strongest operating network today. Tanga is gaining strategic weight through port expansion, Rwanda-bound fuel, and EACOP. Lamu offers the most ambitious industrial vision, but it also carries the greatest execution risk.
The emerging energy map will be determined by which location can turn infrastructure into dependable commercial service. On that measure, the contest has only just begun.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
