Tanzania and Qatar Tax Treaty Clears a Barrier. The Real Test Is Whether Capital Follows
Ready
The agreement could make cross-border investment easier to structure across energy, logistics, tourism, agriculture and finance. Its commercial value now depends on the fine print, ratification and a credible pipeline of bankable projects.
Tanzania and Qatar have removed one obstacle from their investment relationship, but not yet the most difficult one.
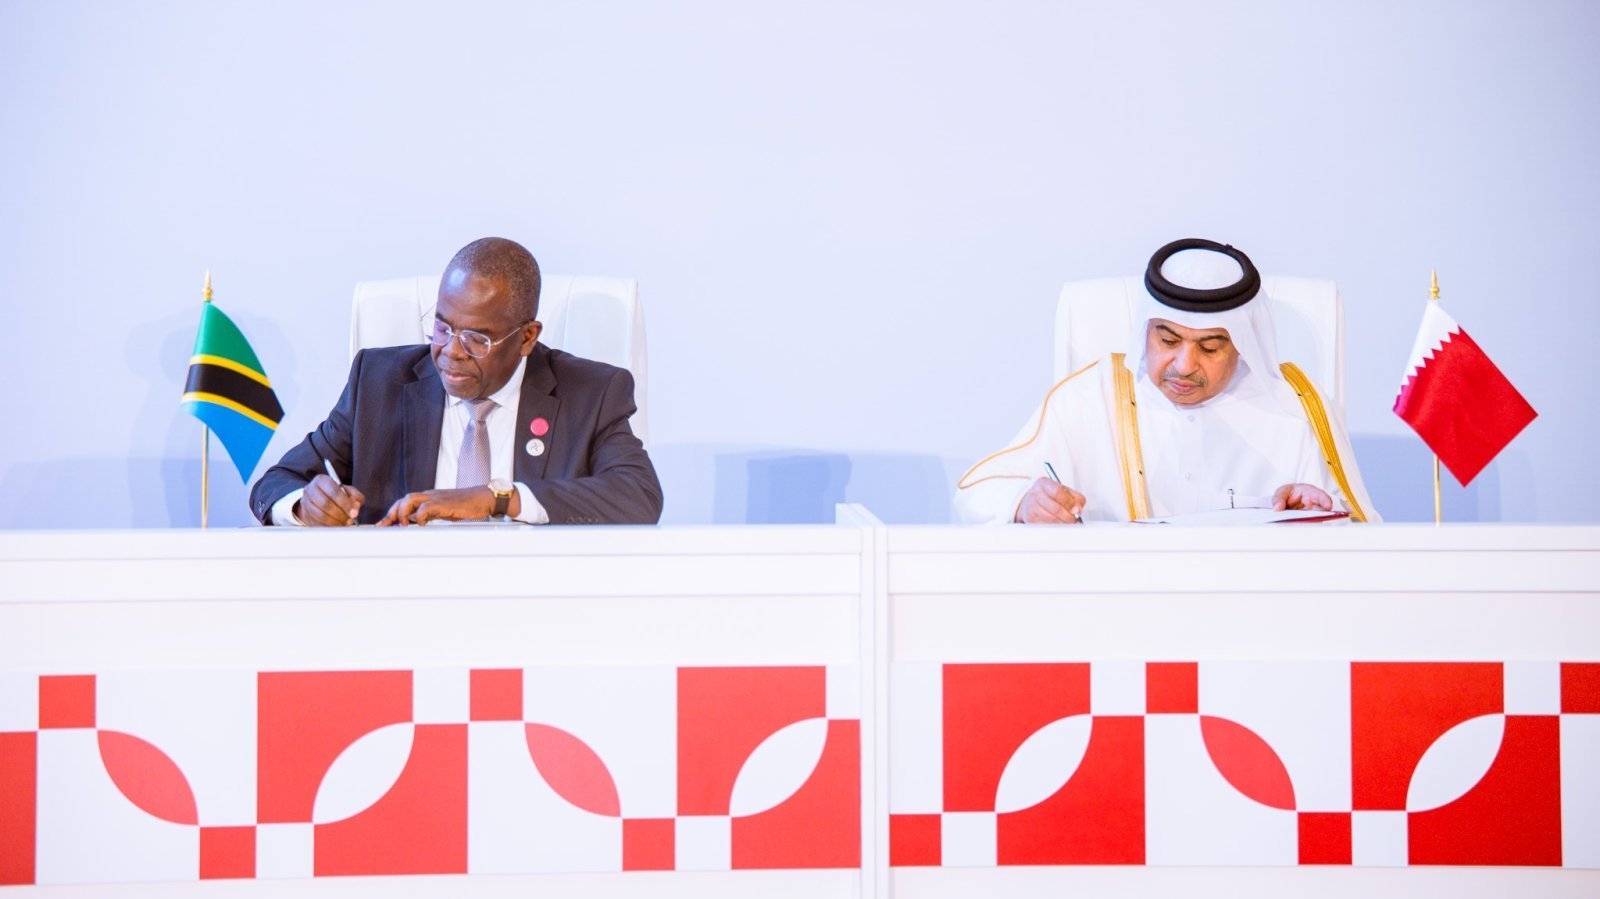
On 29 September, the two governments signed an agreement to avoid double taxation on income and prevent tax evasion and avoidance. Tanzania’s Finance Minister, Khamis Mussa Omar, and his Qatari counterpart, Ali bin Ahmed Al Kuwari, signed on behalf of their countries.
Qatar’s General Tax Authority said the agreement is intended to create a stable tax environment, strengthen transparency and information exchange, and support capital, trade and investment between the two economies.
The announcement sounds administrative. In practice, it could influence how Qatari investors price Tanzanian projects, how lenders structure financing and how profits move between the two countries. It also arrives as Tanzania intensifies its courtship of Gulf capital for energy, infrastructure, food production, tourism and logistics.
Yet the distinction between signing a treaty and activating it is crucial. Until the two governments confirm that all required procedures have been completed, publish the treaty and specify its effective date, businesses should not assume that treaty benefits are already available.
What the agreement is designed to change
Cross-border investment can create overlapping tax claims or uncertainty over where particular income should be taxed. A Tanzanian project company may pay tax on income earned locally, while payments such as dividends, interest, royalties or management fees can attract withholding tax before the money reaches an overseas investor. Depending on the investor’s status and the rules in each jurisdiction, further tax or reporting obligations may follow.
A double-taxation agreement normally determines which country may tax particular income, when the other country must provide relief and what conditions an investor must satisfy to claim treaty treatment. It can also define when an overseas business has a taxable permanent establishment and establish a process for resolving disputes between tax authorities.
The Tanzania and Qatar negotiations were concluded, and the draft was initialled in August 2025. At that stage, Qatar’s tax authority said the agreement contained provisions covering international maritime and air transport, joint ventures, dividends, interest and royalties. It also highlighted tax-information exchange and the removal of barriers to capital flows.
Those categories touch the main channels through which major projects are financed and operated. Lower or more predictable tax costs can improve expected returns. Clearer rules can reduce the risk that a project becomes trapped in a dispute over where income should be taxed.
But the commercial effect cannot be calculated from the signing announcement alone. Investors still need the full treaty text, including the taxes covered, the treatment of permanent establishments and capital gains, any limits on withholding taxes, eligibility tests, anti-abuse rules and dispute-resolution procedures.
A treaty aligned with Tanzania’s Gulf investment push
The timing is not accidental. Two days before the signing, Prime Minister Mwigulu Nchemba met a Qatar Chamber delegation and invited Qatari businesses to invest in Tanzania.
The sectors presented included agriculture and food processing, energy and liquefied natural gas, minerals, livestock, the blue economy, tourism and hospitality, ports, logistics and special economic zones. Qatar Chamber also raised the possibility of organising a business delegation to examine opportunities in Tanzania.
This is a broad list, but the strongest fit lies where Qatar has capital, operating expertise or strategic demand.
Energy is the most obvious area. Tanzania has natural-gas resources and long-standing ambitions to develop a larger gas economy. In February, the Ministry of Finance said the country wanted to draw on Qatar’s experience in gas exploration, production and development, while using Qatar’s financial-centre capabilities to improve access to capital markets.
Large energy projects commonly involve project companies, foreign debt, technical-service agreements and eventual distributions to investors. Tax treatment affects all of them. Greater predictability could improve financial modelling and make it easier for sponsors and lenders to assess long-term returns.
It cannot, however, substitute for agreements on project economics, regulation, infrastructure, foreign-exchange risk and the allocation of construction and market risk.
Ports, logistics and aviation present another natural opening. The earlier treaty announcement specifically referred to maritime and air transport. The final wording could therefore matter to airlines, shipping companies, freight operators and investors linking Tanzanian ports to regional supply chains.
Tanzania’s access to the Indian Ocean and its connections to landlocked East and Central African markets strengthen the strategic case. Investors will still judge port efficiency, rail and road integration, customs performance and the reliability of cargo volumes.
Tourism and hospitality could also benefit. Hotel investments often combine foreign equity, debt, management contracts, brand fees and reservation systems. Each creates cross-border payments whose tax treatment can influence the economics of a resort or business hotel.
A clearer treaty framework may make Tanzanian opportunities easier to compare with projects elsewhere, particularly for investors already active in premium hospitality and aviation.
Agriculture and food security offer a different proposition. Qatar is a food-importing economy, while Tanzania is seeking capital for production, processing, cold storage and export logistics.
Tanzania’s livestock ministry said in September that the country already exports meat to Qatar and wants investment to expand processing, quality assurance and cold-chain capacity.
A tax treaty will not reduce customs duties, secure sanitary approvals or fix logistics. It could, however, make a processing or distribution joint venture easier to finance and operate.
The signature is not the starting gun
For investors, the next announcement matters almost as much as this one.
Neither government’s public statement has established when the agreement will enter into force, from which tax period its provisions will apply, or the rates and conditions businesses will receive. Those details determine whether the treaty changes a live transaction or remains a future planning consideration.
Companies considering projects should therefore resist premature restructuring. The prudent step is to map the relevant income flows—dividends, interest, royalties, service fees, transport income and potential gains, then test them against the published treaty once it is available.
Eligibility will matter as much as the headline rates. Modern tax treaties increasingly require investors to demonstrate genuine economic substance and may deny relief where an arrangement was created mainly to obtain treaty advantages.
The information-exchange provisions are equally important. They show that the agreement is not simply an incentive instrument; it is also an enforcement framework.
Tanzania has an interest in attracting capital without opening a route for treaty shopping, artificial profit shifting or the concealment of taxable income. Qatar has a parallel interest in protecting the integrity of its international tax network.
What Tanzania should do next
The first priority is publication. The full agreement should be released promptly, accompanied by a concise guide explaining the ratification process, effective date, covered taxes, withholding-tax treatment and procedure for claiming relief. Predictability is most valuable when companies can understand and apply it.
The second priority is conversion. Tanzania and Qatar now need to move from a general catalogue of opportunities to a short pipeline of investment-ready projects. Each should have a clear sponsor, financing requirement, revenue model, approval status, risk allocation and implementation timetable. A project list without this information is promotion, not a deal pipeline.
Third, the proposed Qatari business delegation to Tanzania should be organised around transactions rather than ceremony. Meetings should connect investors with project owners, regulators, local financial institutions, exporters and potential operating partners. Sector-specific sessions on gas, ports, food processing, tourism and finance would be more productive than another broad investment forum.
Finally, progress should be measured publicly. The useful indicators are not the number of memoranda signed but the value of financing committed, projects reaching financial close, export contracts secured, facilities entering operation and jobs created.
A useful opening, not a guarantee
The tax agreement gives Tanzania a better platform from which to compete for Qatari capital. It addresses a real concern for investors and complements a diplomatic push that has become more commercially focused.
It does not make weak projects bankable. It does not resolve permitting delays, foreign-exchange exposure, infrastructure gaps or questions over contractual certainty. Nor does it automatically lower any company’s tax bill before the treaty becomes effective and its eligibility rules are met.
The opportunity is nevertheless significant. Qatar brings experience in gas, aviation, logistics, hospitality, food security and international finance. Tanzania offers resources, a large domestic market and access to wider regional demand.
If the treaty’s legal certainty is matched by disciplined project preparation, the agreement could help turn that complementarity into long-term investment.
The real scorecard will not be the signature. It will be the capital that moves after the ink dries.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
