Uchumi360 Author Archive

Author: Gaston Rucibigango

44 articles Latest: October 26, 2026
The Death of Interoperability Fees: How Rwanda’s eKash Is Rewriting the Digital Economy Rules
Regions 26 October 2026

The Death of Interoperability Fees: How Rwanda’s eKash Is Rewriting the Digital Economy Rules

At a fee ceiling of RWF 20 per transfer, Rwanda's national instant payment system cannot earn meaningful money from moving money. In September 2026 eKash handled 28.9 million transactions, according to the National Bank of Rwanda's October financial sector report. Multiplied by the cap, that is a maximum fee pool of about RWF 578 million, roughly $0.4 million, for an entire national payments system in a month. The figure is a ceiling rather than a revenue estimate, because institutions may charge less or nothing at all. That arithmetic frames the real question about eKash. When the central bank mandates that every person-to-person transfer runs through one switch, ends the bilateral contracts between mobile money providers and banks, and cuts fees by roughly a hundredfold, the payments toll disappears. Something has to replace the income of banks, mobile money operators and microfinance institutions, and the central bank has pointed to transaction data as the substitute. The thesis of this analysis is that eKash is less a pricing reform than a transfer of control. Price, routing and data have moved from private contracts to a rail operated under central bank authority. Whether that produces an economic gain depends on a chain that has not yet been shown to operate. Aggregated transaction data must become alternative credit scoring, scoring must become lending, and lending must reach the roughly 80 percent of people who have an account but no access to credit. Meanwhile the switch must stay reliable enough to deserve its monopoly on domestic transfers. The regional design adds a second test. Routing intra-EAC traffic through the EAC system and everything else through PAPSS avoids duplication, but cross-border payments are decided by settlement liquidity and foreign exchange, not by messaging standards. The Tanzania pilot is the first evidence of whether Rwanda's blueprint can travel.
Beyond Race Weekend: What Rwanda’s 10-Year Agreement With Formula 1 Means for Tourism and the Economy
Regions 13 October 2026

Beyond Race Weekend: What Rwanda’s 10-Year Agreement With Formula 1 Means for Tourism and the Economy

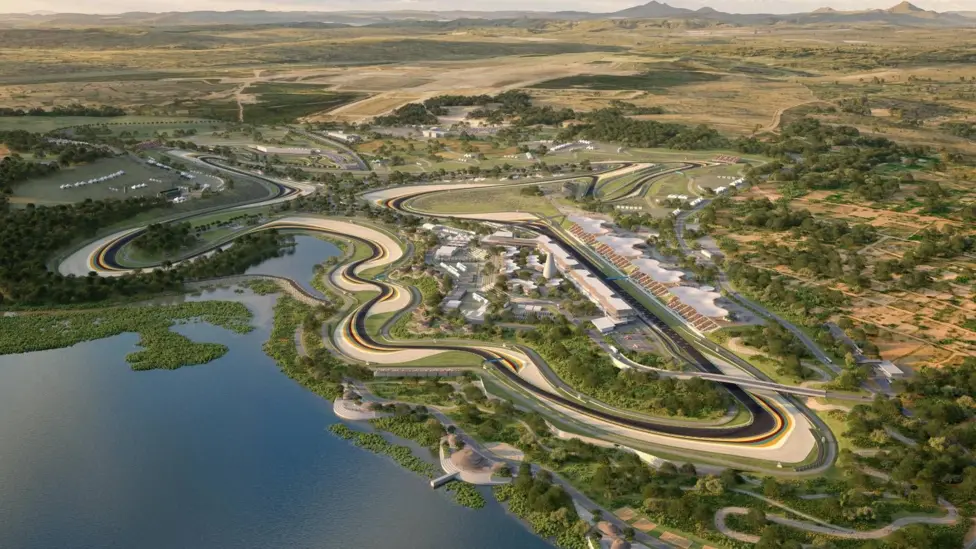
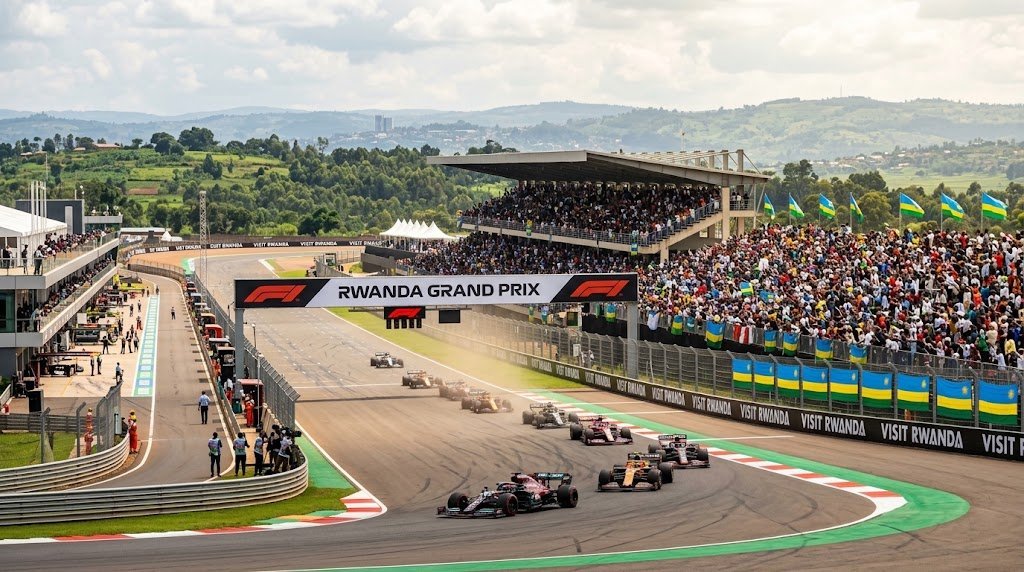
Rwanda’s tourism sector earned $685 million in 2025, and more than a third of that, $248 million, came from one species in one national park. That concentration is the starting point for judging what a ten-year Formula 1 commitment can do for the economy. A sector built on gorilla trekking and conferences has a narrow base, a supply that is capped by design, and a revenue target of $1.1 billion by 2029 that cannot be reached by adding more of the same. The African Grand Prix enters that market as a different kind of product. It brings tens of thousands of high-spending visitors in a short window, a global broadcast audience that carries the Visit Rwanda name, and a permanent venue that could host events throughout the year. Each of these channels works through a different mechanism. Race-weekend spending is large relative to Rwanda’s conference earnings but small relative to the gap between today’s receipts and the 2029 target. Brand exposure is harder to measure and potentially more valuable. The venue’s year-round use is the least certain and the most important. The economic effects beyond tourism follow from the same logic. Foreign-exchange earnings from visitors are real, but a dollar-denominated hosting fee and import-heavy construction reduce the net. Construction creates jobs and demand, though much specialist work is likely to be imported. The wider gain depends on whether Bugesera becomes a district with revenue of its own. The central thesis is that the Grand Prix will matter to Rwanda’s economy less as a weekend of spending than as a change in the type of visitor the country attracts and the price at which it sells access. If the race lifts the yield per visitor and fills the shoulder seasons, it strengthens the whole tourism system. If it simply competes with peak-season demand and ships profit to foreign operators, it becomes an expensive piece of marketing.

From Visit Rwanda to Formula One: Rwanda’s New Bet on Global Visibility
Regions 8 October 2026

From Visit Rwanda to Formula One: Rwanda’s New Bet on Global Visibility

Visit Rwanda's shirt deals show how the country has paid for global attention until now. The Arsenal sleeve agreement was reported at $13.3m per season over eight years and ended with the 2025-26 season. The Aston Villa front-of-shirt agreement that followed is reportedly worth up to $26m a year if bonuses are met. Both are marketing expenditure. They are rented visibility, priced annually, cancellable at the end of a term and carried on an operating budget. A Formula One Grand Prix works differently. Reports now indicate that Rwanda could join the calendar from 2030, although no official announcement has been made. A race needs a permanent circuit near Bugesera airport, reported at hundreds of millions of dollars at a minimum, plus hosting rights, event operations and a week of hospitality capacity that does not yet exist. The spending moves from a marketing line to a capital programme, and the risk moves from a sponsorship contract to the sovereign and quasi-sovereign balance sheet. The central argument is that the economic value of a Rwandan Grand Prix will be determined less by the race weekend than by what happens in the other 360 days. The circuit's financial logic depends on utilisation, on the performance of the airport it sits beside, and on whether Rwanda captures the commercial layers of the event rather than only hosting them. South Africa's minister has conceded the race to Rwanda while insisting his country will also get one, which shows the competing models are not mutually exclusive but are priced very differently. This analysis separates what has been announced from what has been financed, examines who carries and who captures the value, and sets out the conditions under which an F1 circuit becomes productive infrastructure rather than an expensive piece of national branding.

Rwanda’s IMF Scorecard Is Clean. Its Inflation Problem Is Not.
Regions 7 October 2026

Rwanda’s IMF Scorecard Is Clean. Its Inflation Problem Is Not.

A review in which a government meets every quantitative target for the period should settle the question of whether the programme is working. In Rwanda's case it opens a harder one. The staff-level agreement announced in Kigali on 6 October clears the way for about $35.7 million, roughly 14 per cent of the $250 million, 38-month Extended Credit Facility, pending an IMF Executive Board decision expected in December. Every end-June 2026 target was met. The economy grew 9.7 per cent in the first half. The fiscal deficit narrowed to 4.8 per cent of GDP in 2025/26. Inflation, meanwhile, reached 15.7 per cent in August against a central bank medium-term target of 5 per cent. In February it stood at 9.2 per cent. The gap between a programme that is performing and a price level that is not is the substance of this review. The relevant question is not whether Rwanda deserves the money. It is what the review actually certifies, and what it cannot. The disbursement is small relative to the economy's financing needs. Its value lies in the signal it sends to lenders, rating agencies and private investors that fiscal and debt management are being conducted within agreed limits. That signal is currently being tested by an inflation shock that originates largely in imported oil and fertiliser, channels that fiscal consolidation and monetary tightening can only partly influence. This analysis argues that the first review certifies Rwanda's policy credibility rather than financing its economy, and that the credibility will be priced on how the state handles a supply-side shock it did not create and cannot fully offset. It examines the arithmetic of the facility, the limits of a passed scorecard in a boom year, the transmission of imported inflation through food, transport and credit, the distribution of the adjustment cost, and the institutional load implied by revenue reforms running to 2030. It also sets out a downside scenario in which the strongest first-half numbers become the hardest benchmark to repeat.

Rwanda’s Logistics Pivot: Dar es Salaam Emerges as a Strategic Challenger to Mombasa
Regions 5 October 2026

Rwanda’s Logistics Pivot: Dar es Salaam Emerges as a Strategic Challenger to Mombasa

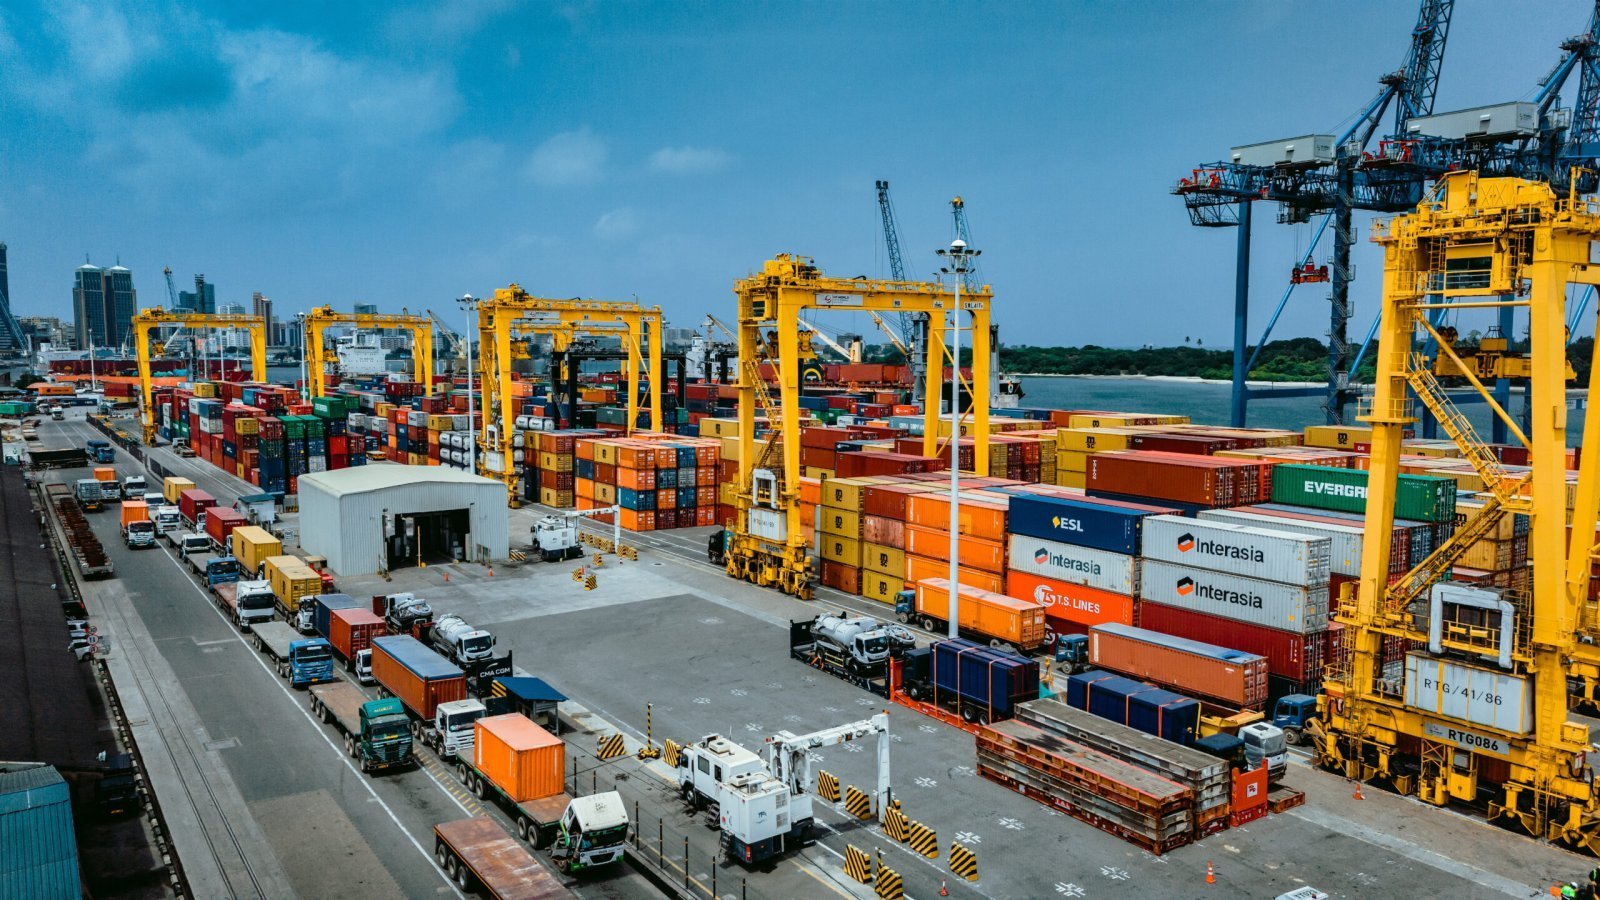
For most of the post-independence period, the economic geography of Rwanda was determined by a single structural fact: a landlocked state of dense population and limited domestic industrial depth had to route the overwhelming majority of its imports and exports through the Port of Mombasa and the Northern Corridor, which meant that the pricing, reliability and political stability of one foreign logistics system functioned as an unlisted component of Rwandan macroeconomic policy. That arrangement is now being reorganised. According to cargo figures reported from Tanzania, Rwanda-bound transit traffic through the Port of Dar es Salaam rose 24 percent to 2.18 million tonnes in the 2025/26 financial year, from approximately 1.75 million tonnes a year earlier, while total cargo handled at the port reached 33.71 million tonnes and transit cargo reached 14.61 million tonnes. What appears to be a statistical improvement in a Tanzanian port is increasingly becoming evidence of a structural shift in the bargaining architecture of East African trade, in which the Central Corridor, supported by terminal concessions, the Standard Gauge Railway and inland facilities such as the Kwala dry port, is acquiring the characteristics of a credible alternative rather than a residual route. The pattern is already operational in petroleum, where Rwanda's first government-backed fuel shipment under its Tanzanian import arrangement, 40,000 metric tonnes, reached the Port of Tanga in July 2026 and a second 40,000-tonne cargo followed through Mombasa in September, which gives the state a sovereign-managed supply channel in each corridor. The significance extends beyond volumes, because the EAC Regional Time Release Study records an average of roughly 22 days and 21 hours from berthing at Dar es Salaam to Kigali ICD against roughly 17 days and five and a half hours from Mombasa, which establishes that the contest has moved from the quay to the corridor. The comparative relevance is considerable: Ethiopia's dependence on Djibouti, Botswana's reliance on South African and Namibian routes, and the Gulf's rerouting of trade after the 2017 Qatar blockade each demonstrate that landlocked and exposed economies convert route diversity into sovereign leverage only when institutional capacity exists on both sides of the border. The current moment matters because Rwanda's industrial, energy and export ambitions are scaling at precisely the point at which two corridors are competing for its cargo.

Five Days, $10.46 Million: Rwanda’s Agricultural Export Economy Faces a Value-Capture Test
Regions 3 October 2026

Five Days, $10.46 Million: Rwanda’s Agricultural Export Economy Faces a Value-Capture Test

Rwanda's disclosure that 8,527 metric tonnes of agricultural exports generated USD 10.46 million between 21 and 25 September 2026 is, on its surface, a short-interval trade statistic, yet the composition of that figure describes the structural position of a landlocked economy that has spent three decades converting a subsistence agrarian base into a managed export system coordinated by the National Agricultural Export Development Board, and that now confronts the limits of that conversion. Coffee supplied USD 4.36 million from 635 tonnes, diversified agricultural products supplied USD 4.07 million from 6,519 tonnes, and the two categories together account for roughly four-fifths of reported value, while the remaining categories of tea, fruit, animal products, vegetables and flowers contribute the balance at sharply different unit values. The framework through which this ledger should be read is not the aggregate total but the spread between a coffee unit value of approximately USD 6,900 per tonne and a diversified commodity unit value near USD 620 per tonne, because that spread defines where Rwanda captures rents and where it merely transits volume. The significance extends beyond agriculture, since the same spread determines how much of the country's foreign-exchange earnings depend on specialty positioning in a price-volatile global coffee market, how much depends on aggregation and processing capacity that remains thinly developed, and how much depends on air cargo, cold-chain and corridor infrastructure that Rwanda does not control unilaterally. The convergence of Gulf capital in aviation, Chinese and European demand in coffee and horticulture, and South Asian demand for bulk commodities positions Rwanda within a reorganising pattern of South-South and Gulf-Africa trade, in which Ethiopia, Kenya, Uganda and Tanzania pursue overlapping strategies with materially larger volumes. The current moment matters because regional competition for export logistics, traceability compliance and processing investment is intensifying while Rwanda's institutional advantage, a coordinating state able to publish and act on granular export data, is most valuable when matched to infrastructure that converts coordination into margin.

The First 80,000 Tonnes, Not the Last: How Maiden Fuel Consignments from Mombasa and Tanga to Kigali Show Rwanda's Dual-Corridor Agreements Moving Fast and Removing the Middlemen from the Fuel Market
Regions 29 September 2026

The First 80,000 Tonnes, Not the Last: How Maiden Fuel Consignments from Mombasa and Tanga to Kigali Show Rwanda's Dual-Corridor Agreements Moving Fast and Removing the Middlemen from the Fuel Market

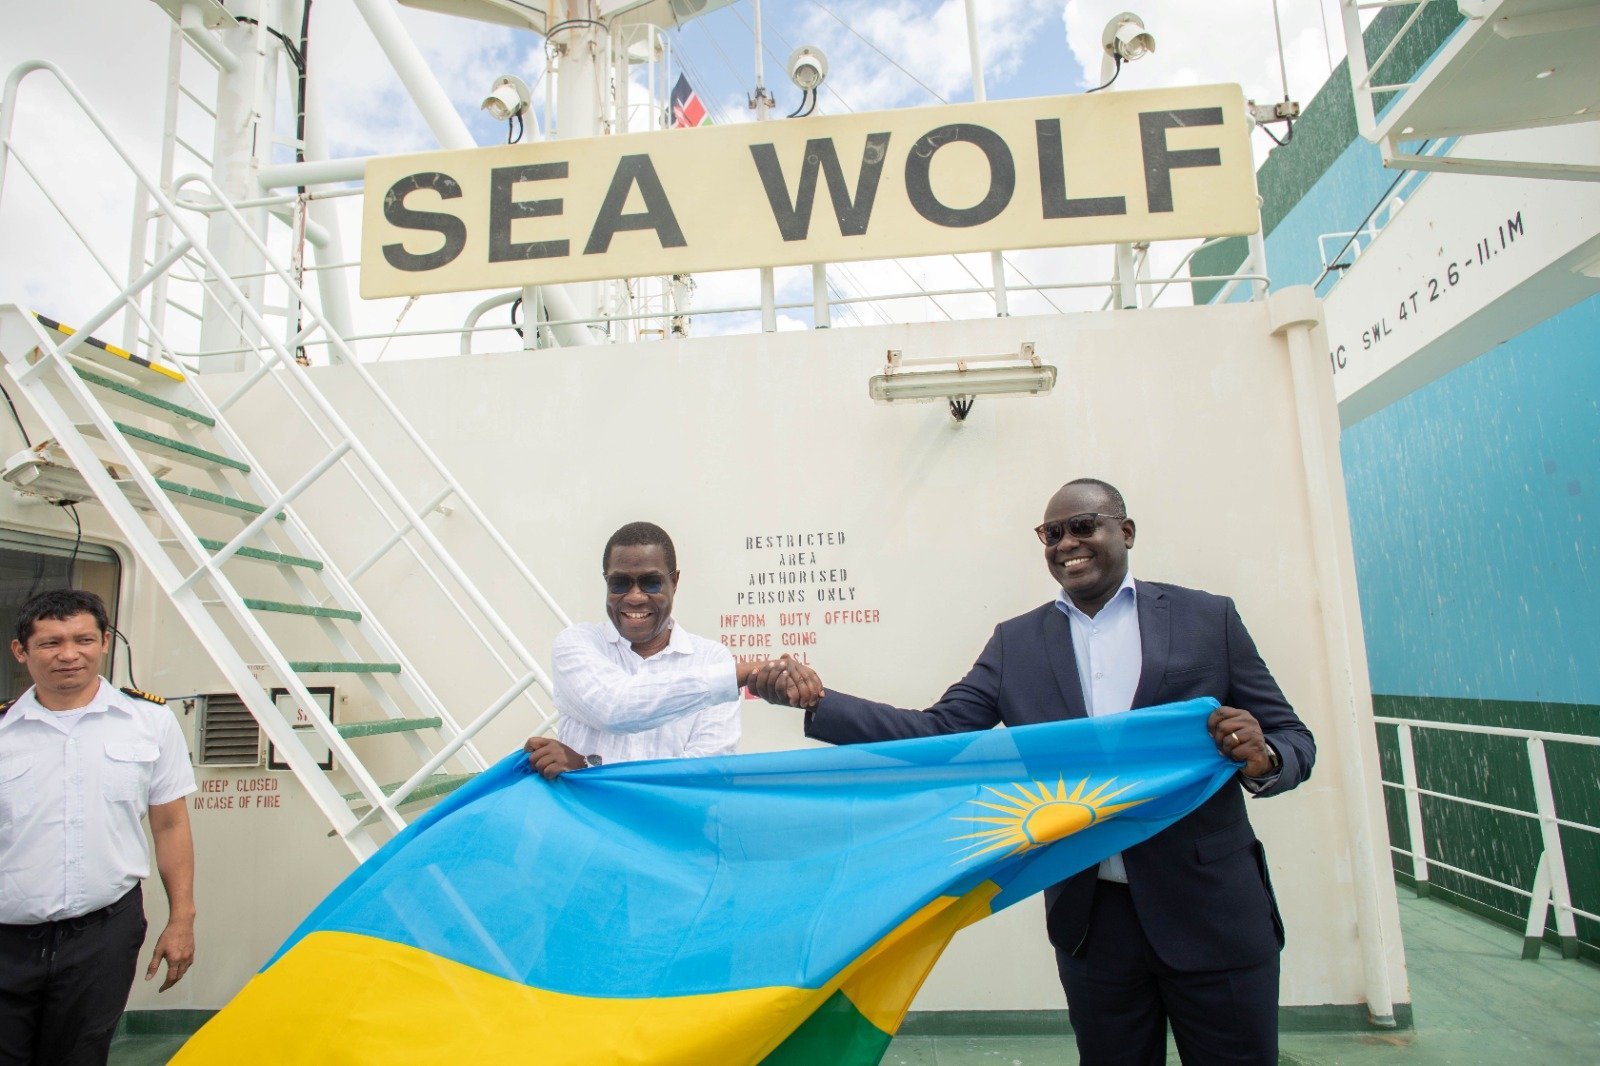
Landlocked states have historically purchased energy security on terms set by transit neighbours, commercial intermediaries and the price cycles of distant refining hubs, and Rwanda's petroleum supply followed that pattern for decades, with imported fuel reaching Kigali through layers of traders and marketers whose margins accumulated between the refinery gate and the forecourt. That framework began to change between July and September 2026, when two maiden government-backed consignments of roughly 40,000 tonnes each arrived through Tanga in Tanzania and through Kipevu Oil Terminal 2 in Mombasa aboard the MT Sea Wolf. The significance extends beyond the 80,000 tonnes, which represents perhaps forty to fifty days of national demand and which are the first cargoes of a continuing programme rather than a one-off delivery. The convergence of a June 2026 government-to-government framework with Kenya, a parallel arrangement with Tanzania, access to Kenya Pipeline Company transport and storage, and a 90-day storage allowance that exceeds what commercial marketers ordinarily receive shows agreements moving from signature to operation within a single quarter, a pace rare in a region where corridor accords have often taken years to become physical flows. The institutional consequence is that the state now sources bulk product directly and uses partner infrastructure, which removes the intermediary layers that previously inflated the landed cost of fuel. The current moment matters because headline inflation reached 15.7 percent in August, the energy category rose 45.4 percent, and the government has spent nearly Rwf48 billion over four months on price support. Kenya's Gulf-backed import deals, Tanzania's bulk procurement tradition, Uganda's national-oil-company consolidation and Ethiopia's Djibouti dependence show that direct state procurement has become a distinct regional instrument, while Singapore, the UAE and Vietnam illustrate mature storage systems and Botswana and Mauritius show how small states use state trading to protect domestic prices. Rwanda is assembling a hybrid of these models, and whether it converts speed of implementation into durable price and reserve discipline will depend on procurement capacity, financing, storage governance and diplomatic continuity with both transit partners.

Rwanda's 100 Changemakers Show How Execution Is Spreading Beyond the State
Regions 28 September 2026

Rwanda's 100 Changemakers Show How Execution Is Spreading Beyond the State

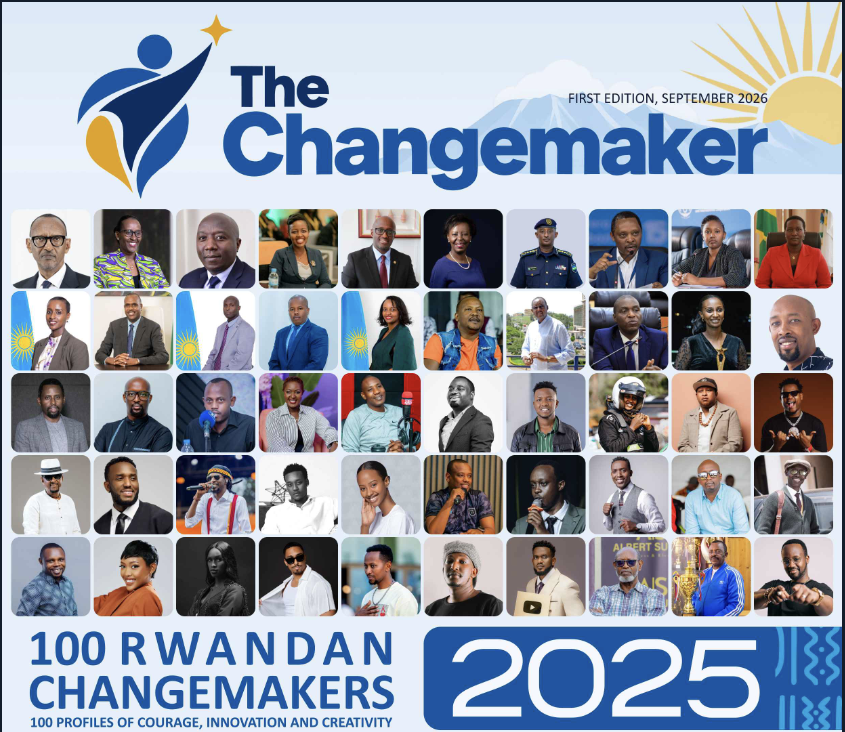
Rwanda's economic story is often told through headline figures such as growth rates, investment totals, tourism arrivals and export volumes, but figures alone do not show who produces the change. The 2025 edition of 100 Rwandan Changemakers, produced by Serengeti Bytes Rwanda, approaches the question through people, profiling 100 individuals across public leadership, business and entrepreneurship, technology, development and NGOs, tourism, media, sports and entertainment, faith, health, agriculture and global allies for Rwanda's progress. Read as a whole, the profiles describe an economy in which state leadership remains central while execution is increasingly shared among banks, manufacturers, technology operators, tourism firms, cultural enterprises, health institutions and foreign investors. The publication's public leadership profiles emphasise industrialisation, including a reported 11.8 percent growth rate in the third quarter of 2025 and a RWF10 billion investment in four priority industrial parks in the 2025/26 fiscal year, both framed within the "Made in Rwanda" agenda. The profiles that follow show what surrounds that agenda: an investment agency converting strategy into projects, banks expanding digital services and SME lending, processors adding value to milk, avocados and other crops, platforms carrying transport, government services and commerce online, and tourism and sport connecting conservation, culture and international events to economic activity. Health, education and inclusion profiles extend the picture to the skills and participation on which higher-value activity depends, while the global allies section shows foreign capital already embedded in Rwandan manufacturing, retail and sport. The index's most useful contribution is therefore not naming 100 important people but showing how many institutions and enterprises now sit between policy ambition and productive capacity. The parallel Tanzanian edition, by comparison, is weighted towards resource-linked enterprise, which makes the Rwandan cohort notable for its concentration in institutions, services and coordinated industrial policy. The evidence has limits, since the publication is a set of profiles rather than a national economic survey and many of its figures come from the organisations and individuals profiled, but as a record of who is trying to build capacity, and in which parts of the economy, it offers a useful view of where Rwanda's next stage of development is taking shape.

Chery's Rwandan Assembly Agreement and the Test of Whether a Landlocked Economy Can Convert Chinese Automotive Relocation Into Regional Industrial Capacity
Regions 19 September 2026

Chery's Rwandan Assembly Agreement and the Test of Whether a Landlocked Economy Can Convert Chinese Automotive Relocation Into Regional Industrial Capacity

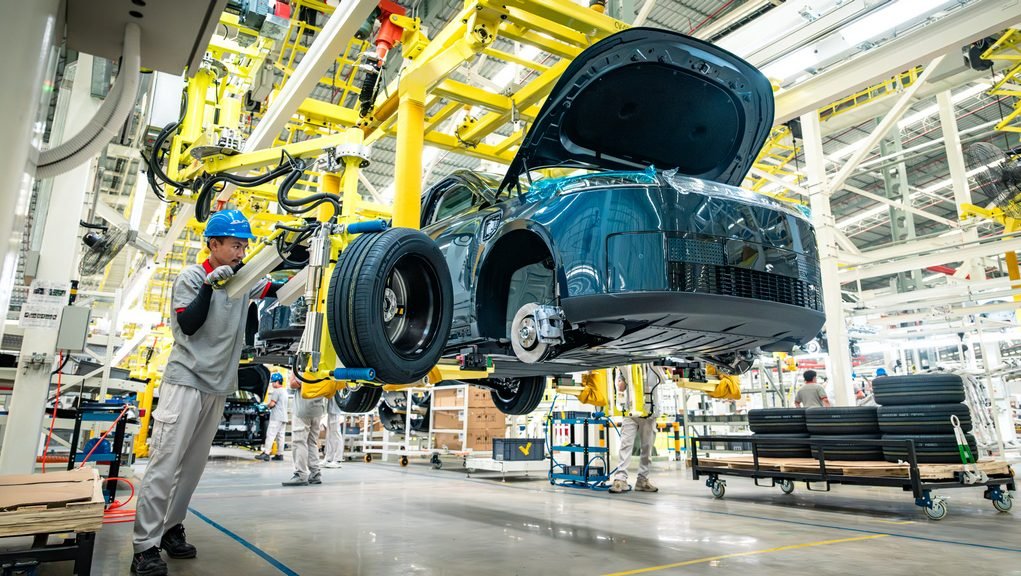
The Cabinet approval on 18 September 2026 of a Strategic Investment Agreement between the Government of Rwanda and Chery Holding Rwanda Ltd extends a sequence of Chinese automotive relocation decisions that has already reached Pretoria, Nairobi, Cairo and Addis Ababa, and it arrives at a moment when China's domestic vehicle market is contracting while its export volumes, at 5.096 million units in the first half of 2026, expand at a pace without recent precedent. African automotive policy has historically oscillated between dependence on used-vehicle imports and low-volume semi-knocked-down assembly, of which Volkswagen's Kigali facility, launched in 2018, remains the nearest local precedent, and neither model produced durable supplier ecosystems outside South Africa, Morocco and Egypt. The structural shift lies in the fact that Chinese manufacturers, facing trade barriers in Europe and North America, are now using local assembly to secure market access, compress logistics costs and align with host-country industrial policy, which converts governments with credible investment frameworks into bargaining counterparties rather than passive export destinations. For Rwanda, the agreement follows the April 2025 memorandum between the Rwanda Development Board and Chery Holding Group, the April 2026 meeting between President Paul Kagame and Chery's vice president and board secretary Xu Hui, and the Ministry of Infrastructure's directive that public institutions procure at least 30 per cent fully electric vehicles, a sequence that suggests demand-side policy and supply-side investment promotion are being deliberately synchronised. The published resolutions disclose no investment value, site, capacity or timeline, and the indicative $39.25 million and 2,000 direct jobs in RDB's electric-car assembly material cannot be attributed to Chery, which places the analytical weight on institutional design rather than announced figures. Ethiopia's prohibition on fossil-fuel vehicle imports and its 17 operating assembly plants, Kenya's CKD partnerships, Uganda's state-backed Kiira Motors programme and Tanzania's import-oriented vehicle market define the regional field in which Rwanda's proposition will be priced. The question that determines the outcome is whether a domestic market of roughly 14 million people, a landlocked supply chain and a modest grid can be converted, through EAC market access, local content rules and supplier development, into a platform that Chery treats as a regional production node rather than a showroom with a workshop attached.

Rwanda's Industrial Turn: How a 9.4% Expansion Is Rewriting the Architecture of East Africa's Fastest-Growing Economy
Regions 16 September 2026

Rwanda's Industrial Turn: How a 9.4% Expansion Is Rewriting the Architecture of East Africa's Fastest-Growing Economy

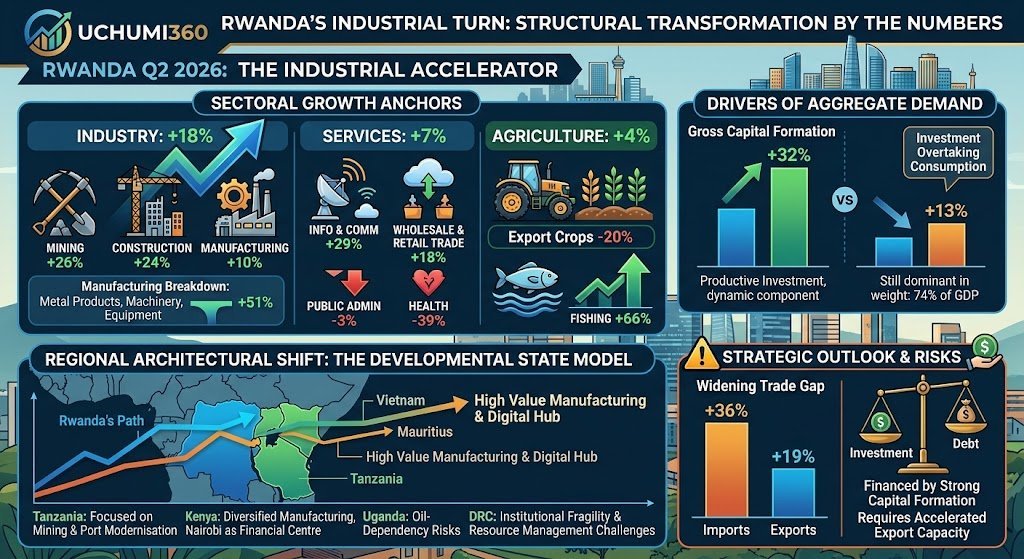
Rwanda's economy expanded by 9.4% year-on-year in the second quarter of 2026, a figure that on its own would be unremarkable in a country whose growth trajectory over the past three decades has repeatedly outpaced regional and continental averages. What distinguishes this quarter, and what elevates it from a routine statistical release to a structural marker, is the composition beneath the headline number. According to National Institute of Statistics of Rwanda (NISR) data, GDP at current market prices reached FRW 7.174 trillion, up from FRW 5.799 trillion a year earlier, but the more consequential detail is that industry expanded by 18%, mining and quarrying by 26%, construction by 24%, and gross capital formation by 32%, while agriculture grew by only 4% and export-crop production contracted by 20%. This divergence signals a transition already underway in the underlying structure of the Rwandan economy, one in which the traditional agrarian base that has anchored rural livelihoods and export earnings for decades is being progressively overtaken, in relative weight if not in absolute output, by an industrial and services complex built on construction, manufacturing, mining and information and communication technology. The historical framing matters here. Rwanda's post-1994 development model was constructed around agricultural modernisation, services-led urban growth and an aggressive positioning strategy as a regional hub for finance, conferences and technology, a model that mirrors, in partial form, the sequencing used by Mauritius in the 1980s and Vietnam in the 1990s, both of which used targeted industrial policy to compress decades of structural transformation into a generation. The geopolitical context is equally material. As global supply chains reconfigure around nearshoring, critical mineral security and diversified sourcing away from concentrated manufacturing hubs, landlocked economies with governance discipline and logistics ambition, such as Rwanda, are positioned to capture a share of relocating industrial capacity, provided that transport corridors, energy capacity and financing architecture keep pace with demand. The institutional significance of the Q2 data lies in what it implies about the credibility of Rwanda's National Strategy for Transformation and its successor frameworks, which have long targeted a shift away from commodity-dependent, agriculture-heavy growth toward a diversified, higher value-added structure. The comparative relevance extends across the East African Community, where Kenya's larger and more diversified industrial base, Tanzania's mineral and port-driven expansion, Uganda's oil-anchored medium-term outlook and the Democratic Republic of Congo's resource-extraction dependency each represent alternative paths through the same regional transformation. Why this matters now is straightforward: the widening gap between import growth of 36% and export growth of 19% is generating external pressure at precisely the moment industrial policy needs sustained capital inflows, meaning the credibility of Rwanda's investment and trade architecture will be tested well before the structural transformation it is financing has fully matured.

Dangote Refinery IPO Puts Rwanda’s Financial Hub Ambitions to the Test
Regions 15 September 2026

Dangote Refinery IPO Puts Rwanda’s Financial Hub Ambitions to the Test

The launch of the Dangote Petroleum Refinery and Petrochemicals initial public offering on September 14 represents more than the monetisation of a single industrial asset in Lagos. It constitutes a stress test of a structural question that has shadowed African capital markets since the founding of the African Continental Free Trade Area: whether capital, not merely goods, can move across the continent's borders with the fluidity that trade liberalisation has promised but rarely delivered. Valued at between $40 billion and $50 billion, the refinery is the largest single-train petroleum processing facility in the world, and its decision to open a retail-accessible offering priced at roughly $0.40 per share reframes an asset historically reserved for sovereign wealth funds and multinational energy conglomerates into an instrument nominally available to any investor across the continent with a functioning brokerage relationship. That Rwandan investors can now access this offering through United Capital Financial Services PLC, a firm dual-licensed by the National Bank of Rwanda and the Capital Market Authority, is significant less for the transaction volume it is likely to generate in the near term and more for what it reveals about the architecture, still largely improvised, through which African capital markets interoperate. The Rwanda Stock Exchange's acknowledgment that a possible cross-listing or dual listing is under discussion indicates that this is not a passive retail distribution exercise but an early test of whether Kigali's stated ambition to function as a regional financial and investment hub can be substantiated through actual cross-border equity mechanics rather than policy language. The comparison that matters here is not primarily with Lagos but with the institutional frameworks of Nairobi, Dar es Salaam, and Kampala, each of which has pursued a different model of capital market depth, and with the sovereign strategies of smaller, capital-scarce states such as Mauritius and Singapore that converted limited domestic capital bases into disproportionate financial intermediation capacity. The Dangote offering, in this sense, functions as a diagnostic: it tests whether Rwanda's regulatory infrastructure, still comparatively thin in transaction volume relative to Nairobi's, can absorb and channel genuine investor demand for continental industrial assets, and whether the RSE's ambitions toward cross-listing reflect a coherent capital markets strategy or an opportunistic response to a single high-profile transaction.

Rwanda’s B+ Rating: The Institutional Capital Behind Its Growth
Regions 14 September 2026

Rwanda’s B+ Rating: The Institutional Capital Behind Its Growth

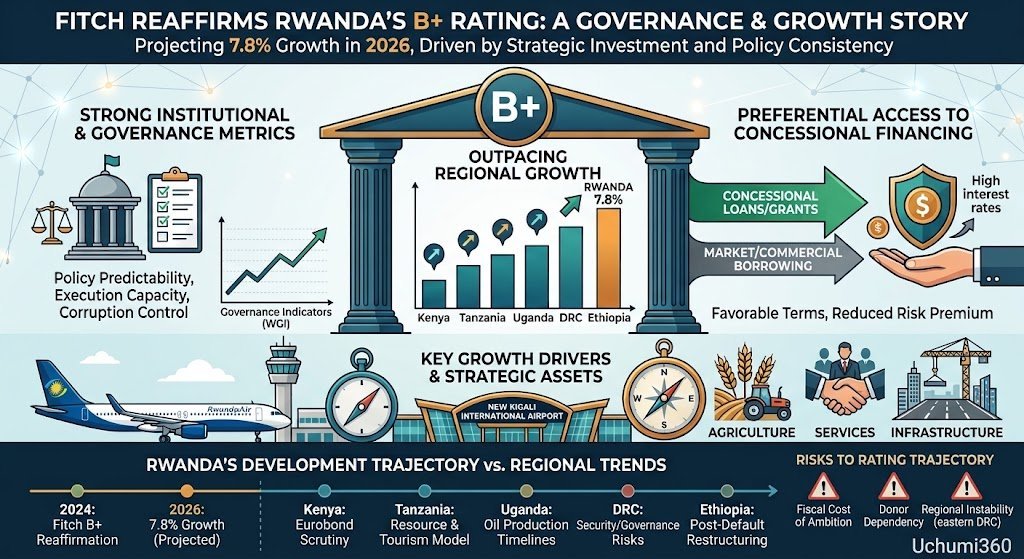
A sovereign credit rating is, at its core, an institutional judgment about the probability that a state will honor its obligations under conditions of stress, and Fitch Ratings' affirmation of Rwanda's Long-Term Foreign-Currency Issuer Default Rating at B+ with a Stable Outlook should be read within that narrower, more technical frame before it is read as a broader endorsement of national trajectory. Rwanda's Ministry of Finance and Economic Planning announced the reaffirmation on September 14, 2026, framing it around the country's governance indicators, growth potential, and the concessional structure of public debt, alongside continued financial and technical backing from development partners. That framing captures the strengths Fitch cites, but the fuller rating action commentary shows a more layered calculation underneath it. The agency's Sovereign Rating Model, a proprietary eighteen-variable regression framework, assigns Rwanda a score equivalent to a straight 'B' rating, one full notch below where the country actually sits; it is only through Fitch's qualitative overlay, a discretionary one-notch upward adjustment applied specifically to reflect Rwanda's access to concessional financing and its sustained growth rate, that the B+ rating and its Stable Outlook are reached at all. This distinction matters because it reframes the rating as a conditional judgment rather than a straightforward reading of fundamentals: the current account deficit is forecast to widen to nearly 15 percent of GDP in 2026, driven by resilient domestic demand, a surge in imports tied to the New Kigali International Airport in Bugesera construction project, and elevated fuel and fertilizer costs linked to spillovers from the Iran war. Net external debt is projected to reach 63 percent of GDP in 2026, well above the 48 percent median for 'B' rated sovereigns, while reserve coverage is forecast at just 3.2 months of current external payments, thinner than the 4.2 month median among comparable peers. General government debt, having peaked near 74 percent of GDP in the fiscal year ending June 2025, is expected to average 65 percent of GDP across FY27 and FY28, still above the 56 percent 'B' category median. What emerges from Fitch's full commentary, read in its entirety rather than through the Ministry of Finance's summary framing, is a rating built on a genuine trade-off: institutional and governance strength offsetting external and fiscal metrics that, on their own, would place Rwanda a notch lower on Fitch's scale. Understanding how that trade-off is constructed, and how it compares with the methodology applied to Rwanda's regional peers, is the more useful exercise than treating the affirmation as a simple pass or fail.