Uchumi360 Author Archive

Author: Gaston Rucibigango

44 articles Latest: October 26, 2026
The China-Rwanda Infrastructure Deal That Could Reshape Kigali’s Eastward Corridor
Regions 9 September 2026

The China-Rwanda Infrastructure Deal That Could Reshape Kigali’s Eastward Corridor

The groundbreaking of the Prince House-Giporoso-Masaka road on September 8 is, on its surface, a municipal infrastructure event: a 10.3 to 10.4 kilometre urban arterial corridor connecting central Kigali to the city's eastern industrial and institutional core. Read through a structural lens, however, the project functions as a compressed case study in how a small, landlocked, resource-constrained state converts external grant capital into domestic logistics capacity while simultaneously deepening a bilateral relationship whose origins trace back to a 2018 head-of-state visit rather than a routine procurement cycle. The Government of China's contribution of over Rf95 billion against Rwanda's own Rf35 billion, combined with an expropriation bill already exceeding Rf30 billion covering more than 530 valued properties, places the total project cost above Rf130 billion, making it one of the more capital-intensive single urban transport interventions in Rwanda's recent infrastructure history. The historical framing matters because Rwanda has spent the past decade constructing an institutional identity around disciplined public investment management, and a project of this scale, financed almost entirely through Chinese grant capital and executed by a state-owned Chinese contractor, tests whether that discipline extends to large, externally financed, time-compressed builds rather than the smaller, more easily governed domestic capital projects that have historically anchored Rwanda's infrastructure narrative. The geopolitical context is equally load-bearing. The corridor was jointly identified by President Xi Jinping and President Paul Kagame during Xi's 2018 state visit, which places it inside the architecture of the Belt and Road Initiative and the Forum on China-Africa Cooperation rather than treating it as an isolated bilateral grant, and this distinction shapes how the project should be read by regional peers, multilateral financiers, and political risk analysts tracking the durability of Chinese infrastructure commitments on the continent. Economically, the corridor's significance is inseparable from its function as a logistics artery: it links the Kigali Special Economic Zone, the Eastern Industrial Zone, and the Masaka Medical Complex to routes running toward the Rusumo border crossing, the Inland Dubai Port, Kigali International Airport, and the emerging Bugesera airport corridor, meaning the road's completion timeline directly affects the cost structure of firms operating along one of Kigali's principal trade and logistics axes. Institutionally, the decision by the Ministry of Infrastructure to publicly challenge the contractor to compress delivery from 30 months to as little as 15, while simultaneously embedding a formal skills-transfer and technical training program between Chinese and Rwandan engineering teams at the construction site, signals an attempt to extract not just an asset but institutional capability from the financing relationship. Comparatively, few peer states in the region have paired large-scale Chinese urban infrastructure financing with an explicit, publicly stated compression mandate and a parallel technical capacity-building program in the same announcement, and that combination is what elevates this from a routine road opening to a data point in Rwanda's broader positioning as a state that treats infrastructure financing as a vehicle for institutional upgrading rather than simple asset acquisition.
Rwanda's Intelligence Layer: How the State Is Turning Agricultural Data Into a National Development Instrument
Regions 8 September 2026

Rwanda's Intelligence Layer: How the State Is Turning Agricultural Data Into a National Development Instrument

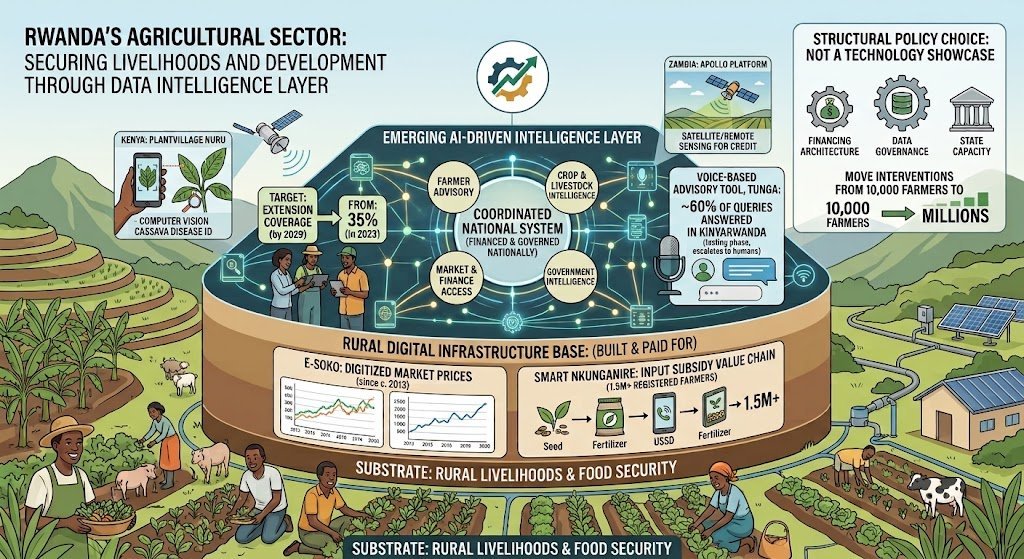
Rwanda's agricultural sector has never been merely a line item in the national accounts. It is the substrate on which rural livelihoods, food security and, increasingly, the credibility of the country's development model rest, and it is against that backdrop that the government's emerging artificial intelligence agenda for agriculture deserves to be read as a structural policy choice rather than a technology showcase. The framework through which Rwanda is approaching this problem did not begin with algorithms. It began, roughly a decade ago, with the unglamorous work of digitising market prices through e-Soko and, later, digitising the input subsidy value chain through Smart Nkunganire, a platform that today carries more than 1.5 million registered farmers transacting via USSD. That sequencing matters structurally, because it means Rwanda is not attempting to leapfrog into artificial intelligence from a low base of digital infrastructure, in the manner of several donor-funded pilots elsewhere on the continent, but is instead attempting to extract a new intelligence layer from data rails it has already built and paid for. Minister of ICT and Innovation Paula Ingabire's remarks at the Africa Food Systems Forum in Kigali, delivered during a high-level roundtable on September 1, 2026, made this sequencing explicit and, in doing so, offered a rare degree of specificity about targets that are usually left deliberately vague in African digital strategy documents: extension coverage rising from 35 percent in 2023 to a targeted 69 percent by 2029, reaching more than 2.5 million farmers, alongside a voice-based advisory tool, Tunga, that during testing answered approximately 60 percent of farmer queries correctly in Kinyarwanda before escalation to a human expert. The comparative significance is immediate. Kenya's PlantVillage Nuru has already demonstrated, according to CGIAR-cited research, that computer vision can out-diagnose farmers and extension agents on cassava disease identification, while Zambia's Apollo platform has shown that satellite and remote-sensing data can substitute, at least partially, for the credit histories that formal lenders in agrarian economies have never been able to build. What Rwanda is proposing is not a single application drawn from that menu but an attempt to sequence farmer advisory, crop and livestock intelligence, market and finance access, and government intelligence into one coordinated system, financed and governed nationally rather than assembled from disconnected donor pilots. Whether that ambition is achievable depends less on the sophistication of the underlying models than on financing architecture, data governance, and the state capacity required to move interventions that work for 10,000 farmers to interventions that work for millions, a transition point at which most African digital agriculture initiatives to date have stalled.

Inside RSSB's Triple Acquisition: How Rwanda's Pension Fund Is Rebuilding the Architecture of Domestic Capital
Regions 2 September 2026

Inside RSSB's Triple Acquisition: How Rwanda's Pension Fund Is Rebuilding the Architecture of Domestic Capital

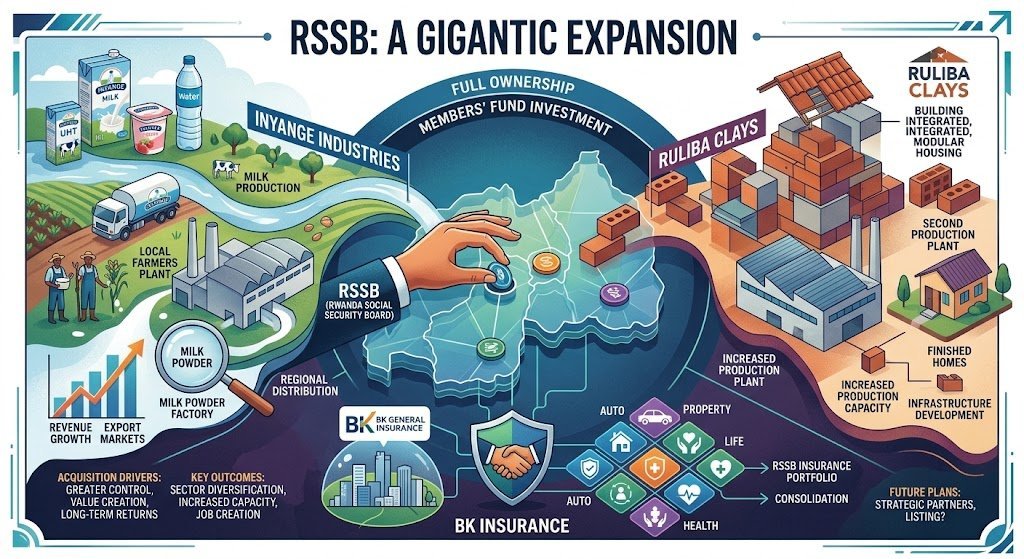
Between late August and early September 2026, the Rwanda Social Security Board executed three transactions that, taken individually, might have registered as routine corporate consolidations, but which together constitute a structural signal about how Rwanda intends to organise domestic capital for the next phase of its development trajectory. RSSB converted its existing minority and majority stakes in Inyange Industries and Ruliba Clays into full ownership, while simultaneously acquiring BK General Insurance and folding it into an insurance platform already anchored by SONARWA General Insurance and SONARWA Life Assurance. The historical framing matters because none of these were greenfield entries into unfamiliar sectors. RSSB had already provided the patient capital that financed Inyange's milk powder plant and Ruliba's second production line at Rugende, meaning the fund was not speculating on new industries but consolidating control over assets whose productive capacity it had already helped build. The structural shift lies in what full ownership permits that partial ownership did not: unified capital allocation, faster governance cycles and the ability to sequence a company's evolution from state-financed capacity expansion toward commercial maturity and, eventually, public market participation. This sequencing pattern, financing capacity first and consolidating ownership once utilisation curves justify it, is not unique to Rwanda, but the discipline with which RSSB has articulated valuation methodology, a net-asset-value anchor for Inyange and Ruliba against an independently reviewed earnings-based valuation for BK General Insurance, distinguishes this transaction set from the more opaque state-enterprise consolidations seen elsewhere on the continent. The geopolitical and economic context is that Rwanda, a landlocked economy without the mineral endowments of neighbouring Tanzania or the Democratic Republic of Congo, has increasingly relied on institutional capital discipline, logistics corridor positioning and financial-sector depth as substitutes for resource rents, and RSSB's evolution into a more assertive institutional owner is part of that substitution strategy. The institutional significance extends to how Rwanda is signalling its long-term intent to build public-market depth: RSSB's leadership has explicitly tied these acquisitions to a future listing pathway on the Rwanda Stock Exchange and potentially the Nairobi Securities Exchange, positioning full ownership not as an end state but as a preparatory phase before capital markets absorb a portion of the value created. Comparative relevance lies in contrasting Rwanda's approach with mineral-economy peers in the region, where sovereign wealth has more frequently been deployed reactively around extractive windfalls rather than proactively around agro-industrial and financial-sector consolidation. Why this matters now is a function of timing: RSSB's assets under management have doubled over five years to Rwf3.9 trillion, its investment returns have compounded at double-digit rates for two consecutive years, and the fund has simultaneously cleared two consecutive years of unqualified audit opinions from the Office of the Auditor General, giving it both the balance sheet capacity and the governance credibility to absorb three simultaneous acquisitions without triggering the kind of institutional overreach concerns that typically accompany rapid state-linked expansion.

Rwanda's Tungsten Rise: How the World's 7th-Largest Producer Is Gaining Strategic Leverage
Regions 27 August 2026

Rwanda's Tungsten Rise: How the World's 7th-Largest Producer Is Gaining Strategic Leverage

The global tungsten market has, for more than two decades, functioned as a near-monopoly disguised as a commodity market, with China's control of roughly four-fifths of world production giving Beijing a lever over an input that is structurally irreplaceable in cutting tools, aerospace components, and defense-grade munitions, a dependency that Western industrial and defense planners have only recently begun to treat with the urgency once reserved for rare earths. Against this backdrop, Rwanda's rise to become Africa's largest tungsten producer and the world's seventh-largest, anchored by the Nyakabingo mine in Rulindo District and operationalised through the London-listed Trinity Metals, represents a structural rather than incidental development. The country's output, at approximately 1,300 metric tonnes against a global total near 85,000 tonnes according to United States Geological Survey figures, appears numerically modest, yet the significance of a critical-minerals position is not measured by volume share alone but by the degree to which supply is verifiable, politically stable, and geographically distinct from the dominant producer. It is this triad, traceability, stability, and distance from Beijing's sphere of control, that has allowed Rwandan concentrate to account for as much as one-fifth of primary tungsten consumption at Global Tungsten & Powders in Pennsylvania, a supply relationship that plugs the world's seventh-largest tungsten producer directly into the American defense-industrial base and converts a modest production ranking into outsized strategic leverage. This is a different category of relevance than the extractive relationships that have historically defined Africa's position in global commodity chains, where volume was the only currency and processing, standard-setting, and pricing power remained offshore. The Rwandan case also arrives at a moment when the government's National Strategy for Transformation 2 has set explicit mineral-revenue targets, when 3T mineral exports helped narrow the country's trade deficit in 2025, and when the state faces a genuine strategic choice between continuing to export raw concentrate for reliable foreign-exchange earnings or committing capital and institutional capacity toward downstream processing into higher-margin intermediate products such as ammonium paratungstate. Understood in isolation, Rwanda's tungsten sector is a mining success story. Understood systemically, against the backdrop of a Democratic Republic of Congo whose vastly larger mineral endowment remains hostage to weak traceability enforcement and cross-border informality, and against a Tanzania and Uganda still building the institutional scaffolding to convert mineral wealth into industrial policy, Rwanda's tungsten position illustrates how governance capacity, more than geological endowment, has become the primary determinant of which African states are admitted into premium Western supply chains during this period of critical-minerals realignment.

What a Rwandan Equity Stake in the Dangote Lamu Refinery Signals About Kigali's Energy Sovereignty Strategy
Regions 24 August 2026

What a Rwandan Equity Stake in the Dangote Lamu Refinery Signals About Kigali's Energy Sovereignty Strategy

Rwanda's evaluation of an equity stake in the Dangote Group's proposed refinery at Lamu, Kenya, is not a transaction that can be read through the narrow lens of retail fuel prices. It sits inside a longer historical arc in which landlocked, resource-poor states have periodically confronted the same structural choice: remain a price-taking consumer at the terminus of someone else's supply chain, or acquire a claim on the infrastructure that determines the terms of that supply. Singapore made this choice with refining and bunkering capacity in the 1960s, converting a transit port into a pricing hub for the entire Asia-Pacific petroleum trade. The United Arab Emirates made a comparable choice decades later, using sovereign capital to move from crude exporter to integrated downstream operator through Abu Dhabi National Oil Company's refining and petrochemical expansion. Rwanda's position is structurally different, since it holds no hydrocarbon reserves of its own and imports the entirety of its petroleum needs, but the logic of the decision facing Kigali is the same logic that has shaped every serious energy strategy pursued by a small, trade-dependent state: ownership of infrastructure changes a country's bargaining position even when it cannot change the underlying commodity price. Officially confirmed in July 2026, Dangote Industries selected Lamu as the site for a refinery designed to process 700,000 barrels of crude per day, a facility conceived from the outset as a regional supply node for East and Central Africa rather than a domestic Kenyan asset alone, and the company has structured a collective 30 percent equity pool worth approximately $1.5 billion specifically to draw regional governments into co-ownership. Kenya has already signalled a $500 million commitment for a 10 percent share. For Rwanda, whose 2024 petroleum import bill reached roughly $680 million against national consumption of 571 million litres and growing, the decision arrives at a moment when Kigali has already begun re-architecting its fuel logistics away from the Tanzania-routed Central Corridor and toward a Northern Corridor system anchored in Kenya, following the bilateral framework signed with Nairobi on June 29, 2026. The refinery question and the corridor question are, in practical terms, a single question about whether Rwanda participates in the ownership layer of a supply chain it will in any case depend on for the foreseeable future, and it is this convergence of infrastructure timing, capital availability, and strategic sequencing that makes the Lamu decision one of the more consequential economic choices facing Kigali this decade.

The Billion-Dollar Harvest: How Rwanda Engineered Its Way Past $1B in Agricultural Exports, and What the 24.3% Leap Reveals About State Capacity, Logistics Power, and the New Economics of Trust
Regions 16 August 2026

The Billion-Dollar Harvest: How Rwanda Engineered Its Way Past $1B in Agricultural Exports, and What the 24.3% Leap Reveals About State Capacity, Logistics Power, and the New Economics of Trust

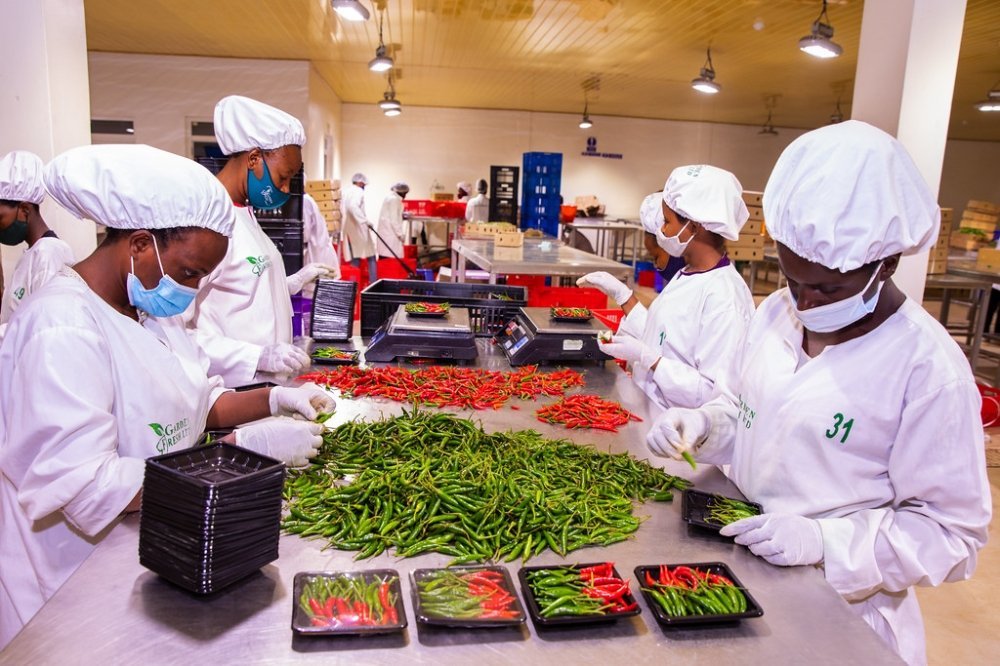
Rwanda's announcement that agricultural exports generated $1.1 billion in the fiscal year spanning July 2025 to June 2026, an increase of 24.3 per cent over the $893 million recorded the previous year, is not simply a trade statistic. It is a data point that closes one strategic chapter and opens another. For a landlocked economy with no direct access to a seaport, no significant hydrocarbon endowment, and a domestic market too small to absorb meaningful industrial output, the capacity to convert agricultural production into hard currency earnings at this scale is a test of institutional coordination rather than a test of soil fertility alone. The National Agricultural Export Development Board, the state agency responsible for engineering this outcome, has spent the better part of a decade building the connective tissue between farm and international buyer: quality testing infrastructure, traceability systems, pack houses, specialty coffee competitions, and market access diplomacy conducted through trade fairs and buyer linkage programmes. None of these instruments are individually remarkable. What is structurally significant is that Rwanda has sequenced them into a coherent export architecture at a moment when global food systems are tightening their compliance requirements, when regional peers are still negotiating the basic infrastructure of agricultural logistics, and when landlocked states more broadly are being forced to reconsider what economic sovereignty means in a world of hardening supply chains. This places the milestone in the same analytical category as Ethiopia's coffee sector reforms, Vietnam's transition from subsistence rice exporter to a top-tier global agricultural exporter within two decades, and Mauritius's earlier pivot from single-crop sugar dependency toward a diversified, quality-driven export base. The comparison is instructive because it clarifies what the $1.1 billion figure actually measures: not the size of Rwanda's harvest, but the sophistication of the institutional system converting that harvest into internationally trusted, traceable, certifiable commercial product. Understanding why this matters now requires situating Rwanda's agricultural strategy within its wider national planning architecture, the Second National Strategy for Transformation and the Fifth Strategic Plan for Agriculture Transformation, and within the comparative experience of states that have used export sophistication as a substitute for the natural advantages they lacked.

Rwanda's Suspension of 52 Imported Alcoholic Beverages Signals a Structural Reckoning for East Africa's Quality Infrastructure and the Region's Bid for Institutional Credibility in a Reorganising Global Trade System
Regions 6 August 2026

Rwanda's Suspension of 52 Imported Alcoholic Beverages Signals a Structural Reckoning for East Africa's Quality Infrastructure and the Region's Bid for Institutional Credibility in a Reorganising Global Trade System

On August 5, 2026, the Rwanda Food and Drugs Authority suspended the importation of 52 alcoholic beverage listings sourced from six countries and ordered their immediate recall from the domestic market, an act that on its surface reads as a routine public health intervention but that, on closer institutional reading, functions as a stress test of the regulatory architecture underpinning the East African Community's twenty-year project of market integration. The decision did not arrive in isolation. It followed the closure of more than 130 domestic manufacturing facilities, the revocation of every ethanol import licence in the country, and a documented public health emergency in which Rwandan health authorities recorded at least 50 deaths and more than 100 cases of vision impairment linked to methanol contaminated alcohol during the first half of 2026. The sequencing matters because it establishes that Kigali's move against foreign brands, including Tanzania's Konyagi, one of East Africa's most commercially entrenched spirit brands, was not a protectionist opening gambit but the terminal phase of a domestic enforcement campaign that had already dismantled a significant share of the country's own production base. That distinction carries structural weight. Regional economic communities built on mutual recognition protocols, the East African Community's Standardisation, Quality Assurance, Metrology and Testing regime foremost among them, depend on the credible assumption that a certification issued in one member state can be trusted in another without duplicated inspection. When a regulator in one jurisdiction unilaterally withdraws that trust for products bearing valid regional certification marks, it does not merely interrupt a supply chain. It signals to investors, development financiers and trading partners that the underlying institutional guarantee, the thing that is supposed to reduce transaction costs and justify the entire architecture of regional integration, cannot yet be relied upon under stress. This matters for reasons well beyond Kigali's bar shelves. The episode arrives as the East African Community negotiates its position within the African Continental Free Trade Area, as Rwanda positions itself as a logistics and services hub for a landlocked regional economy, and as global capital increasingly prices sovereign and regional risk according to the observable strength of regulatory institutions rather than headline growth figures alone. The comparative lesson, drawn from how mature economies manage cross border food and beverage safety without triggering diplomatic or commercial rupture, is that institutional capacity, not enforcement severity, determines whether a public health intervention strengthens or corrodes a regulatory system's long term credibility.

Inside Rwanda's ICT Employment Surge: How a 0.4% Workforce Segment Became the Clearest Signal of the Country's Digital Industrial Strategy
Regions 22 July 2026

Inside Rwanda's ICT Employment Surge: How a 0.4% Workforce Segment Became the Clearest Signal of the Country's Digital Industrial Strategy

Between the second quarter of 2025 and the second quarter of 2026, Rwanda's information and communication technology sector added roughly seven thousand jobs, taking total ICT employment from an estimated twelve thousand workers to approximately nineteen thousand. On a percentage basis that expansion, 62.6% year on year, outpaced every other sector tracked in the national labour force data, and did so against a backdrop in which aggregate national employment grew by a comparatively modest 2.7%, reaching 4.7 million workers economy-wide. The scale mismatch between these two figures, a sector growing more than twenty times faster than the national average while still accounting for only about 0.4% of the workforce, is the analytical starting point for understanding what is actually happening inside Rwanda's digital economy. This is not yet a mass employment story. It is a formation story, a period in which a small, high-value segment of the labour market is being deliberately constructed through coordinated state instruments rather than emerging organically from private demand alone. The ICT Sector Strategic Plan for 2024 to 2029 sets an explicit target of fifty thousand digital jobs, meaning the current base of nineteen thousand represents progress toward a five-year mandate rather than a terminal outcome. That target sits inside a broader architecture, GovTech digitisation of public services through platforms such as Irembo, venture financing through the Rwanda Innovation Fund, physical and institutional incubation through spaces such as Norrsken House Kigali, and skills pipelines through the Rwanda Coding Academy and the Digital Ambassadors Programme, each addressing a different constraint in the sequence that converts policy intention into payroll. For investors, multilateral financiers, and regional competitors, the relevant question is not whether Rwanda's ICT sector is growing, since the labour force data already answers that, but whether the growth rate is structurally sustainable once the low base effect fades, whether the roles being created carry export value beyond the domestic market, and whether Rwanda's small population and landlocked geography impose a ceiling on how large this sector can become relative to peers pursuing similar strategies with larger domestic markets or more established outsourcing brand recognition. This analysis works through the mechanics of that question, comparing Rwanda's trajectory against Kenya's more mature outsourcing sector, Vietnam's export-manufacturing pivot as a template for state-sequenced industrial transition, and Mauritius's experience converting a small-state services economy into an internationally credible one.

Rwanda's Investor Relations Score Signals a Deeper Structural Shift in How Small States Compete for Global Capital
Regions 20 July 2026

Rwanda's Investor Relations Score Signals a Deeper Structural Shift in How Small States Compete for Global Capital

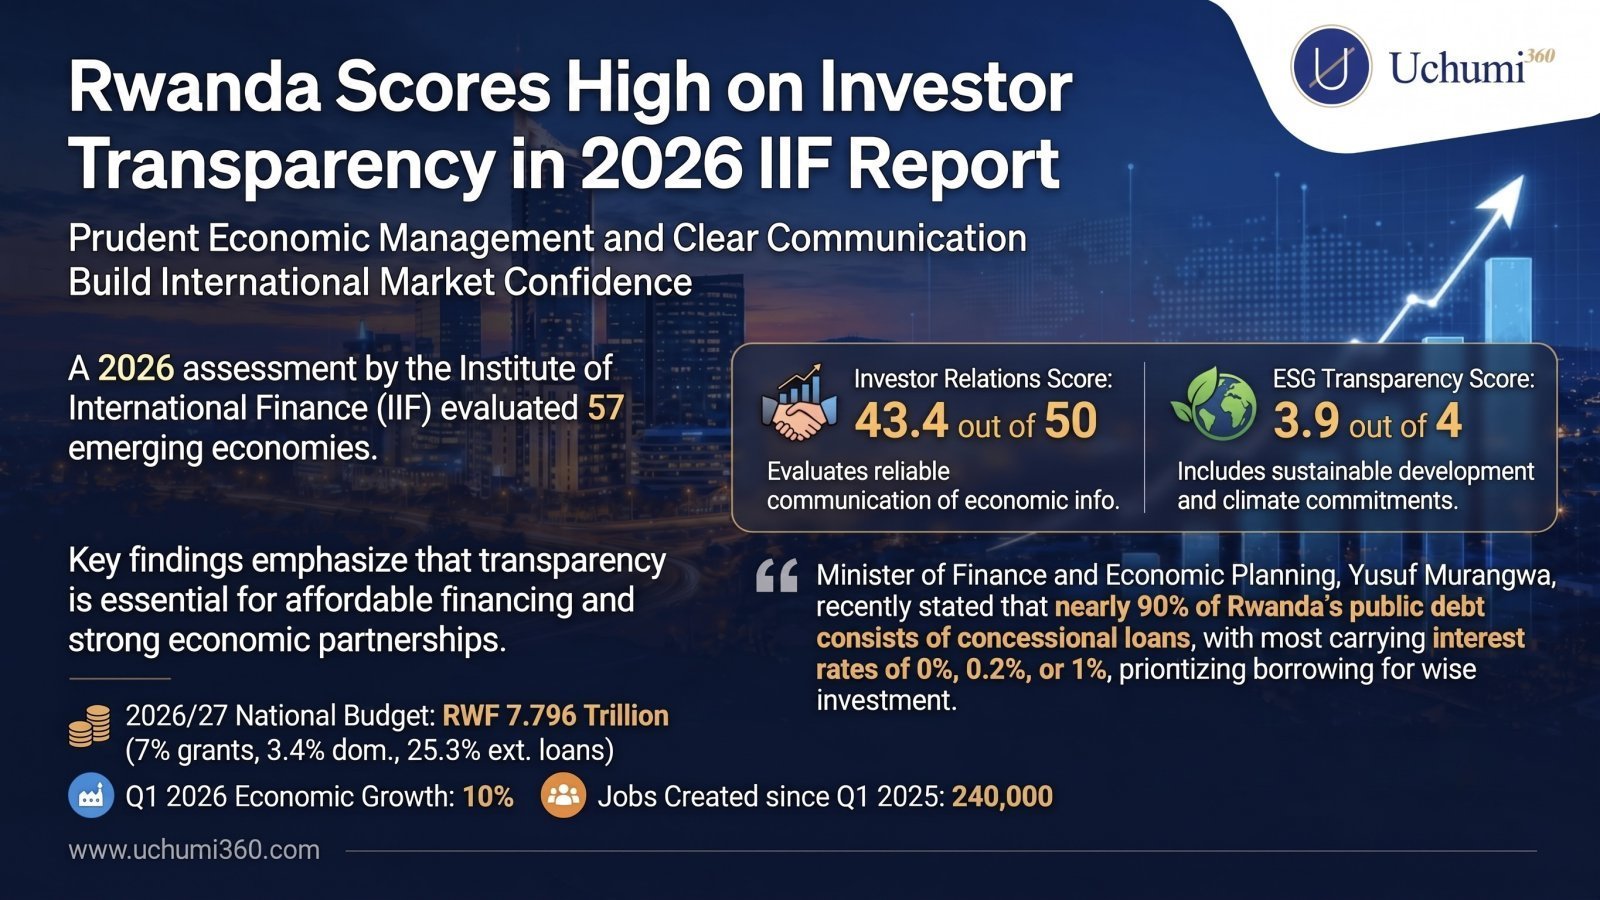
For most of the last three decades, the global conversation about sovereign creditworthiness in Africa has been dominated by a narrow set of variables: reserve buffers, current account balances, and the binary judgment of the three major credit rating agencies. What the Institute of International Finance's 2026 assessment of investor relations across 57 emerging and developing economies quietly confirms is that this framework is incomplete, and that a second, less visible axis of sovereign competitiveness has become decisive: the institutional capacity of a government to communicate, verify, and continuously update the information investors need to price risk accurately. Rwanda's score of 43.4 out of 50 on this axis, placing it among a small cohort of states including Ukraine and Vietnam that have adopted international transparency standards under very different macroeconomic conditions, is therefore not a diplomatic courtesy extended by a Washington-based industry body. It is a measurable input into the cost of capital itself, because investors and multilateral lenders increasingly treat the reliability of a government's disclosure regime as a proxy for the reliability of its debt management more broadly. This matters structurally because Rwanda, unlike resource-rich peers such as Nigeria or Angola, cannot rely on commodity windfalls to absorb the cost of opaque governance. Its access to concessional finance, at interest rates as low as zero to one percent according to Minister of Finance Yusuf Murangwa, is a direct function of earned confidence rather than natural endowment. The historical framing matters here. Landlocked states with limited natural resource bases have historically faced a structural financing penalty, a pattern visible from Bolivia to Chad to Malawi, in which the absence of hard collateral is compounded by weak institutional signalling, producing a doubly punitive cost of capital. Rwanda's trajectory, alongside Singapore's earlier transformation from entrepot vulnerability into financial credibility, and Mauritius's construction of a jurisdictional reputation for governance discipline, suggests an alternative model in which institutional transparency substitutes for resource endowment as the foundation of sovereign creditworthiness. The geopolitical context sharpens this further. As traditional Western development financing tightens and as China recalibrates its own overseas lending posture following the debt distress episodes of the 2020s, the pool of governments competing for a shrinking supply of affordable capital is widening, while the number of lenders willing to extend concessional terms without rigorous verification is narrowing. In this environment, Rwanda's ESG transparency score of 3.9 out of 4, placing it alongside Turkey, Indonesia, Egypt, and Uzbekistan, functions as a second layer of credibility that compounds the first. Understanding why this convergence of fiscal and ESG signalling matters now, at a moment when Rwanda's economy expanded by ten percent in the first quarter of 2026 and its 2026/27 budget of RWF 7.796 trillion leans on external loans for a quarter of its financing, requires situating Kigali's disclosure architecture within a broader reorganisation of how capital is allocated to small, ambitious states.

Rwanda's Labour Market Holds Steady on Paper, But Underemployment Signals a Deeper Structural Reckoning
Regions 20 July 2026

Rwanda's Labour Market Holds Steady on Paper, But Underemployment Signals a Deeper Structural Reckoning

Rwanda's labour market data for the second quarter of 2026 arrives at a moment when the country's macroeconomic narrative has been defined largely by resilience: sustained GDP growth, a disciplined fiscal consolidation path under the IMF's Extended Credit Facility, and a diversification agenda that has pushed mining, services, and manufacturing further into the export mix. Against that backdrop, an unemployment rate of 13.4 percent, statistically unchanged from a year earlier, could be read as confirmation that the labour market has found a stable footing. That reading, however, misidentifies where the actual signal lies. The National Institute of Statistics of Rwanda's latest release shows a labour underutilisation rate climbing to 59.7 percent, a measure that captures not just the unemployed but the underemployed, the discouraged, and the involuntarily part-time. This is the indicator that matters more, because it describes the difference between an economy that creates employment and one that creates income security. Rwanda, on current evidence, is doing more of the former than the latter. The distinction is not semantic. It is the difference between a labour market that absorbs a young, fast-growing population into productive, wage-earning activity and one that merely reclassifies underemployment as employment through the statistical architecture of own-use production and subsistence agriculture. This pattern is not unique to Rwanda. It echoes the early-stage labour transitions observed in Vietnam through the 1990s, in Ethiopia's agrarian-to-industrial pivot over the past decade, and in Kenya's persistently high youth informality despite headline employment gains. What separates Rwanda from these comparators is not the presence of underemployment, which is a near-universal feature of low-income structural transformation, but the institutional capacity Rwanda has built to potentially correct for it: a coordinated planning architecture under the Second National Strategy for Transformation, a Rwanda Development Board investment pipeline increasingly weighted toward higher-value sectors, and a fiscal framework disciplined enough to sustain targeted labour interventions without destabilising debt dynamics. Whether that institutional capacity translates into a labour market that pays better, not just employs more, is now the central question for policymakers, investors, and development financiers assessing Rwanda's trajectory toward its Vision 2050 upper-middle-income target. The data suggests the country has stabilised the denominator of its labour market equation while the numerator, the quality and remuneration of work itself, remains unresolved.

eKash and the Consolidation of Rwanda's Payment Infrastructure: How a National Interoperability Mandate Signals a Deeper Shift in East African Financial Architecture
Regions 16 July 2026

eKash and the Consolidation of Rwanda's Payment Infrastructure: How a National Interoperability Mandate Signals a Deeper Shift in East African Financial Architecture

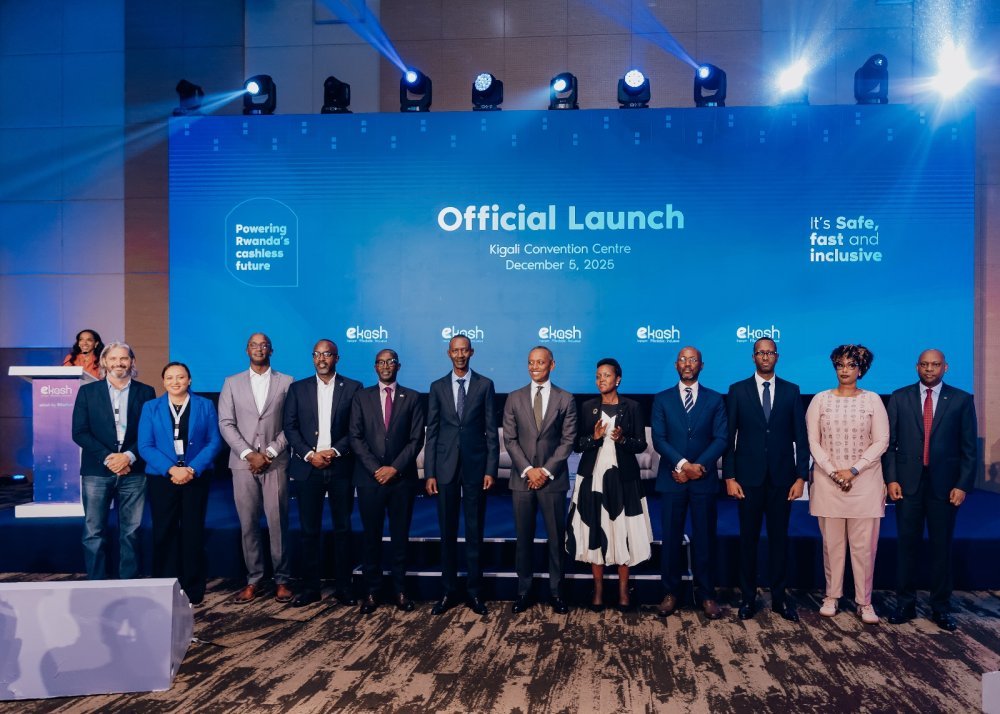
The history of monetary infrastructure in Africa has largely been a history of fragmentation. Banks built proprietary rails. Mobile money operators built parallel ones. Regulators, often years behind the pace of private sector innovation, spent the 2010s attempting to stitch together systems that were never designed to interoperate. Rwanda's designation of eKash as its national instant payment system on July 14, 2026 should be read against this backdrop, not as an isolated product launch but as the culmination of a longer institutional project to unify a financial system that had, until now, operated as a set of disconnected networks bound together by manual reconciliation and costly intermediation. The National Bank of Rwanda's directive that all domestic interoperable retail transactions migrate to eKash, executed operationally through RSwitch, the national payment switch, represents a rare instance of a central bank asserting direct architectural control over the rails through which its currency moves electronically. This is a structural departure from the market-led interoperability models that characterised earlier waves of African fintech development, in which private operators such as M-Pesa built dominant positions before regulators intervened to open access. Rwanda's approach inverts that sequence: the state designs the interoperable core first, then invites banks and mobile wallets to operate on top of it. The economic logic is straightforward but consequential. A transaction fee capped at RWF 20 regardless of transfer size, alongside a transaction ceiling of RWF 10 million, collapses the cost structure that has historically taxed digital transactions in Rwanda, transactions that in some cases carried fees of up to RWF 5,000. The geopolitical and comparative context matters as much as the domestic mechanics. Nigeria's NIP, Ghana's GhIPSS instant pay, South Africa's PayShap, Tanzania's TIPS and Egypt's InstaPay have each, in their own ways, attempted to solve the interoperability problem, with varying degrees of success and vastly different institutional architectures. Rwanda enters this field as a comparatively small economy attempting one of the continent's most aggressive pricing models, a decision that carries implications for bank revenue structures, mobile money economics, and the fiscal calculus of a National Bank willing to compress margins across an entire sector in pursuit of adoption. What is being tested in Kigali is whether a small, tightly governed state can use infrastructure policy as a substitute for the scale that larger economies rely on to drive down unit costs. The answer to that question will shape how investors, multilateral lenders, and regional peers interpret Rwanda's broader digital economy strategy over the coming decade.