
Kenyan Banks Control 65% of Rwanda’s Banking Assets, IMF Flags Regional Concentration Risks
Ready
A new IMF working paper says Kenyan banking groups also hold nearly half of the DRC market and almost a third of Uganda’s. Their expansion supports credit, trade and financial integration, but it creates stronger channels through which banking shocks could cross borders.
Kenyan banking groups account for nearly 65 per cent of banking-sector assets in Rwanda, 48 per cent in the Democratic Republic of Congo and 29 per cent in Uganda, demonstrating how Kenya’s financial system has become embedded across East Africa.
The figures appear in an International Monetary Fund working paper published on November 13 examining Kenya’s cross-border banking exposure and the economic spillovers associated with regional expansion.
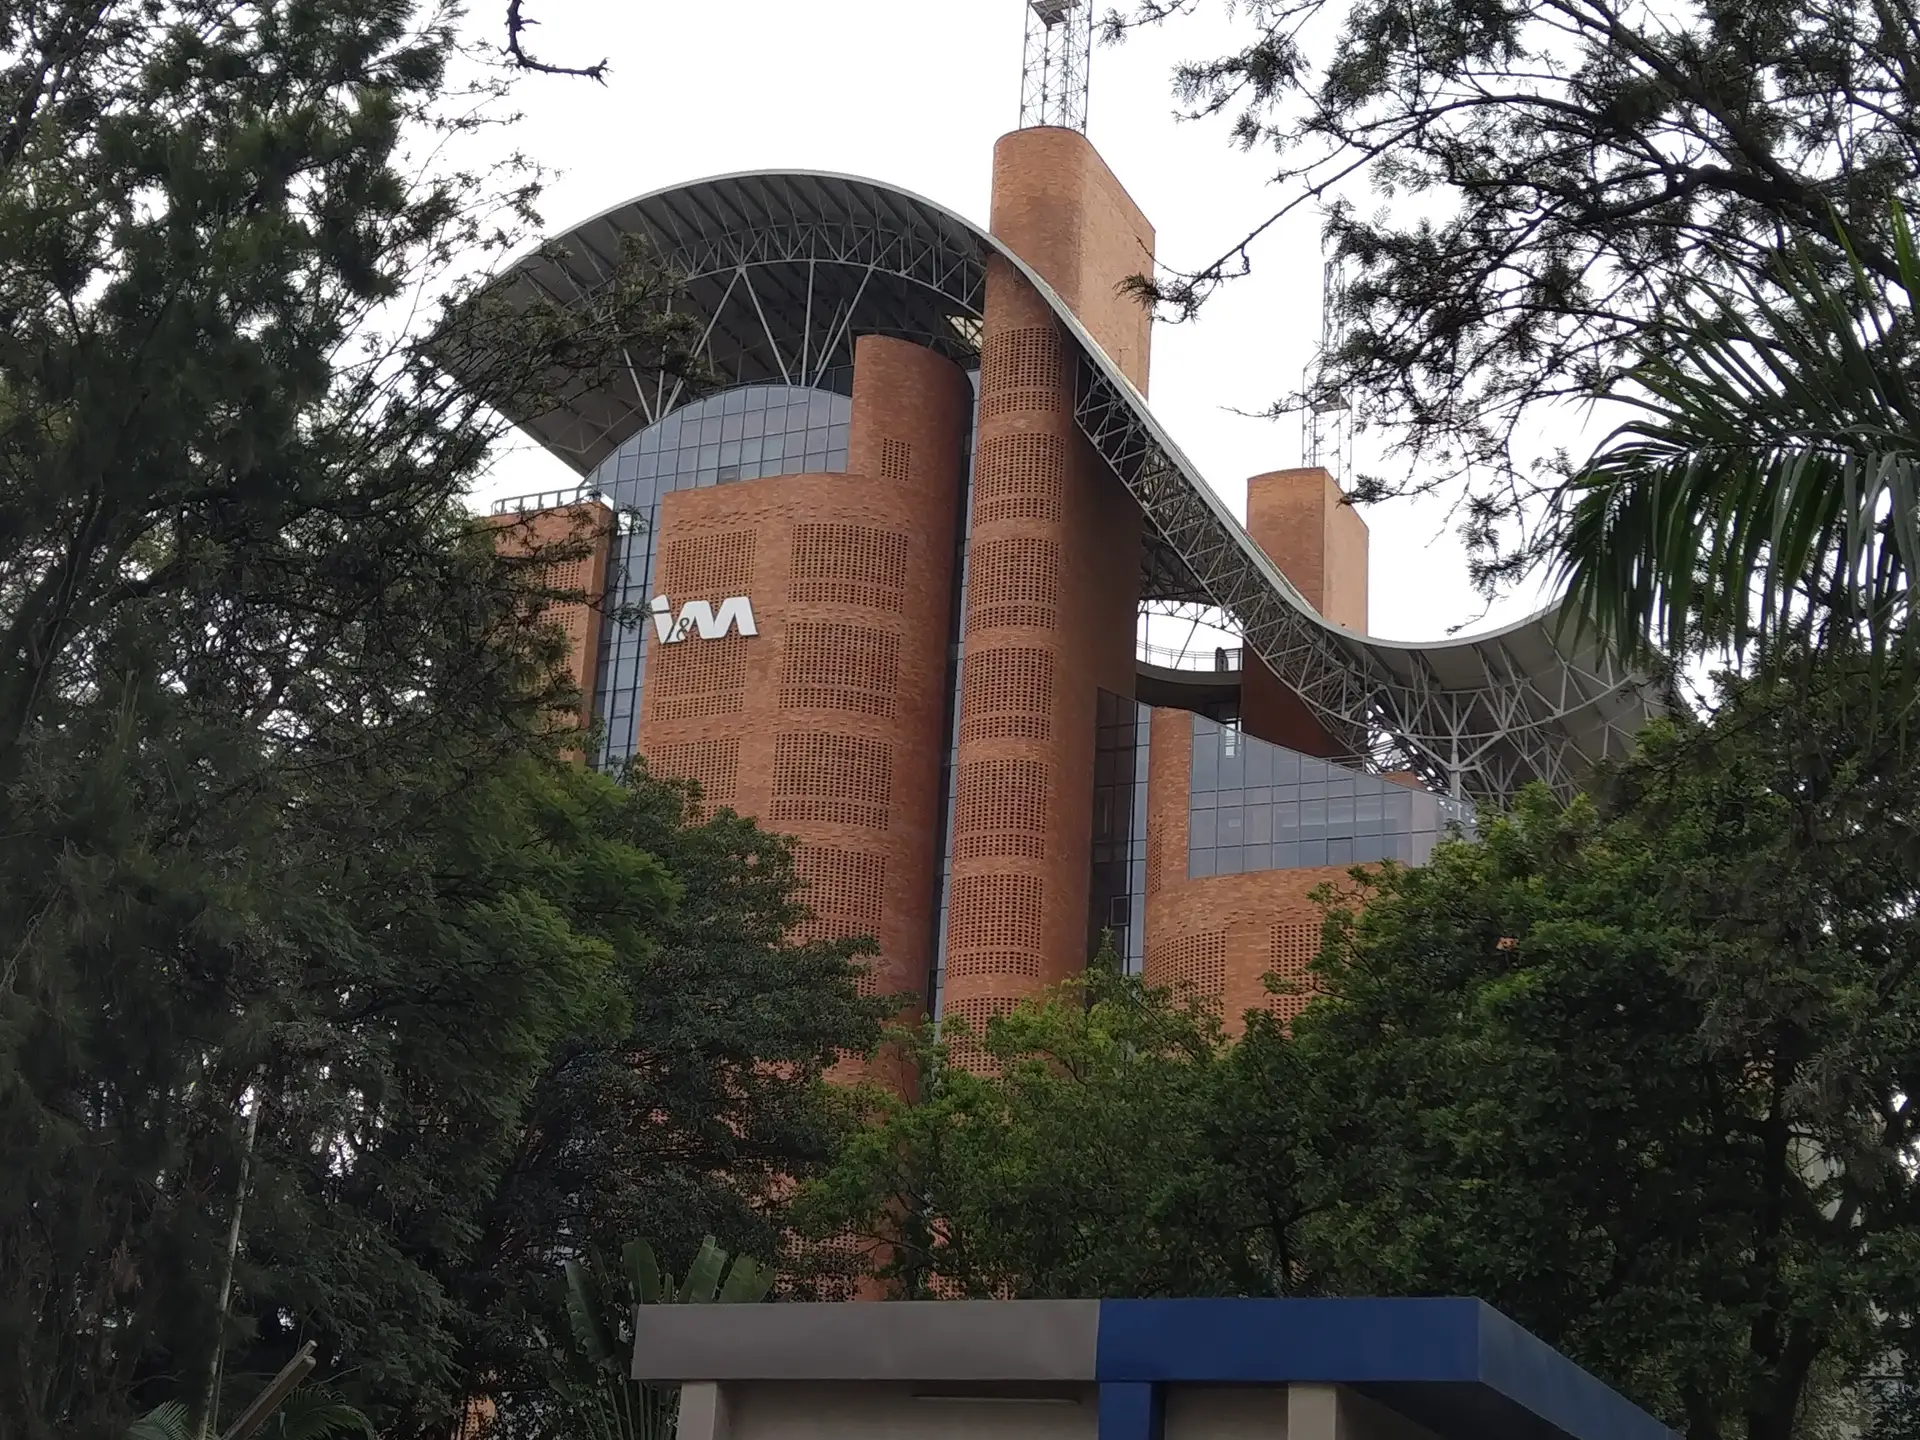
The research identifies KCB Group and Equity Group as the largest regional players. Co-operative Bank, NCBA, I&M, Diamond Trust Bank and Guaranty Trust Bank Kenya also maintain operations outside the country.
The findings confirm Kenya’s position as East Africa’s principal banking centre. They also show that banking integration has advanced faster than some of the regional systems required to supervise large cross-border groups or manage a failure affecting several countries simultaneously.
The DRC has become the largest regional market
The DRC accounted for approximately 43 per cent of Kenyan banks’ assets in other East African Community markets in 2024, up from about 10 per cent in 2018.
Rwanda, Tanzania and Uganda each accounted for approximately 15 per cent of the regional assets held by Kenyan banking groups. The DRC’s growing share reflects the expansion of KCB and Equity into a large but still underbanked market following its admission to the EAC.
Kenyan banks’ regional operations are supported mainly by customer deposits collected in host countries. This reduces their direct dependence on money transferred from Kenya and means subsidiaries largely finance lending from local deposit bases.
The structure can strengthen resilience because a temporary funding shortage at the Kenyan parent does not automatically remove all liquidity from its subsidiaries. However, it does not eliminate group-level risks involving capital, governance, technology, reputation and strategic lending decisions.
Kenya is also exposed in the opposite direction. Foreign-controlled banks account for approximately 30 per cent of assets in its domestic banking system, while international banks held about US$6.5 billion in cross-border claims on Kenya in 2024. Banks based in the United Kingdom, the United States, France, India and Italy were among the largest external sources.
Kenya therefore sits between international capital and regional banking markets. A global funding shock can affect Kenya, while financial or economic stress originating in Kenya can potentially be transmitted to subsidiaries and customers across neighbouring economies.
Trade expansion is helping drive banking expansion
The IMF paper finds that Kenyan banks expanded most strongly into countries where Kenyan exports were growing and where host banking systems were relatively profitable and recorded better asset quality.
A one-percentage-point increase in Kenya’s export growth to a destination market was associated with a 0.2-percentage-point increase in the growth of Kenyan banks’ assets in that country.
The relationship reflects the close connection between trade and finance. Banks often follow existing customers into new markets, providing trade finance, foreign-exchange services, payments, working-capital loans and cash-management products.
Regional banking networks can reduce the cost of operating across several countries because businesses do not need to establish entirely new financial relationships in each market. A Tanzanian importer buying from Kenya, for example, can benefit from a bank with operating systems and correspondent relationships on both sides of the transaction.
The expansion is also supported by digital banking platforms that allow corporate customers to manage accounts, payments and collections across national borders.
Credit growth brings benefits and inflationary pressure
The researchers found that stronger lending by Kenyan banks was associated with higher economic growth and higher inflation in host markets during the same year. The effects did not remain statistically significant in subsequent years.
Across a sample of 32 African economies, a one-percentage-point increase in total private-sector bank credit was associated with a 1.1-percentage-point increase in real economic growth and a 0.2-percentage-point increase in inflation.
The authors caution that these are conditional statistical associations. They do not prove that lending alone caused the increases in growth or prices. Faster-growing economies may attract banks and generate demand for credit at the same time.
Nevertheless, the findings illustrate the two-sided economic effect of financial expansion. Additional credit can finance stock, equipment, construction, transport and consumer spending. If lending expands more quickly than the supply of goods and services, it can also add to price pressure and asset-market risks.
For businesses, the regional expansion of Kenyan banks can widen access to trade finance and larger corporate loans. It may also increase competition among lenders. Smaller businesses will benefit only if regional scale translates into more accessible credit rather than being concentrated among large corporate customers.
Tanzania is a major operational market
The Central Bank of Kenya’s 2024 banking-supervision report recorded 77 branches belonging to Kenyan banking groups in Tanzania.
Diamond Trust Bank had the largest branch network among the Kenyan-controlled institutions, with 29 branches. KCB had 17, Equity 15, while NCBA and I&M each had eight.
Across the wider region, Kenyan banks had 586 branches at the end of 2024, including 188 in the DRC, 149 in Rwanda and 127 in Uganda. The regional total had declined from 654 in 2023 as some groups consolidated physical outlets and increased their use of digital channels.
For Tanzania, the presence of these banks connects local borrowers and traders to regional financing networks. It also means Tanzanian supervisors must assess risks at both subsidiary and group level, particularly where strategic, technology or treasury functions are managed from Kenya.
A cyber incident, liquidity problem or capital shock at a regional parent could affect services in several markets even where each subsidiary is legally separate.
Non-performing loans create pockets of risk
The IMF paper notes that non-performing-loan ratios at KCB and Equity exceeded banking-sector averages in Kenya, Rwanda and Uganda during parts of the period examined.
This does not mean the groups are insolvent or that their entire regional operations are deteriorating. It does indicate that rapid expansion and large market shares must be accompanied by strong credit assessment, provisioning and loan-recovery systems.
Asset-quality problems can become more difficult to manage when groups operate under different insolvency laws, accounting rules and supervisory requirements. A loan classified one way in one country may receive different treatment elsewhere, making group-wide comparisons more difficult.
Investors should therefore look beyond headline profit and asset growth. The quality of loans, provisioning coverage, capital held in each subsidiary, foreign-currency exposure and the ability to move capital within a group are equally important.
Regional supervision has not kept pace
The Central Bank of Kenya has signed cooperation agreements with regulators in several African markets, but the IMF researchers found that joint inspections remained infrequent.
Most relationships between Kenyan banking groups and individual host countries recorded no joint supervisory inspection during the preceding decade. Accounting standards, minimum-capital requirements and deposit-protection arrangements also vary across the region.
Burundi, the DRC and South Sudan were identified as lacking fully operational deposit-insurance arrangements. That could complicate depositor protection, emergency liquidity provision and the allocation of losses if a large cross-border institution failed.
A regional bank may operate under a single brand, but depositors are generally protected under national rather than EAC-wide arrangements. A customer in Rwanda, Tanzania or the DRC may therefore have different protection from someone using the same banking group in Kenya.
The policy priority is not to reverse cross-border expansion. It is to ensure that supervision, information sharing and crisis-management arrangements catch up with it.
What regulators and investors should watch
East African regulators will need more frequent joint inspections, compatible reporting standards and clearer rules for resolving cross-border banks. Authorities also need plans covering emergency liquidity, capital support, deposit repayment and the treatment of critical digital-payment systems during a crisis.
For banks, greater regional integration provides diversification and access to growing markets. It also increases exposure to different currencies, political risks, sovereign borrowers and regulatory systems.
For businesses, the benefits will be measured through faster payments, competitive trade finance and improved access to working capital. For households, the critical issues are deposit safety, service continuity and responsible lending.
The IMF publication is a working paper representing research by its authors rather than a formal policy decision of the IMF Executive Board. Its figures nevertheless deliver a clear message: Kenya’s regional banks are now large enough that their financial health is an East African economic issue, not only a Kenyan one.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
