
Tanzania’s Banks Earn TZS 2.11 Trillion in Nine Months as CRDB and NMB Capture 62% of Profits
Ready
Tanzania's banking sector recorded TZS 2.11 trillion in profit after tax during the first nine months of 2026, an increase of 17.1% from the corresponding period in 2025, according to an AML Finance assessment of 43 financial institutions. CRDB Bank and NMB Bank generated a combined TZS 1.31 trillion, representing 61.9% of sector profits despite holding 47.8% of total assets. Industry assets reached TZS 97.73 trillion, loans and advances stood at TZS 59.27 trillion, and customer deposits increased as private sector credit expanded by 34.2%. The results demonstrate the banking industry's growing financial capacity while raising questions about market concentration, lending rates above 15%, competition and the distribution of credit across Tanzania's economy.
Profits across 43 Tanzanian banking and financial institutions increased 17.1% to TZS 2.11 trillion in the nine months ending September 2026, supported by rising lending, deposits and financial assets. CRDB and NMB generated TZS 1.31 trillion between them, accounting for 61.9% of the industry's earnings despite holding 47.8% of its assets. The concentration raises questions about competition and the distribution of banking profits as private sector credit grows 34.2% and average lending rates remain above 15%.
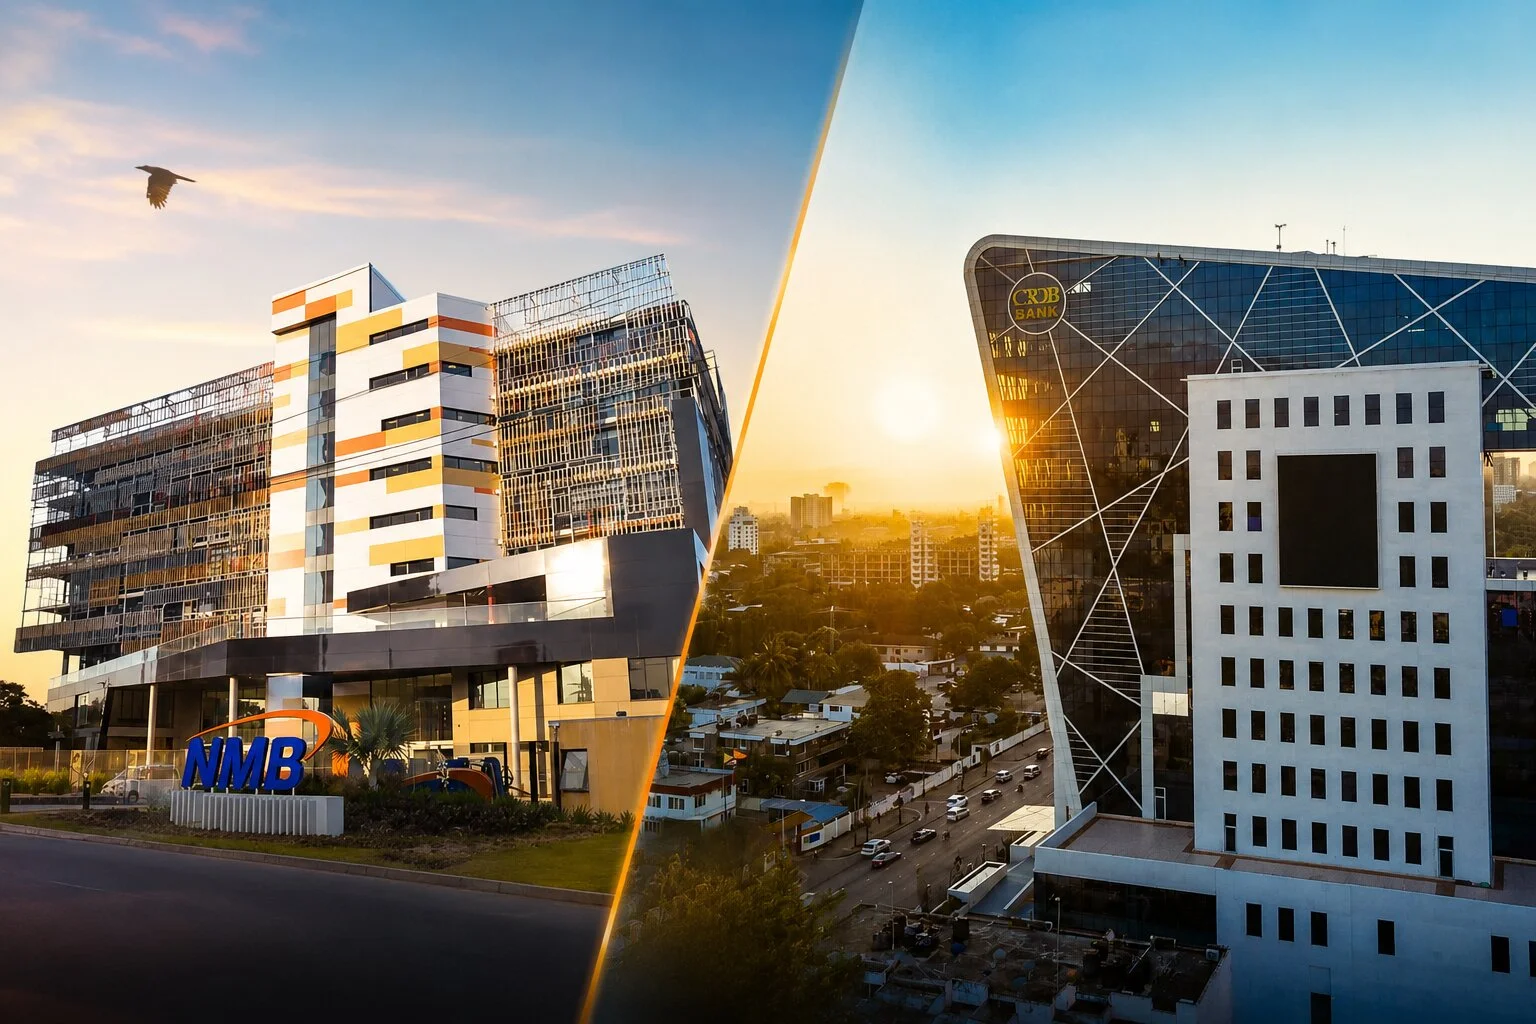
Tanzania's banking industry generated a combined TZS 2.11 trillion in profit after tax during the first nine months of 2026, an increase of 17.1% from approximately TZS 1.80 trillion recorded during the corresponding period of 2025, as commercial banks expanded lending and deposits while strengthening their position in the country's financial system. The growth was heavily concentrated among the two largest lenders, CRDB Bank and NMB Bank, which earned a combined TZS 1.31 trillion, equivalent to 61.9% of total industry profits, according to a November 2026 assessment of 43 banks and financial institutions.
The analysis, prepared by AML Finance Limited Managing Director Reginald Massawe and published by TanzaniaInvest on November 10, shows that the institutions collectively held TZS 97.73 trillion in assets at the end of September, including TZS 59.27 trillion in loans and advances and TZS 65.12 trillion in customer deposits. The figures were compiled from publicly available unaudited financial statements covering the nine months ending September 30, providing a broad assessment of the banking industry's performance rather than a separate audited sector-wide financial statement issued by the Bank of Tanzania.
The results demonstrate the growing financial capacity of Tanzania's banking institutions but also reveal considerable differences in profitability, asset quality and operating performance. Sixteen institutions with assets exceeding TZS 1 trillion controlled 92.8% of industry assets and generated 96.3% of profits, leaving the remaining 27 institutions sharing a relatively small proportion of earnings. Eight smaller institutions reported combined losses of TZS 10.16 billion, while several medium-sized lenders achieved strong profit growth despite operating with substantially smaller balance sheets.
NINE MONTH PROFIT
TZS 2.11T
17.1% annually
TOTAL ASSETS
TZS 97.73T
43 institutions
LOANS & ADVANCES
TZS 59.27T
CUSTOMER DEPOSITS
TZS 65.12T
Source: AML Finance, analysis of unaudited financial statements for January to September 2026.
The financial expansion comes as Tanzania pursues higher economic growth and increased investment in agriculture, manufacturing, mining, transport and infrastructure under its National Development Vision 2050. Commercial banks are central to those ambitions because their ability to mobilise domestic deposits and extend credit influences how businesses finance machinery, inventories, agricultural production and expansion. However, rising bank profitability does not necessarily mean borrowing is becoming more affordable, particularly when lending rates remain elevated and institutions differ substantially in the cost and availability of credit.
The Bank of Tanzania's October 2026 Monthly Economic Review reported that private sector credit expanded by 34.2% annually in September, while the overall lending rate increased to 15.54%, compared with 15.05% in August. The average deposit rate also rose to 9.02% from 8.78%, indicating higher returns for depositors alongside increased borrowing costs. These developments suggest that banks are expanding the quantity of credit available even as financing remains relatively expensive for many households and enterprises.
CRDB and NMB Account for Nearly Two-Thirds of Industry Profits
CRDB Bank maintained its position as Tanzania's largest banking group by assets and reported a profit after tax of TZS 672.07 billion during the first nine months of 2026, representing growth of approximately 29% from the corresponding period of 2025. Its total assets reached TZS 27.45 trillion, supported by expansion in lending, deposits and other financial activities. NMB Bank followed with a profit of TZS 634.60 billion, an increase of 17%, while its total assets reached TZS 19.31 trillion.
Together, the two banks held TZS 46.76 trillion in assets, representing approximately 47.8% of the combined assets covered by the AML Finance assessment. Their 61.9% share of industry profits was therefore considerably higher than their share of assets, indicating that they generated a disproportionately large share of banking earnings relative to their balance sheet size.
Tanzania's leading banks by profit, January to September 2026
| Bank | Profit after tax | Annual growth |
| CRDB Bank | TZS 672.07B | +29% |
| NMB Bank | TZS 634.60B | +17% |
| NBC | TZS 119.49B | +7% |
| Stanbic Bank | TZS 103.22B | −1% |
| People's Bank of Zanzibar | TZS 67.01B | +20% |
| Exim Bank | TZS 64.40B | +7% |
| KCB Bank Tanzania | TZS 55.80B | +17% |
| Azania Bank | TZS 54.90B | +23% |
| Diamond Trust Bank | TZS 50.80B | +38% |
| Equity Bank Tanzania | TZS 47.60B | +59% |
Source: AML Finance, as reported by TanzaniaInvest, November 10, 2026. Results cover the first nine months of 2026 and are unaudited. Ranking is by profit, rather than assets.
CRDB's stronger profit growth was accompanied by substantial expansion in its lending portfolio. The bank reported net loans of approximately TZS 18.44 trillion, an increase of 43.7% from the previous year, while customer deposits grew 26.5% to TZS 17.79 trillion. NMB's loans expanded by approximately 27% to TZS 12.07 trillion, bringing the combined loan portfolios of the two institutions to approximately TZS 30.51 trillion.
The expansion reflects growing demand for credit from businesses and households, but also the advantages enjoyed by banks with established deposit bases, extensive customer networks and the capacity to invest in technology. Large institutions can spread certain fixed costs, including payment infrastructure, regulatory compliance and software development, across millions of customers and substantial transaction volumes. They may also secure lower funding costs than smaller institutions because of stronger deposit mobilisation and greater access to institutional funding.
However, market concentration needs to be interpreted carefully. A high share of industry profits is not equivalent to the same share of lending or deposits, and it does not independently establish anticompetitive conduct. Profitability may reflect stronger asset quality, operating efficiency, greater lending volumes, differences in the services offered or more favourable funding structures. Establishing whether concentration is affecting competition would require evidence on interest rate margins, fees, market shares across specific services, customer switching and the barriers confronting competing institutions.
The AML Finance assessment found that CRDB and NMB accounted for approximately 79% of the industry's increase in profits compared with the corresponding period of 2025. Their combined share of assets has remained close to 48% since 2023, suggesting that the strengthening concentration of profits has been driven more by earnings performance than by a major increase in their share of the industry's assets.
That distinction presents a more precise picture of Tanzania's banking market. The two largest banks are generating an increasing proportion of total profits without necessarily absorbing an equivalent proportion of industry assets. Smaller and medium sized institutions therefore face the challenge of competing through credit pricing, customer service, specialised lending and operating efficiency rather than simply attempting to match the geographic reach of the largest lenders.
Lending Is Expanding Rapidly, but Borrowing Costs Remain High
The banking industry's profitability has increased alongside exceptionally strong credit growth. The Bank of Tanzania reported annual private sector credit expansion of 34.2% in September 2026, with particularly strong growth in transport and communication, trade and agriculture. Credit to transport and communication activities increased by 78.3%, while trade lending expanded by 52.5% and agricultural credit by 41.9%. Personal loans, a category that includes financing associated with micro, small and medium enterprises, accounted for approximately 33.9% of outstanding private sector credit, followed by trade at 15.6% and agriculture at 13.7%.
The figures suggest that Tanzanian banks are responding to rising demand for financing across productive activities, although the relationship between rapid lending growth and economic output requires closer examination. Private sector credit growth of 34.2% substantially exceeds Tanzania's reported real economic growth rate of approximately 6%, meaning the amount of credit outstanding is expanding considerably faster than measured production. This can be consistent with increased financial intermediation and investment, particularly in an economy where many businesses have historically lacked access to bank financing. However, sustained credit expansion also requires careful monitoring of borrower repayment capacity and the quality of newly issued loans.
According to The Citizen on November 3, the country's 16 largest banks increased their combined loans, advances and overdrafts by TZS 4.14 trillion in the third quarter alone, reaching TZS 55.12 trillion at the end of September from TZS 50.98 trillion in June. The 8.12% quarterly expansion was accompanied by stronger earnings, with these institutions generating more than TZS 2.02 trillion in profit during the first nine months. The difference between that figure and the AML Finance total of TZS 2.11 trillion reflects the coverage of 16 institutions in the former calculation against 43 institutions in the latter.
Lending prices nevertheless remain a concern for borrowers. The average lending rate of 15.54% in September was more than six percentage points above the average deposit rate of 9.02%, although the difference between these published rates should not be interpreted directly as the banking industry's realised profit margin. Banks incur additional costs associated with maintaining branches, payment systems, liquidity, capital, regulatory compliance and provisions against loans that may not be repaid. They also finance different products using liabilities with varying interest rates and maturities.
For businesses, even moderate differences in borrowing costs can materially affect investment decisions. An enterprise financing TZS 500 million in machinery or working capital at an annual interest rate of 15.54% would face approximately TZS 77.7 million in annual interest charges if the entire principal remained outstanding for a year, before fees and other financing costs. At 12%, the comparable interest charge would be TZS 60 million, a difference of TZS 17.7 million. Actual interest expenses on amortising loans would vary according to repayment schedules, but the illustration demonstrates why credit pricing influences which investments businesses can undertake profitably.
The availability of credit at different interest rates also has distributional consequences. Large and established companies may possess sufficient collateral, transaction histories and financial records to negotiate more favourable terms, while smaller enterprises often face higher interest rates or stricter lending requirements. The Bank of Tanzania reported that the negotiated lending rate offered to prime borrowers reached 12.03% in September, substantially below the overall average. The difference suggests that borrowers do not experience lending conditions uniformly across the economy.
Bank profitability could contribute to improved financing conditions over time if stronger earnings allow institutions to expand capital, invest in more efficient systems and compete more aggressively for customers. However, those benefits are not automatic. Greater profits can also be distributed to shareholders or retained to support further asset growth without necessarily reducing lending charges. The extent to which customers benefit depends on competition, bank strategies, funding conditions and regulatory oversight.
The concern has entered public debate. In its November 13 analysis, The Citizen examined whether the rising profits of Tanzania's major banks were being accompanied by lower borrowing costs, reduced fees and improved returns for depositors. The publication found that profits among leading institutions had increased substantially since 2023, although its comparison covered different numbers of banks across the years. The analysis reflects an emerging concern about how financial sector growth translates into benefits for customers, rather than establishing that high profits are evidence of unfair pricing.
Smaller Banks Face an Increasingly Uneven Competitive Market
The latest results reveal considerable variation among Tanzania's smaller and medium sized financial institutions. While CRDB and NMB dominate aggregate earnings, several smaller lenders recorded strong profit growth. Access Bank increased profits by approximately 110%, Ecobank Tanzania by 107%, Equity Bank Tanzania by 59% and Mwanga Hakika Bank by 48%, according to the AML Finance review. These results indicate that smaller institutions can expand profitability despite competing with banks that possess substantially larger asset bases.
However, the industry's overall distribution of profits remains highly uneven. The 16 institutions with assets exceeding TZS 1 trillion accounted for 96.3% of earnings, leaving a limited share to the remaining institutions. Eight smaller financial institutions reported combined losses of TZS 10.16 billion, including Co-operative Bank Tanzania, Selcom Microfinance Bank, United Bank for Africa Tanzania, Akiba Commercial Bank, DCB Commercial Bank, Guaranty Trust Bank Tanzania, Uchumi Commercial Bank and FINCA Microfinance Bank.
The reasons for weak profitability differ between banks. Some institutions may be undertaking investment programmes that increase operating costs before producing sufficient revenue, while others may face expensive deposit funding, low lending volumes, credit losses or limited customer activity. Small balance sheets can also increase the relative cost of maintaining banking infrastructure and complying with regulatory requirements. The figures alone do not establish which factor explains the performance of each institution.
The market also contains examples of institutions expanding rapidly through balance sheet growth. Azania Bank increased its assets from TZS 3.68 trillion in December 2025 to TZS 7.31 trillion by September 2026, becoming Tanzania's third largest institution by assets under the AML Finance assessment. Its reported profit of TZS 54.9 billion was nevertheless considerably smaller than that of NBC, which held approximately TZS 6.71 trillion in assets and earned TZS 119.49 billion. The comparison illustrates that balance sheet size does not automatically produce proportionate profits, particularly where institutions differ in funding costs, lending portfolios and the composition of their assets.
Potential consolidation could further alter competition. Absa Group has been pursuing a proposed combination of its Tanzanian banking interests involving NBC and Absa Bank Tanzania. Based on their September asset values, the two institutions would have approximately TZS 8.77 trillion in combined assets before consolidation adjustments, placing the proposed entity ahead of Azania Bank in the current ranking but still substantially below CRDB and NMB. The Bank of Tanzania has reportedly indicated that it has no objection to the proposal, although its ultimate implementation and competitive consequences depend on the completion of the relevant corporate and regulatory processes.
A larger third institution could create additional competitive pressure in corporate lending, deposits and other banking services. At the same time, consolidation would reduce the number of independently operating banks, demonstrating why merger assessments must consider both the capacity of the resulting institution and the potential implications for market concentration.
Asset Quality and Operating Costs Will Determine Whether Profit Growth Is Sustainable
The expansion of lending and profitability must also be considered alongside banks' operating costs and the quality of their credit portfolios. The AML Finance analysis reports a sectorwide nonperforming loan ratio of 5.8%, although individual institutions show substantial variation. CRDB recorded a ratio of approximately 2.3% and NMB 2.5%, while TIB Development Bank, China Dasheng Bank and Uchumi Commercial Bank reported considerably higher ratios.
Nonperforming loan ratios are useful indicators of credit quality, but they can temporarily improve during periods of rapid lending growth because new loans increase the outstanding portfolio before repayment difficulties emerge. A reduction in the ratio therefore does not necessarily demonstrate that all underlying credit risks have declined. Banks and regulators must also examine the value of troubled loans, loan restructuring, write offs and the provisions established to absorb potential losses.
The industry's income structure presents another consideration. Across the 43 institutions, interest income reached TZS 6.30 trillion during the first nine months of 2026, compared with TZS 2.23 trillion in income from fees, foreign exchange activity and other sources. Noninterest income accounted for approximately 26.1% of total income, down from 28% in the corresponding period of 2024, indicating that interest earning activities have become relatively more important even as banks expand digital transactions and other financial services.
This distinction challenges assumptions that growth in digital banking necessarily produces an increasing proportion of revenue from transaction fees. Digital channels may reduce the cost of delivering services, attract deposits and support lending without proportionately increasing noninterest income. Their economic contribution should therefore be assessed through transaction costs, service reliability, customer adoption and the profitability of the businesses they support.
Massawe, the AML Finance Managing Director who prepared the assessment, argued that banks need to examine the profitability of additional lending rather than assume that expanding assets will automatically improve financial performance. He emphasised the relationship between the revenue earned from new business and the associated costs of funding, servicing and potential loan losses. This assessment is relevant because rapid credit growth can initially generate additional expenses before the full revenue from new lending is realised.
The broader financial results also present a question for Tanzania's development priorities. A banking industry earning more than TZS 2 trillion over nine months possesses considerable capacity to generate capital and support further financial expansion. However, its contribution to the economy will depend on where credit is allocated, whether borrowers can obtain financing at sustainable costs and whether institutions maintain sufficient financial strength to withstand unexpected economic shocks.
For a country targeting a $1 trillion economy by 2050, banking sector performance must eventually be reflected in the availability of capital for productive businesses, infrastructure, agriculture and industrial development. The September figures show that lending is growing rapidly and that the largest institutions are generating substantial profits. They also reveal that profitability is concentrated among a small number of banks, average borrowing costs remain elevated and smaller institutions face markedly different financial conditions.
The next measure of the industry's development will be whether rising earnings and expanding balance sheets can support broader access to competitively priced credit without compromising financial stability. That outcome will depend on effective competition, prudent lending and the ability of Tanzania's banks to finance investment that increases production and household incomes.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
