Uganda Raised Rates by 225 Basis Points. The Shilling Kept Falling
Ready
Uganda’s largest interest rate increase in years briefly strengthened the shilling, but persistent demand for dollars, higher oil costs and weaker export receipts quickly reversed the gains. The Bank of Uganda was selling foreign currency within days, exposing the limits of monetary tightening when the pressure is coming from the external account.
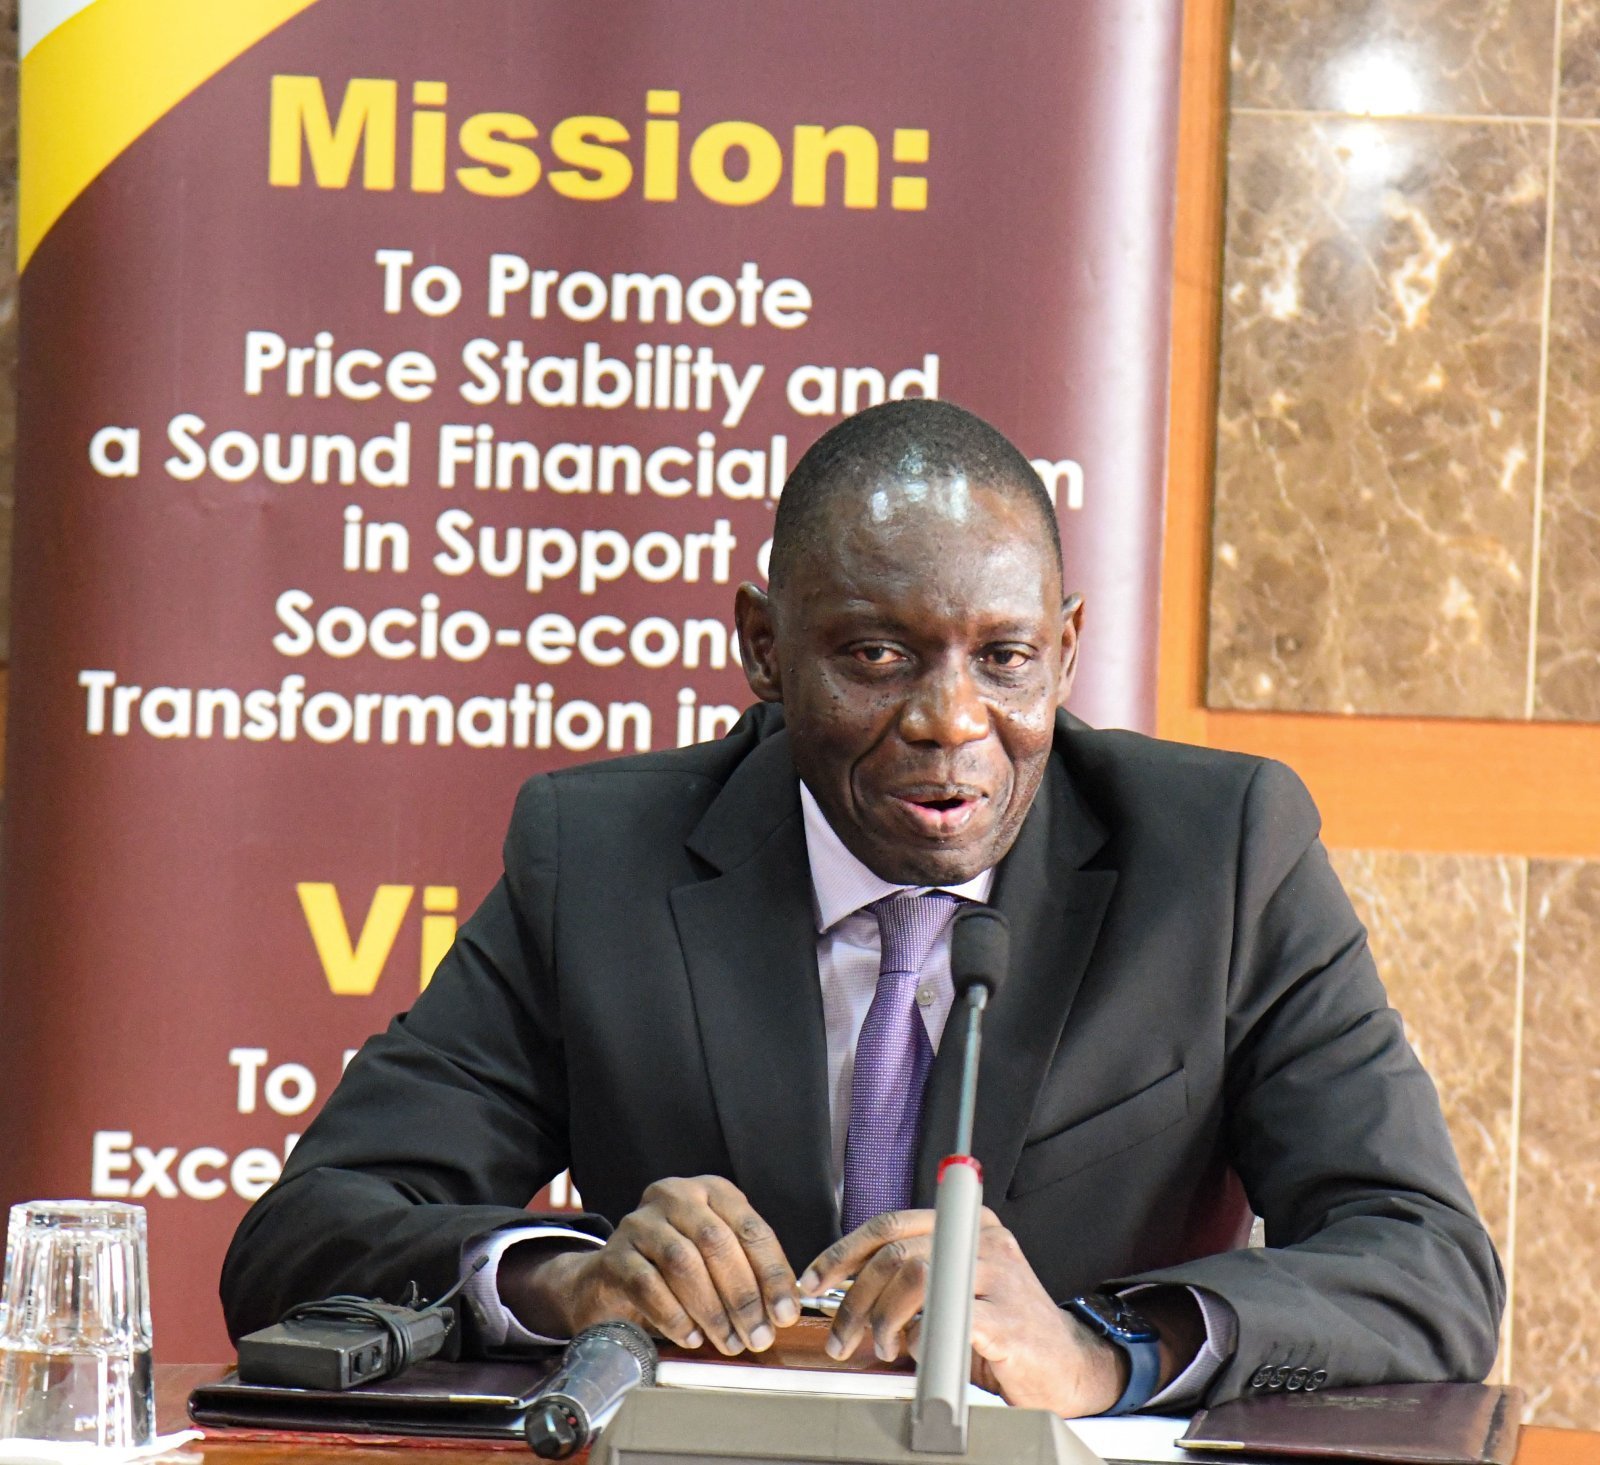
Uganda entered October with one of the more uncomfortable combinations available to a central bank: a rapidly weakening currency, rising imported inflation, an expanding external deficit and an economy that was still expected to grow strongly enough to make aggressive tightening costly. On 14 October, the Bank of Uganda responded by raising its Central Bank Rate by 225 basis points, from 9.75 percent to 12 percent, in an emergency monetary policy meeting, its first rate change since October 2024 and one of the sharpest adjustments in more than a decade.
The scale of the move reflected the speed at which Uganda’s external conditions had deteriorated. The shilling had already crossed USh4,000 to the dollar and had fallen to successive record lows, with strong foreign currency demand from energy companies, merchandise importers and telecom firms placing sustained pressure on the market. By 8 October, commercial banks were quoting the currency at about USh4,090 to USh4,100 per dollar, more than 11 percent weaker since the beginning of the year.
The initial reaction suggested that monetary policy might be enough to slow the decline. After the emergency rate hike, the shilling strengthened temporarily to around USh3,990 to USh4,000 per dollar, but the recovery did not last because the underlying demand for dollars remained intact while export receipts stayed weak and energy costs remained elevated.
By 22 October, barely a week after the rate increase, the shilling had weakened to around USh4,250 to USh4,260 per dollar, considerably below the level prevailing before the rate decision, forcing the Bank of Uganda to enter the foreign exchange market as a seller of dollars. The central bank did not disclose the size of the intervention, but the sequence was economically revealing because the largest monetary tightening move in years had failed to reverse the currency’s direction.
Uganda’s Problem Is Increasingly External
The pressure on the shilling is being driven by a combination of import demand, higher energy costs and weaker foreign currency earnings rather than by domestic inflation alone. Higher global oil prices have raised the cost of petroleum imports, while freight and insurance costs have increased alongside geopolitical tensions, widening the amount of foreign exchange Uganda needs simply to maintain existing import volumes.
At the same time, weaker export receipts have reduced the flow of dollars into the economy. Coffee and cocoa earnings have softened, while tourism receipts have not fully compensated for the increase in import requirements, creating a widening gap between the foreign currency Uganda earns and the foreign currency demanded by businesses and consumers.
This imbalance is visible in the balance of payments. The current account deficit has widened sharply, while the goods trade deficit has also deteriorated, leaving Uganda more dependent on capital inflows, investment related foreign exchange and central bank reserves to finance the difference between what the economy imports and what it earns externally.
That creates a difficult policy environment because a central bank can increase interest rates, withdraw liquidity and intervene in the foreign exchange market, but none of those measures directly reduces the number of barrels of petroleum the country needs to import or immediately increases export receipts. Monetary tightening can reduce domestic demand and discourage some imports, but the adjustment works through slower consumption, more expensive credit and weaker investment rather than through an immediate improvement in Uganda’s export capacity.
The 225 Basis Point Increase Was About More Than Inflation
Bank of Uganda had held the Central Bank Rate at 9.75 percent for much of 2026, even as external risks were becoming more visible. In May, the central bank was still projecting core inflation at between 5.0 and 5.3 percent over the following 12 months and economic growth of between 6.5 and 7 percent in FY2025/26, while warning that higher oil prices, geopolitical tensions and further shilling depreciation could push inflation higher.
By October, those risks had moved from forecast scenarios into actual economic pressure. The weakening currency was increasing the local currency cost of imported fuel, machinery, pharmaceuticals, industrial inputs and consumer goods, while higher energy prices were adding another layer of imported inflation.
The policy rate increase therefore served two purposes. The first was to restrain inflation by making borrowing more expensive and reducing domestic demand. The second was to defend the attractiveness of shilling denominated assets by increasing returns available to investors holding Ugandan financial instruments.
The second objective is especially relevant when a currency is under pressure because higher interest rates can encourage investors to retain local currency positions rather than moving into dollars, while also attracting some portfolio inflows. The problem is that such flows respond to more than interest rate differentials. Investors also consider currency expectations, political risk, external financing conditions and the likelihood of further depreciation, which can quickly erase the additional return offered by a higher policy rate.
Uganda Was Already Tightening Before The October Rate Shock
The October rate increase did not occur in isolation. Bank of Uganda had already been using reserve requirements to remove liquidity from the financial system, increasing the Cash Reserve Requirement earlier in 2026 from 9.5 percent to 11 percent as part of an effort to absorb excess banking sector liquidity and reduce exchange rate pass through into inflation.
Further tightening followed as currency pressure intensified, meaning that commercial banks faced both a higher benchmark interest rate and tighter liquidity conditions. This combination affects the economy through bank lending because commercial lenders have fewer funds available to extend as credit while their own funding environment becomes more expensive.
For businesses, the result is likely to appear through higher borrowing costs, tighter credit approval, more expensive overdrafts and slower expansion decisions. Companies already dealing with higher fuel, freight and imported input costs may therefore face another pressure from domestic financing at precisely the point when working capital requirements are increasing.
Households face a similar adjustment through higher loan rates and more expensive consumer credit, while borrowers with variable rate facilities may see debt servicing costs rise. The central bank is effectively accepting some reduction in domestic demand as the price of reducing pressure on inflation and the currency.
Uganda’s Reserves Are Rising While Its Currency Is Weakening
One of the more interesting contradictions in Uganda’s external position is that foreign exchange reserves have improved substantially while the shilling has weakened sharply.
Bank of Uganda reported that foreign exchange reserves increased by 56 percent in the year to June 2026, strengthening the country’s external buffer, while the central bank also announced plans to increase gold purchases as part of efforts to diversify reserve assets.
Earlier Bank of Uganda data already showed gross reserves rising from about $3.79 billion in April 2025 to more than $6 billion by March 2026, with import cover improving from around 2.6 months to about four months over the same period.
A larger reserve position would normally provide greater confidence in the currency, but reserves and daily foreign exchange liquidity are not the same thing. A country can have stronger gross reserves while its domestic foreign exchange market remains under pressure if importers, energy companies and other businesses are demanding dollars faster than exporters, investors and remittance channels are supplying them.
The Bank of Uganda’s decision to sell foreign currency directly into the market on 22 October illustrates this distinction. Reserves provide the central bank with the capacity to intervene, but using them repeatedly to defend the currency can eventually reduce the same buffer that had previously strengthened Uganda’s external position.
The policy challenge is therefore not simply whether Uganda has enough reserves, but how much of those reserves the central bank is willing to deploy before the underlying external imbalance adjusts.
Higher Oil Prices Are Reversing Part Of Uganda’s External Improvement
Uganda’s vulnerability to the current energy shock is particularly notable because the country is approaching its own transition into crude oil production.
Until domestic oil exports begin generating significant foreign currency earnings, however, Uganda remains a petroleum importing economy. Higher global crude prices therefore worsen the external account before the country begins receiving the export benefits associated with its own oil sector.
That creates an unusual transitional period in which oil related investment can strengthen foreign exchange inflows and reserves while imported petroleum simultaneously increases the current demand for dollars.
The contradiction will remain until Uganda begins exporting crude at sufficient scale to materially change the country’s balance of payments. Once production begins, the external sector could shift considerably because petroleum exports would introduce a large new source of dollar earnings, although the extent of the benefit will depend on production volumes, global prices, repatriation structures and the import intensity of the oil industry itself.
Until then, higher international oil prices remain negative for the shilling even though Uganda is preparing to become an oil producer.
The Cost Of Defending The Shilling Will Be Felt In Credit And Growth
Aggressive monetary tightening can stabilise a currency when depreciation is being driven partly by domestic liquidity and speculative demand, but the economic cost rises when the pressure originates from structural foreign exchange shortages.
The October rate increase therefore creates a trade off for Uganda. Higher interest rates can reduce inflation expectations, moderate demand for imports and make local financial assets more attractive, but they can also reduce private investment, raise business financing costs and slow household consumption.
Bank of Uganda has already reduced its growth outlook, reflecting the pressure created by higher energy prices, weaker consumption and tighter financial conditions. The adjustment is particularly relevant for an economy that had previously been expected to accelerate as investment around the oil industry increased.
The risk is that monetary policy suppresses sectors of the domestic economy that are not responsible for the foreign exchange shortage while only partially addressing the forces driving the shilling lower. A manufacturer borrowing in Uganda shillings may face a higher interest bill even though the currency pressure originates largely from imported petroleum, global freight costs and weaker export receipts.
This does not make the rate increase unnecessary, but it does explain why monetary policy alone is unlikely to resolve the problem.
The Shilling Is Now Testing Uganda’s First Oil Transition
Uganda is approaching first oil with stronger international reserves, substantial infrastructure investment and the prospect of a major new source of export earnings, but it is entering that period with a currency under severe pressure and a widening external imbalance.
The events following the October rate increase show how difficult that transition may be. A 225 basis point increase initially strengthened the shilling, but within days the currency resumed falling, eventually forcing the central bank to sell foreign exchange directly into the market.
Until oil exports begin generating substantial foreign currency earnings, Uganda remains exposed to the same forces affecting other petroleum importing African economies: expensive fuel, elevated freight costs, a strong dollar and periodic shortages of foreign exchange.
The country may therefore spend the period immediately before first oil tightening monetary conditions to contain pressures that its own oil exports could eventually help reduce. Whether that adjustment remains manageable will depend less on the headline size of the policy rate and more on how quickly export earnings, investment inflows and petroleum revenues begin closing the gap between Uganda’s demand for dollars and its capacity to earn them.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
