WMO Says Very Strong El Niño Will Persist Through February 2027 as Africa Faces Drought, Flood and Food Risks
Ready
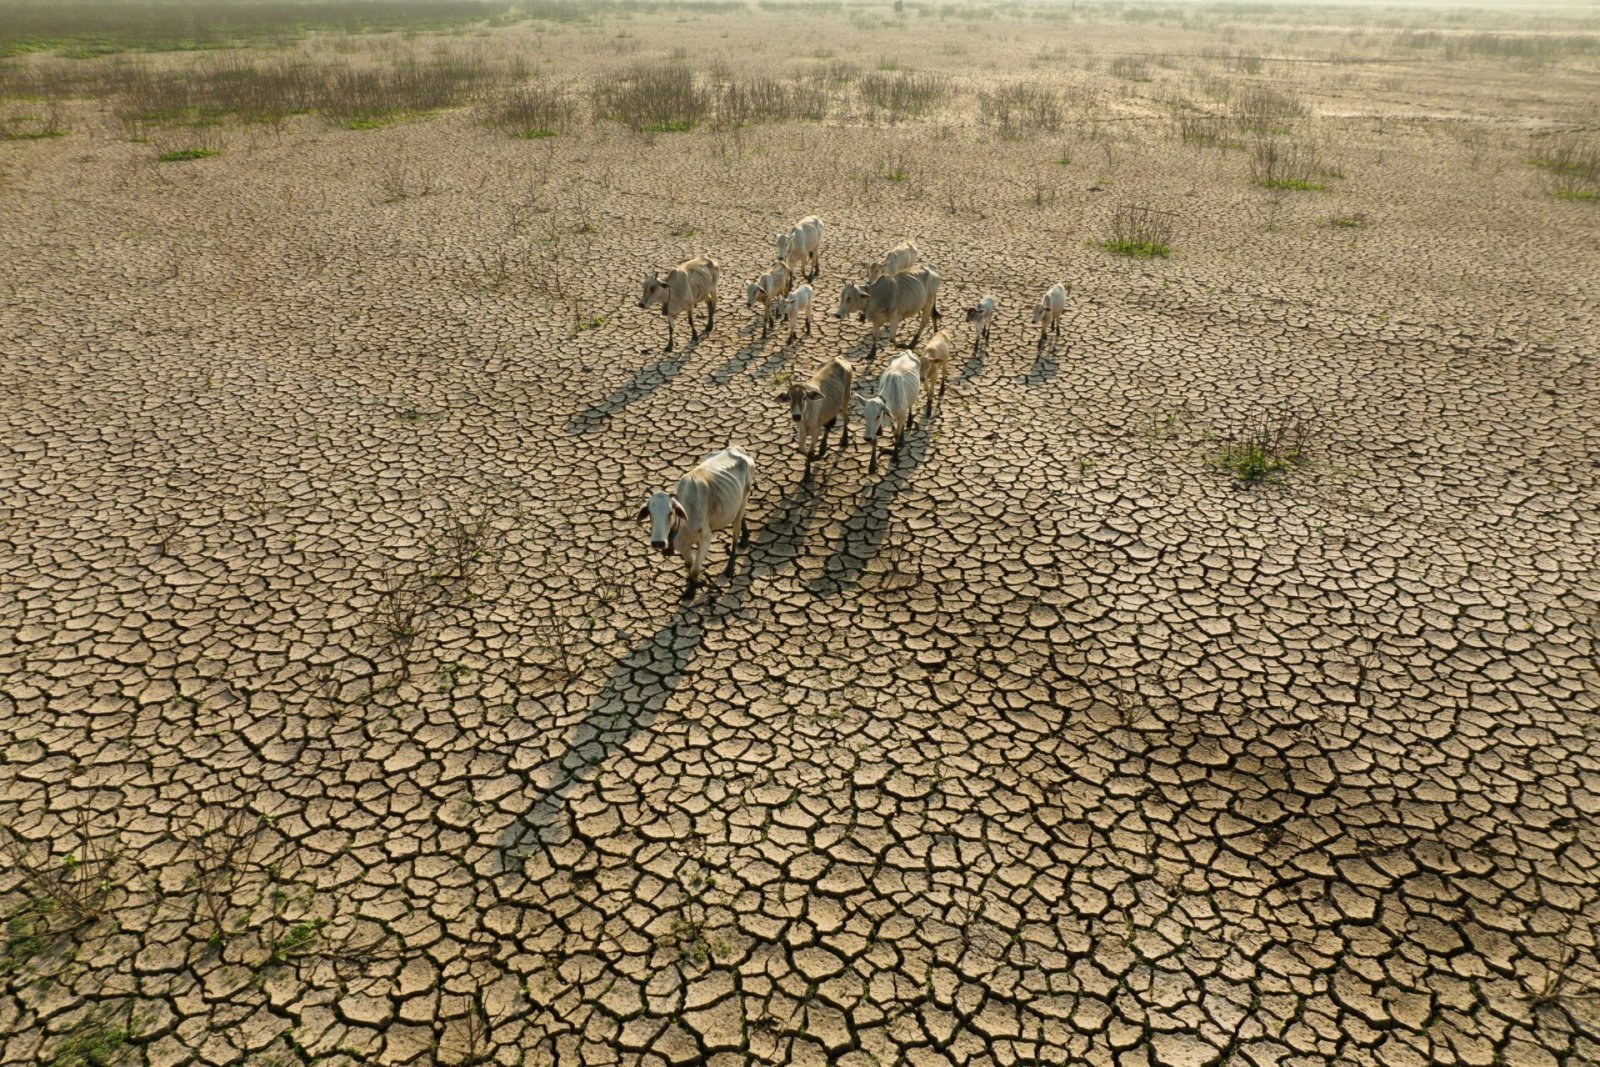
The World Meteorological Organization expects the very strong 2026 El Niño to persist through February 2027, exposing African economies to sharply different but connected risks. Southern Africa faces below normal rainfall that could reduce maize output and hydropower generation just two years after the 2024 drought, while Eastern Africa faces a volatile combination of rainfall deficits, heavy rain, flooding, livestock disease and infrastructure disruption. Previous El Niño shocks have reduced cereal production, raised food prices and weakened GDP through agriculture and electricity shortages, making the current event a macroeconomic risk for inflation, trade balances, public finances and household incomes.
Africa is entering the most economically sensitive phase of a strengthening El Niño that the World Meteorological Organization expects to persist through February 2027, exposing different parts of the continent to drought, flooding, extreme heat, agricultural losses, livestock disease, pressure on hydropower generation and renewed food price risks at a time when many governments have limited fiscal room to absorb another climate shock. WMO said in September that El Niño was firmly established and had an exceptionally high probability of persisting through the December 2026 to February 2027 period, while global seasonal models placed the Niño 3.4 sea surface temperature anomaly at approximately 3.6 degrees Celsius during September to November, a level associated with exceptionally strong El Niño conditions. Its October update indicated that central and eastern tropical Pacific temperatures were expected to remain extremely elevated through the final quarter of 2026 before the event peaks around December.
For African economies, the consequences cannot be reduced to a single continental story about drought or rain because El Niño alters atmospheric circulation differently across regions. Eastern Africa can move between rainfall deficits, intense storms and flooding within the same season, while Southern Africa can experience prolonged dry conditions that reduce maize production, livestock productivity and hydropower generation. The economic transmission therefore differs by geography. Drought reduces yields, lowers farm incomes, weakens livestock conditions, constrains electricity generation and increases demand for imported food, while excessive rainfall destroys crops, roads, bridges, homes and market infrastructure, raises the risk of livestock and human disease and interrupts transport corridors. In both cases the effect eventually reaches inflation, foreign exchange demand, government expenditure, household consumption and business confidence, which is why the current El Niño should be understood as a macroeconomic risk rather than only a humanitarian or meteorological event.
Eastern Africa Faces a More Volatile Economic Risk
The Greater Horn entered the second half of 2026 with agricultural and pastoral areas already weakened by rainfall deficits. FEWS NET reported in September that harvests across the bimodal areas of Kenya, Uganda, Rwanda and Burundi were generally average to below average, while below average crop production was expected in western Kenya, Karamoja in Uganda, Sudan, South Sudan and western Ethiopia. Pasture remained available in parts of eastern Kenya, Somalia and southeastern Ethiopia, but high temperatures were accelerating deterioration, while northeastern Ethiopia, Turkana in Kenya and Djibouti were already experiencing severe water and pasture shortages.
This starting position matters because a climate shock arriving after a weak season produces a larger economic effect than the same shock would produce after a strong harvest. Farmers may enter the next planting cycle with lower grain stocks and less money to buy seed, fertiliser or labour, pastoralists may already have reduced herd quality or spent more on water and feed, and governments may already be financing humanitarian support or additional food imports. The result is that household and public balance sheets are weaker before the most disruptive phase of El Niño has fully arrived, which reduces the capacity to absorb further losses and increases the probability that weather disruption becomes a wider economic problem.
The rainfall outlook for Eastern Africa has also become more complicated as the season has progressed. In August, the IGAD Climate Prediction and Applications Centre projected wetter than normal conditions across much of the Greater Horn during October to December, including a 90 percent probability of enhanced rainfall over southern Ethiopia, central and southern Somalia and northeastern Kenya. The same outlook indicated a high probability of more than 400 millimetres of seasonal rainfall in central and southern Somalia, parts of Kenya, the Lake Victoria basin, Burundi, western Rwanda and western Tanzania. The October to December season supplies as much as 70 percent of annual rainfall in parts of Ethiopia, Kenya and Somalia and around 40 percent in parts of Rwanda, Burundi, Tanzania and Uganda, so the performance of these three months can materially influence annual agricultural output. (icpac.net)
By October, however, ICPAC’s updated outlook pointed to drier than usual conditions across Kenya, southern Ethiopia, Somalia, Tanzania, Burundi, Rwanda and southern Uganda, while wetter conditions remained more likely in southern South Sudan and parts of Uganda. That change is economically significant because it shows that the risk is not simply one of too much rainfall but of greater seasonal instability. Farmers make planting decisions before the full weather pattern is known, commodity traders price future supply based on changing forecasts, insurers reassess risk while crops are already in the ground, and governments can find themselves preparing for both flood response and drought support in different parts of the same country or subregion.
Somalia shows how quickly this volatility can become an economic and humanitarian crisis when it overlaps with conflict and weak institutions. FAO warned in September that a strengthening El Niño could produce severe Deyr flooding, with parts of central and southern Somalia facing up to a 90 percent probability of above normal seasonal rainfall. IPC projections subsequently placed 5.4 million Somalis at Crisis level hunger or worse between October and December, while nearly 26,000 internally displaced people in Baidoa were projected to face Catastrophe conditions under the baseline scenario and potentially famine risk if severe flooding and displacement materialised.
The economic implications extend beyond food availability because floods can destroy roads, cut access to markets, damage storage facilities, disrupt livestock trade and raise the cost of humanitarian delivery. In countries where conflict has already fragmented markets and weakened public institutions, a weather event can therefore reduce agricultural production, interrupt trade and increase government or donor expenditure simultaneously. Amani Africa reported on October 30 that Somalia had 5.4 million people projected to face crisis levels of hunger or worse during October to December, while Sudan had 19.5 million people facing acute hunger amid conflict and humanitarian funding reductions. The same analysis, citing the African Development Bank, estimated that the anticipated super El Niño could impose between $10 billion and $20 billion in economic losses across African countries while adaptation financing needs approach $100 billion.
Eastern Africa also faces a livestock risk that can translate directly into household asset losses and reduced cross border trade. FAO and IGAD warned on October 30 that heavy rainfall and flooding were increasing the risk of Rift Valley fever outbreaks across Ethiopia, Kenya, Somalia, South Sudan, Tanzania and Uganda, with rising risk in Burundi and Rwanda. Tanzania currently has the largest area assessed as suitable for Rift Valley fever transmission. The disease affects sheep, goats, cattle, buffaloes and camels, which means outbreaks can reduce livestock productivity, destroy household wealth, interrupt meat and milk supply and trigger movement restrictions that affect trade.
Southern Africa Faces Another Production and Power Shock
Southern Africa enters the current El Niño from a different economic position because the subregion experienced a severe drought during the 2023 to 2024 event and then benefited from stronger agricultural output during 2026, which rebuilt grain availability and helped moderate food prices in several markets. FAO’s current Southern African climate outlook now favours below normal rainfall across much of the central and southern SADC region during the 2026 to 2027 agricultural season, accompanied by above normal temperatures, while its historical analysis indicates that parts of Namibia, Botswana, Angola, South Africa, Madagascar and Mozambique have faced more than a 50 percent probability of drought during strong El Niño episodes.
The timing of the current risk is economically important because Southern Africa has only recently rebuilt part of the buffer lost during the previous drought. Stronger 2026 harvests increased maize availability and helped moderate food prices in South Africa, Zambia and neighbouring markets, but by October El Niño related production concerns were already influencing grain prices. FAO reported that South African maize prices had risen for a third consecutive month as markets began to price in the possibility of weaker 2027 output.
This is how climate risk enters inflation before harvest losses have actually occurred. Traders adjust expectations, farmers alter planting decisions, millers reassess replacement costs and governments begin considering whether strategic reserves or import arrangements may be required. If the next maize harvest falls materially, the consequences will spread beyond individual producing countries because South Africa and Zambia are important regional suppliers and several neighbouring economies depend on cross border grain flows to stabilise domestic markets. The effect can therefore move quickly from weather conditions in producing regions to food inflation across multiple countries.
The 2024 drought provides a useful measure of the possible scale. FAO estimated that Southern African cereal output deteriorated sharply during that El Niño, while acute food insecurity in the subregion reached around 16 million people in the first quarter of 2024. Zambia’s cereal output eventually fell to about 1.9 million tonnes, nearly 49 percent below the five year average, while maize production dropped 51 percent from the previous year. The country lost both domestic food availability and part of its capacity to supply regional markets, demonstrating how a national production shock can become a wider trade shock.
Zimbabwe provides an equally useful macroeconomic example because the previous drought affected agriculture and electricity at the same time. World Bank analysis estimated that the 2023 to 2024 drought reduced Zimbabwe’s real GDP by more than 3.2 percent relative to a no drought scenario, with agricultural growth revised from an expected 3.3 percent expansion to a 15 percent contraction, while lower water levels at Lake Kariba constrained hydropower generation and weakened industrial activity.
This link between rainfall and electricity is one of the most important economic channels in Southern Africa because hydropower remains central to the electricity systems of several economies. When reservoir levels fall, the shock reaches mining, manufacturing, retail and services, even where food imports prevent severe shortages. Zambia is particularly exposed because mining is electricity intensive and copper is central to export earnings, which means a rainfall shock can reduce power supply and then feed into lower industrial output, weaker exports, reduced foreign exchange inflows and pressure on government revenue. Governments can respond through electricity imports, thermal generation or rationing, but all three carry costs that eventually affect business margins, public finances or consumers.
Food Prices, Trade Balances and Public Budgets Will Carry the Cost
The food price channel is especially important in African economies because food has a larger weight in consumer price baskets than in most advanced economies. Crop losses reduce supply, flood damaged roads raise transport costs, livestock disease affects meat and milk production, and weaker currencies make imported food more expensive, which means climate shocks can reach measured inflation through several channels at the same time. In countries with limited foreign exchange reserves, a poor harvest also increases demand for imports while raising the local currency cost of those imports, creating pressure on exchange rates and public finances simultaneously.
The IMF has found that worsening drought conditions can create persistent damage to real GDP per capita and raise average inflation by around two percentage points in fragile and conflict affected states, particularly where fiscal space, water security, social protection and economic diversification are already weak. (imf.org)
This creates a difficult policy environment for central banks because renewed food inflation can delay monetary easing even when the source of the shock is agricultural rather than monetary. Governments face a similar problem because they may need to spend more on food imports, emergency support, infrastructure repair and agricultural relief at the same time that weaker economic activity reduces revenue growth. The effect can be especially severe in countries already carrying high debt service obligations, where every additional expenditure competes directly with infrastructure, health, education and other development priorities.
Flooding produces a different but equally costly version of the same problem in Eastern Africa. Roads, bridges and border crossings can be damaged or closed, increasing the cost of moving food and imported goods even where agricultural production itself has not collapsed. Urban flooding can interrupt commerce, tourism, construction and digital services while forcing governments to spend on drainage repair, disease response and reconstruction. ICPAC and FEWS NET have identified several major river basins and urban centres in the region as vulnerable to flooding, including areas around the Juba, Shebelle and Tana rivers and cities such as Nairobi, Mogadishu, Kampala and Addis Ababa.
The World Bank’s October 2026 regional outlook also identifies El Niño related agricultural disruption and food insecurity as a downside risk to growth across Sub Saharan Africa. With public debt across the region still elevated and debt service consuming substantial fiscal resources, the cost of responding to climate shocks increasingly competes with the same spending governments need to improve resilience before the next shock arrives.
Africa’s Exposure Is Ultimately a Productivity and Infrastructure Problem
El Niño repeatedly produces large economic losses across Africa because too much production still depends directly on rainfall and too much infrastructure remains vulnerable to weather extremes. The World Bank notes that more than half of Sub Saharan Africa’s labour force remains connected to rainfed agriculture, which means rainfall anomalies affect not only farmers but also rural incomes, household consumption, food prices, tax collections and industries that depend on agricultural inputs.
The same climate event therefore produces very different economic outcomes depending on whether farms have irrigation, whether households have insurance and savings, whether electricity systems are diversified, whether roads and drainage can withstand heavy rainfall and whether governments have enough fiscal space to respond without destabilising their budgets. A commercial farm with irrigation and access to credit can absorb a failed rainfall season differently from a smallholder household dependent entirely on rain, just as a city with functional drainage can absorb extreme rainfall differently from one where roads and settlements have expanded faster than infrastructure.
This is why the economic discussion needs to move beyond emergency response toward the assets that determine how much each climate shock eventually costs. Irrigation, reservoirs, drainage, flood defences, crop and livestock insurance, weather information, grain storage, diversified electricity generation and regional food trade all reduce the amount of economic value lost when rainfall moves outside normal ranges.
FAO and the World Food Programme have launched a $202 million anticipatory action appeal intended to protect 8.8 million people across 22 high risk countries, while the experience of the previous El Niño showed that relatively small amounts spent before a shock can protect seed stocks, livestock and household assets that would otherwise be lost.
The same principle applies to public infrastructure. Clearing drainage before flooding, strengthening bridges, repairing reservoirs, preparing veterinary vaccines and securing alternative electricity supplies are less visible politically than emergency relief after disaster, but they preserve more economic value because they reduce the initial loss rather than merely financing recovery. African Business quoted Somalia’s national climate finance coordinator describing the country’s challenge as one of repeatedly facing either too much water or too little water, which requires investment in storage, flood control, reservoirs and drainage rather than another cycle of emergency response.
The risk may also extend beyond the end of the current El Niño. NDTV, drawing on WMO and NOAA assessments, reported that the event could move toward ENSO neutral conditions during the northern spring or early summer of 2027, although forecasting uncertainty remains high and a subsequent La Niña remains possible.
That possibility matters because countries can move from one weather shock into another before farmers, households and governments have rebuilt their balance sheets. A drought can be followed by heavy rainfall, flood damaged areas can later move into rainfall deficits, and farmers who lose one crop may have insufficient capital to finance the next season. Southern Africa’s recent experience already demonstrates this sequence, with several economies spending 2025 and 2026 rebuilding grain stocks and reducing food inflation after the 2024 drought only to enter the 2026 to 2027 agricultural season facing another El Niño related dry signal.
The full economic cost of the current event cannot yet be calculated because the most important agricultural seasons are still underway and rainfall forecasts continue to change, but the channels through which the shock will move are already visible. Southern Africa faces the risk of weaker cereal production, renewed food inflation and lower hydropower generation, while Eastern Africa faces a more uneven combination of rainfall deficits, heavy rain, crop damage, livestock disease, infrastructure losses and market disruption. Conflict affected countries face the largest downside because the same weather shock reaches economies where transport systems, public finances, household assets and humanitarian institutions are already weak.
WMO’s forecast that El Niño will persist through February 2027 means governments are already dealing with a live economic risk rather than a distant possibility. The eventual cost will appear in agricultural output, food imports, electricity generation, infrastructure repair, public spending, trade balances and household incomes, and the distribution of that cost will depend heavily on the resilience that countries have already built into their farms, roads, power systems, cities and public finances.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
