Tanzania Sets July 2030 Target for Mchuchuma–Liganga as Financing and Steel Competitiveness Take Centre Stage
Ready
The government of Tanzania and China’s Shudao Investment Group have set a construction-completion target for the integrated development. Its industrial value will depend on securing finance, coordinating the mines and processing facilities, and producing steel that can compete with imports on price, quality and reliability.
Tanzania and China’s state-owned Shudao Investment Group have agreed to target July 2030 for completing construction of the Mchuchuma–Liganga integrated development, setting a new milestone for a project whose economic promise rests on turning domestic mineral resources into competitively priced industrial products.
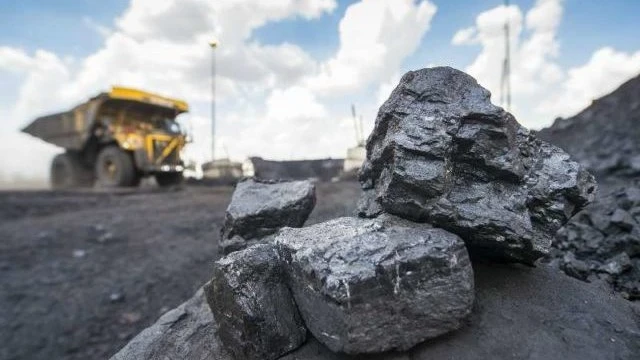
The target emerged from a November 17 meeting in Chengdu between Industry and Trade Minister Judith Kapinga and senior officials of Shudao Investment Group Company Limited, or SDIG. The development would connect coal mining at Mchuchuma with iron ore mining and steel production at Liganga, creating an industrial chain rather than simply another mineral-export operation.
Important preparations remain unfinished. The parties agreed to accelerate the feasibility-study review, joint financial model, project agreements, environmental and social assessment, and engineering designs. Agreements are now expected in the third quarter of Tanzania’s 2026/27 financial year, corresponding to January–March 2027.
Agreements now expected in early 2027
The anticipated signing window is later than the first half of the financial year, July–December 2026, outlined in the Ministry of Industry and Trade’s budget statement. The earlier statement envisaged a three-year construction period.
The revised sequence makes progress on contracts and financing particularly important if the July 2030 construction target is to hold. It also provides a more immediate benchmark: whether the parties can complete the outstanding agreements during the first three months of 2027.
Published accounts of the latest meeting do not identify committed lenders, a financial-close date or a firm construction-start date. July 2030 should consequently be understood as a delivery target, not confirmation that the investment has secured all the resources and approvals needed to meet it.
For businesses considering contracts, equipment orders or investments linked to the development, that distinction matters. An agreed timetable can guide planning, but it does not carry the same commercial certainty as signed contracts, committed financing and a construction programme supported by procurement decisions.
Six linked components must advance together
The National Development Corporation’s September outline illustrates the scale of coordination required.
It described six phases encompassing the Mchuchuma coal mine, Liganga iron ore mine, coal-processing facilities for iron smelting, a steel plant, electricity generation using steam from the steelworks, and approximately 70 kilometres of connecting road. At that stage, implementation was expected to begin in 2027.
These components cannot be assessed independently. A mine operating ahead of its processing facilities may have limited immediate commercial value. A steel plant completed before reliable feedstock, utilities and transport connections are available could incur financing and maintenance costs while producing little revenue.
Coordinating the facilities is therefore as important as completing each construction package. Integration offers the opportunity to retain more value within a single production system, but it also creates dependencies through which a delay in one component can affect the entire operation.
Construction completion must also be distinguished from commercial production. Equipment testing, commissioning, product certification and the gradual increase in output can continue after physical works finish.
For customers and investors, the commercially meaningful milestone will be consistent production of saleable steel, not the completion date alone.
Domestic resources do not guarantee cheaper steel
The project’s industrial logic is substantial. Tanzania could capture more economic value by converting iron ore into usable steel than by exporting unprocessed material alone, provided the additional processing generates returns above its costs.
The potential benefits extend beyond the steelworks to engineering, fabrication, equipment maintenance, transport and other businesses supplying industrial production.
The central economic test, however, is whether the resulting steel can compete with imported alternatives. Domestic iron ore and coal provide a resource foundation, but they do not automatically establish a cost advantage. Mining, processing, energy, transport, financing and maintenance must all be covered by the prices customers are willing to pay.
The relevant comparison is the delivered cost of a suitable domestic product against the landed and delivered cost of its imported equivalent.
A plant can be technically efficient yet commercially disadvantaged if transport to major customers is expensive, borrowing costs are high or output remains below the level needed to spread fixed costs across sufficient production.
Product specifications will matter just as much as aggregate tonnage. Steel used in construction, machinery, infrastructure and manufacturing is not interchangeable. The extent of import substitution will depend on which grades and products the complex can supply, whether they meet required standards and whether deliveries are dependable.
For contractors and manufacturers, a reliable domestic supplier could make procurement more predictable and reduce some exposure to international shipping disruptions. Buyers will nevertheless continue to compare price, quality, credit terms and delivery performance.
Local production becomes an enduring industrial advantage when customers choose it on commercial grounds, rather than solely because it receives protection from competing imports.
Demand and financing will determine commercial viability
Demand is a financing question as well as a marketing question. Credible purchasing commitments would help demonstrate that projected output has a market. Conversely, a financial model built around high capacity utilisation without convincing evidence of demand could overstate revenue and underestimate the time needed for the operation to become self-sustaining.
The joint financial model should expose those assumptions to realistic stress. Lower steel prices, construction overruns, delayed commissioning and slower sales would each affect the project’s ability to service debt. Their combined effect could be more significant than any single risk considered in isolation.
Financing structure will determine who bears those pressures. If borrowing is denominated in foreign currency while a substantial share of sales is collected in shillings, depreciation could increase debt-service costs relative to revenue. Long repayment periods and an appropriate balance between debt and shareholder capital could improve resilience, but the latest announcement does not disclose those terms.
Public-sector participation also requires a distinction between industrial ambition and fiscal exposure. Any future guarantees, infrastructure commitments or investment incentives would need to be assessed against their cost and the risks retained by the state.
Such support should not be assumed from the completion target itself. The investment case must establish both the project’s potential returns and the obligations that would fall on its shareholders, lenders and public institutions.
Foreign-exchange benefits will emerge in stages
The foreign-exchange case deserves equally careful treatment. The ministry’s 2026/27 budget statement put the potential savings from replacing imported steel products at US$1.22 billion. That is a projected benefit, not a realised improvement in Tanzania’s external accounts.
Gross import substitution would not necessarily equal the project’s net foreign-exchange contribution.
Construction could initially require substantial imports of machinery and technical services. During operation, imported inputs, replacement equipment, foreign debt service and any overseas profit distributions would also have to be considered alongside the value of imports displaced and exports generated.
The project could therefore increase demand for foreign currency during development before delivering external-sector benefits later.
Its contribution should ultimately be measured over the investment’s operating life, rather than inferred from a single estimate of steel imports that might be replaced. The stronger outcome would be a production system that consistently earns or saves more foreign currency than it requires to operate, maintain equipment and meet external obligations.
Local suppliers need opportunities beyond construction
For Tanzanian businesses, the opportunity depends partly on how procurement is organised.
Construction and operation could create demand for civil works, haulage, fabrication, maintenance, catering and professional services. Local firms would benefit most where contract packages are accessible, technical requirements are clear and payment arrangements allow suppliers to manage working capital.
A large order is not necessarily a viable opportunity for a smaller business if it requires expensive equipment, lengthy payment periods or financing that the supplier cannot obtain.
Industrial capability would deepen further if domestic businesses acquired skills and contracts beyond the construction phase. Maintenance, spare-parts production, quality testing and specialist engineering could generate more durable value than a temporary increase in building activity.
Supplier development and workforce training would therefore be important complements to the main investment. The long-term industrial dividend would be stronger if Tanzanian companies became capable participants in the production system, rather than remaining peripheral service providers.
Environmental decisions will shape costs and timing
Environmental and social assessments will influence both the timetable and the project’s economics.
Water requirements, land access, emissions, waste management and any necessary compensation can affect engineering choices, operating costs and community relations. With assessments still among the outstanding preparations, the final implications and mitigation commitments remain to be established.
These issues belong within the investment case. Addressing them early can help establish a more credible cost estimate and implementation programme. Leaving major requirements unresolved risks creating additional expenses or redesign work after procurement and construction decisions have been made.
For surrounding communities, the quality of consultation and the clarity of commitments will be important measures of progress alongside the national completion target.
What happens next
The next decisive milestone is the anticipated January–March 2027 signing window.
Beyond signatures, businesses and investors will need evidence of committed financing, an updated project configuration, environmental approvals and a coordinated procurement and construction programme. Those developments would provide a firmer basis for assessing the July 2030 target than another statement of intent.
Subsequent progress should be measured through mobilisation, physical construction, equipment installation, commissioning and sustained production. Each stage answers a different question about whether the project is moving from preparation towards commercial operation.
July 2030 now provides a benchmark against which delivery can be judged. The deeper economic test is whether Mchuchuma–Liganga can move from mineral resources and construction expenditure to sustained, competitive production, supplying customers reliably, developing Tanzanian industrial capabilities and generating a positive return on the capital committed.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
