East Africa Builds Infrastructure as Secure Employment Remains Scarce
Ready
Infrastructure governance improved across Tanzania, Kenya, Uganda and Burundi between 2016 and 2025, according to the latest Ibrahim Index of African Governance. Yet the same assessment places Tanzania 43rd, Uganda 42nd and Burundi 49th in secure employment opportunities, while Kenya's latest labour statistics show that more than 87% of jobs added in 2025 were informal. As governments expand railways, roads, electricity networks and digital infrastructure, the findings raise questions about how public investment translates into productive businesses, stable earnings and employment for East Africa's growing population.
East African countries have recorded substantial improvements in infrastructure over the past decade, but the expansion of transport networks, electricity supply and telecommunications has not been accompanied by equally strong performance in secure employment, according to the 2026 Ibrahim Index of African Governance. Tanzania's infrastructure score increased by 14.5 points between 2016 and 2025, Burundi improved by 11.7 points, Kenya by 9.7 points and Uganda by 9.2 points. Yet their respective scores in Secure Employment Opportunities remained considerably weaker, with Tanzania ranking 43rd among Africa's 54 countries, Uganda 42nd, Burundi 49th and Kenya 30th. The findings expose an economic challenge confronting governments across the region as they commit substantial capital to infrastructure while struggling to expand the number of jobs offering dependable incomes and greater financial security.
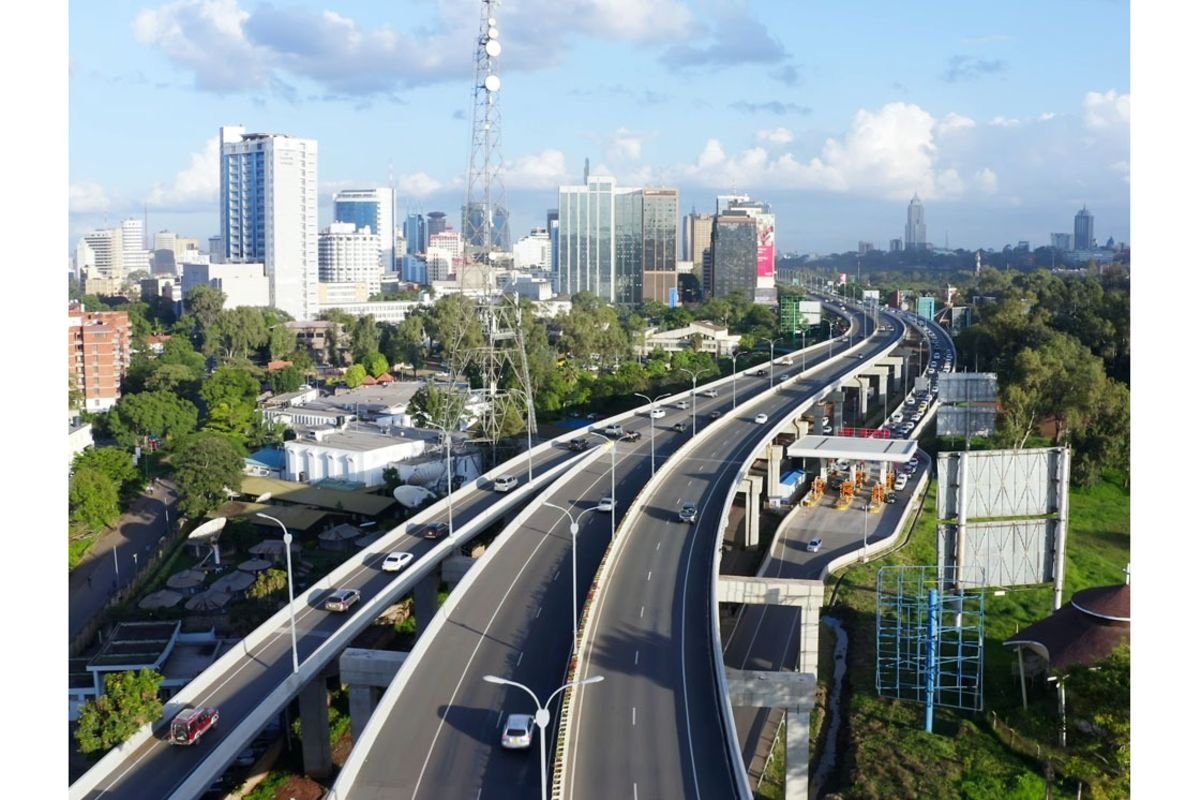
The contrasting results are particularly relevant because infrastructure investment has become central to East Africa's development strategies. Tanzania is extending its standard gauge railway and investing in electricity generation, ports and logistics infrastructure, Kenya is developing transport corridors and expanding electricity and digital connectivity, while Uganda is pursuing petroleum infrastructure, road development and investments intended to support industrial activity. Burundi, operating from a substantially smaller economic base, has also improved several measures of transport and telecommunications infrastructure. These investments can reduce the cost of doing business and support economic growth, but the availability of infrastructure does not automatically establish that enterprises are expanding production, creating permanent jobs or paying wages sufficient to improve household living standards.
The 2026 Ibrahim Index of African Governance, released by the Mo Ibrahim Foundation on October 31, 2026, identifies Infrastructure as the most improved of the 16 governance subcategories assessed across Africa. The continental score rose by 7.7 points to 43.4 between 2016 and 2025, with 52 of the continent's 54 countries recording improvements. Those countries account for approximately 84.5% of Africa's population, and 45 recorded an accelerating pace of infrastructure improvement during the more recent part of the decade. Mobile communications, internet connectivity, energy access, and shipping and postal networks contributed substantially to the gains, reflecting a broad expansion of physical and digital infrastructure.
Employment presents a more complicated picture because governments and statistical institutions measure work using different concepts. A person may be counted as employed while undertaking irregular, poorly remunerated or vulnerable work, including subsistence agriculture, informal trading or self employment with limited capital and earnings. Similarly, an increase in the number of jobs does not establish that those positions offer stable wages, social protection or opportunities for career advancement. The Ibrahim Index's Secure Employment Opportunities indicator focuses on the extent to which employed people are not living in poverty and are not engaged in vulnerable employment. It therefore captures aspects of employment quality rather than the total number of people working or the conventional unemployment rate.
The distinction is supported by separate labour market evidence. Kenya's National Bureau of Statistics reported that the economy added approximately 822,100 jobs in 2025, but 87.2% were in the informal sector. Uganda's latest labour market survey, covering July to September 2026, found that 86.9% of employment outside agriculture was informal, while unemployment stood at 11.8% and a substantially larger share of the potential workforce experienced labour underutilisation. In Tanzania, the World Bank's October 2026 economic update identified the quality and productivity of employment as a principal development challenge despite continuing economic growth. These findings concern different national statistical series and should not be treated as directly comparable measurements, but they reinforce the central issue identified by the Ibrahim Index: economic growth and infrastructure expansion do not necessarily produce a corresponding increase in secure, productive employment.
Infrastructure Improvement Has Been Widespread, but Employment Quality Remains Uneven
The country scorecards show that all four economies improved infrastructure performance between 2016 and 2025, although the magnitude and composition of those gains differed. Tanzania recorded the largest improvement among the four countries, gaining 14.5 points and reaching an Infrastructure score of 51.3, ranking 15th in Africa. Kenya achieved a higher overall infrastructure score of 57.6, ranking 11th, after gaining 9.7 points. Uganda improved by 9.2 points to 46.6, ranking 18th, while Burundi increased its score by 11.7 points to 28.1, ranking 45th. The results demonstrate progress across economies at very different stages of infrastructure development, while also showing that gains from a low starting point do not necessarily produce a high final ranking.
| Country | Infrastructure score, 2025 | Infrastructure change, 2016–2025 | Secure employment score, 2025 | Secure employment rank |
| Kenya | 57.6 | +9.7 | 47.7 | 30th |
| Tanzania | 51.3 | +14.5 | 28.8 | 43rd |
| Uganda | 46.6 | +9.2 | 29.7 | 42nd |
| Burundi | 28.1 | +11.7 | 13.3 | 49th |
Source: Mo Ibrahim Foundation, 2026 Ibrahim Index of African Governance, country scorecards for Kenya, Tanzania, Uganda and Burundi. Scores are out of 100, and changes represent index points rather than percentages. The most pronounced contrast among the larger economies is visible in Tanzania. Its Infrastructure score reached 51.3 after a 14.5 point improvement, while Secure Employment Opportunities remained at 28.8 despite a 4.0 point increase since 2016. Its Public Perception of Economic Opportunities indicator, however, increased by 24.8 points to 62.5, ranking third in Africa. This combination suggests that the economic environment and public expectations of opportunity have improved more strongly than the conditions captured by the secure employment measure. The difference between these scores should not be interpreted as a quantified shortage of jobs, because the indicators assess different concepts, but it creates a basis for examining how improvements in infrastructure and economic confidence are reflected in actual employment arrangements.
Uganda presents a related pattern. Its Infrastructure score improved by 9.2 points, supported by increases of 19.9 points in Mobile Communications, 19.8 points in Internet and 13.3 points in Access to Energy. Secure Employment Opportunities improved by only 3.1 points to 29.7, while the wider Business & Labour Environment score deteriorated by 6.2 points. Regional Integration declined by 23.9 points, Economic Diversification by 16.8 points and Business & Competition Regulations by 14.3 points, indicating that progress in physical and digital infrastructure occurred alongside deterioration in several institutional conditions affecting business activity.
Kenya has a different profile because its infrastructure and secure employment scores are both higher than those of Tanzania and Uganda, although the employment indicator remains below 50. Its Access to Energy score gained 20.8 points and Internet improved by 21.9 points, while Business & Competition Regulations increased by 12.6 points to 81.9. Secure Employment Opportunities nevertheless declined by 3.6 points to 47.7, and Public Perception of Economic Opportunities fell by 5.9 points to 35.6. These results suggest that improvements in infrastructure and business regulation have not been accompanied by equivalent progress in employment security or public perceptions of economic opportunity, an observation that is consistent with Kenya's recent employment statistics showing that informal work accounts for most additional jobs.
Burundi's infrastructure improvement has occurred from a substantially weaker starting position. Its Transport Network score increased by 11.9 points to 30.9, while Mobile Communications gained 16.4 points to 48.4. However, Access to Energy remained at just 3.9 and Internet scored 3.5, placing Burundi near the bottom of the continental rankings on both measures. Secure Employment Opportunities stood at 13.3, the weakest among the four countries examined. Burundi therefore faces a different economic challenge from Kenya and Tanzania: it must continue expanding basic infrastructure access while also creating the productive activities and employment conditions that allow households to earn more reliable incomes.
Tanzania's Jobs Challenge Is Increasingly About Productivity and Earnings
Tanzania provides one of the clearest examples of the economic distinction between infrastructure development and the creation of higher quality employment. The country has undertaken substantial investments in transport, electricity, ports and digital services, including the standard gauge railway connecting Dar es Salaam with Dodoma and additional sections intended to improve access to inland markets. Its infrastructure improvements are reflected in the Ibrahim Index through gains in Transport Network, Shipping & Postal Network, Access to Energy, Mobile Communications and Internet. Such developments can reduce transport delays, improve access to markets and lower some of the operational constraints facing producers, traders and businesses, particularly when they are accompanied by reliable services and commercially competitive prices.
However, the World Bank's September 2026 Tanzania Economic Update, published with a special focus on employment under the theme Making Jobs Work, identifies a more fundamental challenge in how the country's labour market operates. The report estimates that Tanzania's economy grew by 5.9% in 2025 and projects growth of 6.1% in 2026, but finds that a large proportion of workers remain engaged in activities characterised by low productivity, limited earnings and vulnerability to economic shocks. The Bank's analysis emphasises that Tanzania has a high employment rate, while the availability of more productive and better paying work remains constrained, particularly in agriculture and informal activities.
The distinction matters because conventional unemployment figures can obscure the economic circumstances of households that cannot afford to remain without work. A person cultivating a small plot, selling goods at a roadside stall or undertaking irregular transport and construction activities may be classified as employed while earning relatively little and receiving no employment benefits. These activities support livelihoods and are economically consequential, but they may not offer the productivity, capital investment or income security associated with employment in larger, better organised enterprises. For Tanzania, improving economic welfare therefore requires raising earnings and productivity within existing employment as well as expanding opportunities for wage employment in businesses capable of sustained growth.
The World Bank identifies two connected priorities: developing a stronger workforce through education, skills, social protection and labour market systems, and expanding the number of productive firms capable of employing workers at better wages. Firas Raad, the Bank's Division Director for Tanzania, said that improvements in skills, education and health would be necessary to translate continued economic growth into better employment outcomes. Mary Jean Moyo, the International Finance Corporation's Division Director for Tanzania, similarly identified the expansion of productive firms as central to the country's employment challenge. These assessments place business growth, workforce capabilities and the quality of employment at the centre of the economic discussion, rather than relying on infrastructure expenditure or headline GDP growth as sufficient evidence of progress.
Tanzania's Development Vision 2050 creates a longer term framework for addressing these issues through industrialisation, productivity improvements, private investment and higher incomes. Its ambitions depend partly on whether infrastructure projects generate opportunities for firms to expand production and access markets. The standard gauge railway, for example, could improve the economics of freight transportation for manufacturers, agricultural exporters and mining companies if businesses can access reliable services at competitive prices. Electricity investments can support manufacturing and processing when firms receive dependable power and can finance equipment and expansion. Improved ports can increase logistics efficiency, but the economic benefits depend on their integration with transport networks, industrial activity and regional trade.
These relationships are not automatic. A railway can reduce travel time without creating substantial permanent employment if industrial production does not increase. Additional electricity generation may improve supply reliability without attracting new factories where financing costs, market demand, regulations or workforce skills remain obstacles. Similarly, more efficient ports may increase cargo throughput while generating relatively limited direct employment because modern logistics increasingly depends on mechanisation and digital systems. The wider benefits emerge when lower costs enable businesses throughout the economy to produce, trade and employ additional workers.
This is particularly relevant to Tanzania because the economic effects of infrastructure are distributed across sectors and locations. A new transport corridor may benefit freight operators, agricultural producers, manufacturers and consumers in different ways, while some communities may experience mainly temporary construction employment. Understanding its contribution to job creation therefore requires information on construction jobs, permanent operating positions, businesses established along the corridor, changes in freight costs and the subsequent expansion of productive activity. The Ibrahim Index records improvements in infrastructure conditions and measures aspects of employment security, but it does not provide project specific employment multipliers or establish how many jobs were created by a particular investment.
Kenya Created 822,100 Jobs in 2025, but Most Were Informal
Kenya's 2026 Economic Survey provides some of the clearest national evidence of the difference between employment growth and job quality. According to the Kenya National Bureau of Statistics, the economy added approximately 822,100 jobs in 2025, compared with 782,300 in 2024, while employment outside small scale agriculture and pastoral activities increased to approximately 21.6 million. However, 87.2% of the additional jobs were created in the informal sector, equivalent to roughly 716,800 positions, bringing informal employment to approximately 18.1 million. Formal employment increased during the year, but accounted for a much smaller share of new opportunities.
Where Kenya's additional jobs were created in 2025 Kenya National Bureau of Statistics, Economic Survey 2026. The 12.8% balance is the share outside the informal sector, not a count of permanent or socially protected jobs.
The Kenyan figures are economically important because informal enterprises perform substantial productive and commercial functions, including retail trade, transport, food preparation, construction, repairs, personal services and manufacturing at small scale. The sector provides livelihoods for millions of households and contributes to the circulation of goods and services throughout the economy. However, many informal activities face constraints involving access to capital, business premises, market information, equipment, social insurance and predictable earnings. Informal employment should not automatically be equated with poverty or insecure work, because some informal businesses generate substantial income, but the sector's dominance indicates that formal wage employment is absorbing only a limited proportion of additional workers.
The relationship with infrastructure is particularly apparent in Kenya, where investment in transport, telecommunications and electricity has improved the conditions supporting commercial activity. Nairobi's digital services industry, mobile money market and financial institutions operate within infrastructure that has expanded substantially during the past decade, while highways, railways and electricity connections support industrial production and trade. Yet many workers continue to earn their living through small businesses, self employment and casual activities whose income depends on customer demand and operating costs. Improved connectivity may make it easier to establish a business or receive payments, but it does not necessarily increase the profitability or stability of that business.
Kenya's Secure Employment Opportunities score declined by 3.6 points between 2016 and 2025 despite improvements in Infrastructure, Business & Competition Regulations and Access to Energy. The index also records a deterioration of 5.9 points in Public Perception of Economic Opportunities. These findings are consistent with the existence of persistent employment quality concerns, although the IIAG measure and the KNBS employment series use different methodologies and should not be interpreted as directly interchangeable. The former assesses employment poverty and vulnerability within a composite framework, while the latter records employment changes using national statistical classifications.
The commercial challenge is to establish conditions under which small enterprises can grow beyond survival activities and employ more people on predictable terms. Infrastructure can contribute by reducing costs, but business growth also depends on affordable credit, predictable taxation, access to customers, workforce skills and the ability to operate at sufficient scale. In manufacturing, for example, transport and electricity investments can improve competitiveness, but firms must still manage imported inputs, finance equipment, meet quality standards and secure reliable demand. In services, digital infrastructure can enable new businesses, while the stability of employment depends on their ability to generate sufficient revenue and retain customers.
Kenya's experience therefore complicates the use of employment creation figures as a measure of economic performance. An economy may add hundreds of thousands of jobs while much of the growth occurs in activities offering irregular incomes and limited security. Assessing the quality of growth requires information on earnings, hours worked, productivity, employment benefits, business survival and opportunities for workers to move into more productive activities.
Uganda's Latest Labour Survey Shows How Much Unemployment Statistics Miss
Uganda's latest labour market data provide additional evidence of the distinction between employment and economic security. The Uganda Bureau of Statistics reported in its first quarterly Labour Market Survey for 2026/27, covering July to September 2026, that approximately 14.0 million people aged 14 to 64 were employed, representing 48.9% of the working age population. The unemployment rate stood at 11.8%, while youth unemployment among those aged 18 to 30 reached 14.6%. However, the survey also found that 44.5% of the extended labour force was underutilised when unemployment, insufficient working hours and the potential labour force were considered together.
The broader measures provide a substantially different picture from unemployment alone. Almost half of unemployed respondents had been seeking work for at least a year, while 18.4% of employed people reported working fewer hours than they wanted. Among young people, labour underutilisation reached 47.4%, compared with an unemployment rate of 14.6%. Women faced particularly severe constraints, with unemployment among young women reaching 20.4% and underutilisation rising to 57.2%, compared with 12.3% and 33.5% respectively among young men. These differences indicate that the difficulty of obtaining sufficient paid work extends well beyond people conventionally classified as unemployed.
Uganda's labour market, July to September 2026
11.8%
Unemployment rate
44.5%
Composite labour underutilisation
86.9%
Informal employment excluding agriculture
47.4%
Youth labour underutilisation
Uganda Bureau of Statistics, Labour Market Survey 2026/27, first quarter. Unemployment and labour underutilisation use different denominators and should not be added together.
The survey found that independent workers without employees accounted for 47.4% of employed people, while employees represented 28.6% and dependent contractors accounted for 19.0%. Services employed approximately half of the workforce, followed by agriculture, forestry and fishing, while industry represented 13.5%. The distribution indicates that much of Uganda's employment depends on individual economic activity and relatively small enterprises, rather than large employers offering permanent wage positions. When agriculture was included, 91.7% of jobs were classified as informal; the corresponding figure excluding agriculture was approximately 87%, reinforcing the scale of the employment quality challenge.
The establishment component of the survey presents a similarly revealing picture of formal job creation. Formal establishments employed approximately 2.58 million people at June 30, 2026, with services accounting for 82.9% of those positions and industry accounting for 13.7%. During April to June 2026, surveyed establishments reported 38,036 jobs created and 10,375 jobs lost, producing net employment growth of 27,661 positions. Services generated almost all the net increase, while industry recorded a net loss of 1,237 jobs. These figures refer to formal establishments covered by the survey and should not be combined with household employment totals as though they represented the same reporting period or population.
The findings are particularly relevant to Uganda's industrial development ambitions. The government has invested in electricity, road networks, industrial parks and infrastructure associated with petroleum production, with expectations that these developments will support manufacturing, processing, exports and employment. However, the labour survey indicates that the industrial sector was not the principal contributor to net formal employment growth during the quarter examined. This does not establish that industrial policy has failed, because employment effects depend on the stage of investment, the sector and the period assessed, but it demonstrates the importance of monitoring actual labour market outcomes rather than assuming that new infrastructure will produce sustained industrial employment.
Uganda's employment challenge also concerns the ability of firms to retain workers and fill available positions. The survey recorded 84,347 vacancies in formal establishments during April to June 2026, of which 39.4% remained unfilled, while 111,390 employees left their establishments during the quarter. Business expansion accounted for 78.7% of newly created jobs, indicating that firm growth remains a central source of employment demand. The combination of vacancies, turnover and underutilised workers suggests that labour market difficulties can involve skills mismatches, working conditions, geographic constraints and the attractiveness of available jobs, in addition to the total number of opportunities.
Burundi Must Expand Basic Infrastructure While Building a More Productive Labour Market
Burundi's position differs from those of its larger neighbours because its infrastructure score remains among the weakest in Africa despite substantial improvement over the decade. The country's Infrastructure indicator increased by 11.7 points to 28.1, ranking 45th, while Access to Energy scored only 3.9 and ranked 53rd. Internet connectivity scored 3.5, ranking 52nd, and Mobile Communications reached 48.4 after improving by 16.4 points. Transport Network performed comparatively better, reaching 30.9 and ranking 17th, but the overall results indicate that electricity and digital infrastructure remain substantial constraints on economic activity.
The weakness of electricity access is especially consequential for industrial development. Manufacturing, agroprocessing, refrigeration, hospitality and other commercial activities require electricity that is affordable and available when needed. Where supply is insufficient or unreliable, firms may rely on alternative power sources, operate at reduced capacity or avoid investing in equipment whose commercial viability depends on consistent energy availability. Limited digital connectivity creates additional constraints for businesses seeking access to information, digital payments and larger markets, while affecting the capacity of public institutions to deliver services electronically.
Burundi's Secure Employment Opportunities score of 13.3, ranking 49th in Africa, indicates that weaknesses in employment quality are occurring alongside substantial infrastructure deficits. Its Foundations for Economic Opportunity score improved by 6.5 points to 45.6, and Rural Economy gained 11.6 points to 70.3, suggesting some progress in the conditions supporting economic activity. However, improvements in rural support and infrastructure have yet to produce a strong position in the index's measure of secure employment, which considers working poverty and vulnerable employment rather than the simple existence of work.
The economic opportunity for Burundi lies partly in improving the conditions under which agricultural production can support higher incomes and additional businesses. Electricity availability, rural roads, storage, processing facilities and access to financial services can influence whether farmers sell unprocessed produce at relatively low prices or participate in commercial activities generating greater value. The same investments could support employment in transport, food processing, equipment maintenance and distribution, but those outcomes depend on access to markets, commercial financing and the capacity of firms to operate profitably.
Burundi's improving Rural Economy score therefore provides an important qualification to its relatively weak secure employment performance. The country has recorded progress in some conditions supporting rural economic activity, but the gap between those gains and employment security suggests that improving physical access and agricultural support is only part of the development challenge. Raising household earnings will also require better productivity, stronger commercial connections and businesses capable of creating employment beyond subsistence activities.
The Missing Connection Between Public Infrastructure and Private Enterprise Growth
The four country comparisons point towards a common economic issue: infrastructure creates the conditions under which businesses can operate, but the number and quality of jobs generated depend on how enterprises respond to those conditions. A new road can reduce transportation costs, an electricity connection can allow a factory to operate machinery, and faster internet can enable digital transactions, but firms must still identify profitable markets, access working capital, purchase equipment, recruit workers and maintain sufficient demand to expand. These requirements help explain why substantial infrastructure improvements can occur without comparable improvements in employment security.
For East Africa, the connection between infrastructure and enterprise growth is particularly relevant because substantial portions of the workforce remain engaged in agriculture, small scale trading, informal services and self employment. Such activities often operate with limited equipment and access to finance, meaning that the benefits of infrastructure may be constrained by other commercial conditions. A farmer may gain access to a better road but remain unable to finance storage or processing equipment. A manufacturer may receive more reliable electricity but lack affordable credit to expand production. A small trader may adopt digital payments without generating sufficient additional revenue to employ workers or increase household income.
These constraints also influence the economic returns generated by public infrastructure. The value of a transport corridor depends partly on the volume of goods moving through it, while industrial electricity demand depends on the number and scale of productive enterprises operating within its service area. Where businesses cannot expand, infrastructure may remain underused or generate smaller economic benefits than anticipated. Conversely, when new capacity enables firms to reach markets, reduce costs and increase output, the economic contribution can extend well beyond the direct employment created during construction.
The employment effects also differ across types of infrastructure. Road and railway construction can require substantial labour during implementation, but the number of permanent positions associated with operating the completed assets may be considerably smaller. Electricity infrastructure can support employment across manufacturing and services, although improvements in productivity sometimes allow businesses to increase output without employing workers in the same proportion. Digital infrastructure can create commercial opportunities for small enterprises and technology businesses, but it can also automate transactions or reduce the labour required for certain activities. Measuring employment solely through jobs directly associated with constructing an asset may therefore understate some economic benefits while overstating the durability of temporary work.
A more useful assessment would examine the businesses and economic activities enabled by completed projects. For transport corridors, relevant measurements include freight volumes, changes in logistics costs, industrial production and the establishment of new enterprises. For electricity investments, the analysis should consider commercial connections, energy reliability, utilisation by productive industries and the expansion of businesses that previously faced supply constraints. For digital infrastructure, useful evidence includes business adoption, transaction costs, enterprise productivity and the extent to which technology supports income growth.
The Organisation for Economic Co operation and Development's Africa's Development Dynamics 2024 provides historical context for the employment challenge. Drawing on International Labour Organization data, it estimated that approximately 65% of East African workers were in vulnerable employment in 2021, compared with 33% in North Africa. Agriculture, forestry and fishing accounted for approximately 58% of employment in East Africa, while wholesale and retail trade represented 11% and manufacturing only 6%. The figures illustrate how strongly the region's labour markets have depended on agriculture and relatively small scale activities, although they describe 2021 and should not be presented as the current employment distribution in every East African country.
The OECD's assessment also identifies skills development and digital capabilities as relevant to improving productivity. These conditions matter because infrastructure expansion can change the types of labour that businesses require. Firms operating modern logistics facilities, industrial machinery or digital systems may need technicians, engineers, managers and workers with specialised capabilities. Where training systems do not provide those skills, businesses may struggle to fill vacancies even while large numbers of people seek employment.
East Africa's Industrial Corridors Need to Be Judged by What They Produce
The region's major transport and energy investments provide opportunities to examine how infrastructure can contribute to productive employment across national borders. Tanzania's Central Corridor connects Dar es Salaam with inland markets and neighbouring countries, while Kenya's Northern Corridor links Mombasa with Uganda and other economies in the Great Lakes region. Uganda's petroleum developments are expected to create demand for logistics, engineering, maintenance and supporting services, while Burundi's access to regional trade routes influences the cost of importing equipment and exporting products.
These corridors are commonly assessed through construction progress, financing commitments, kilometres completed and estimated transport savings. Such measures are relevant, but a fuller economic evaluation requires examining whether businesses use the infrastructure to expand production and trade. A more efficient railway serving a region with limited industrial output may initially carry relatively little freight, while a road connecting productive agricultural areas to processing facilities and export markets may support income and employment gains beyond the immediate construction programme. The distinction becomes particularly important where infrastructure financing creates substantial debt obligations or requires ongoing operating subsidies.
Regional integration also influences whether infrastructure investments generate their expected commercial benefits. A railway or highway crossing national markets may improve physical connectivity, but businesses can continue encountering customs delays, inconsistent standards, restrictions affecting transport operations or other regulatory obstacles. These conditions can reduce the commercial advantages created by improved infrastructure. The IIAG records progress in regional integration for Kenya, Tanzania and Burundi between 2016 and 2025, but Uganda's Regional Integration indicator deteriorated sharply by 23.9 points, demonstrating that physical infrastructure and the institutional arrangements governing regional trade can develop in different directions.
For governments pursuing industrialisation, an important policy consideration is the relationship between infrastructure planning and productive investment. Industrial parks, transport corridors and energy projects may become more economically useful when they are accompanied by commercially viable opportunities in manufacturing, processing, logistics and supporting services. However, creating industrial facilities without sufficient demand, financing or competitive conditions can result in infrastructure whose productive potential is not fully realised.
The private sector therefore occupies a central position in the region's employment challenge. Public investment can provide roads, electricity and other services, but a substantial proportion of sustained employment growth must emerge from enterprises capable of generating sufficient revenue to employ workers on reliable terms. The World Bank's 2026 assessment of Tanzania explicitly identifies the expansion of productive firms as essential to improving employment quality, while Uganda's quarterly labour survey shows that business expansion accounted for nearly four fifths of new jobs recorded among formal establishments during the period examined. These findings point towards the importance of enterprise growth alongside public infrastructure investment.
Employment Quality Should Become a Central Measure of Development Performance
East African governments have established ambitious infrastructure and economic development programmes, but the results of those investments need to be assessed through a wider set of indicators than physical construction alone. The Ibrahim Index confirms that infrastructure conditions improved across Tanzania, Kenya, Uganda and Burundi during the decade ending in 2025, while their Secure Employment Opportunities scores remained relatively weak. The underlying employment evidence also demonstrates that many workers continue earning livelihoods through informal activities, self employment and other arrangements that may offer limited financial security.
Employment quality involves several distinct conditions, including earnings, productivity, working hours, stability, legal protections and access to social insurance. These conditions differ across workers even within the same sector. A self employed business owner may earn more than a salaried employee, while a worker in a formally registered enterprise may still experience low wages or temporary employment. Consequently, informality should not be treated as an automatic measure of poverty, and formal employment should not be assumed to guarantee adequate earnings. Nevertheless, the high prevalence of informal and vulnerable work indicates why conventional employment totals provide an incomplete assessment of economic development.
Governments can improve the information available for evaluating infrastructure and employment by reporting more consistently on the economic activities generated after projects are completed. Publicly financed transport projects could disclose operational volumes, associated commercial activity and employment changes in connected industries. Electricity projects could report the growth of productive connections and changes in industrial demand, while industrial development programmes could distinguish temporary construction employment from permanent positions created by operating businesses.
The cost of generating employment also deserves examination. Large infrastructure investments may support substantial economic activity over time, but they require financial resources that could be allocated to different development priorities. Comparing projects according to jobs directly created during construction would produce an incomplete result, because some investments generate benefits through higher productivity rather than large permanent workforces. However, governments can assess whether the combination of productivity gains, business expansion, household income and public revenues justifies the full financial cost of an investment.
Workforce development must also be considered alongside infrastructure. Expanding education and technical training can help workers qualify for employment in manufacturing, transport, energy and professional services, while improvements in health and social protection can strengthen productivity and reduce household vulnerability. The benefits depend on the relationship between training programmes and actual employer demand, particularly where workers are preparing for sectors that require specialised technical capabilities.
The World Bank's assessment of Tanzania and the latest Ugandan labour market statistics both identify productive employment as a central development challenge. Kenya's 2025 employment figures add evidence that substantial job creation can occur mainly through informal activity. Burundi's comparatively weak infrastructure and secure employment scores illustrate the difficulties facing economies that must expand basic access while building more productive commercial activity. The countries differ in their economic structures and available resources, but their labour markets demonstrate the need to connect infrastructure policy with enterprise growth and household earnings.
Infrastructure Progress Has Outpaced Improvements in Employment Security
The 2026 Ibrahim Index establishes that East Africa has made measurable progress in infrastructure during the past decade. Tanzania's score increased by 14.5 points, Burundi's by 11.7, Kenya's by 9.7 and Uganda's by 9.2. Those gains reflect improvements in transport, telecommunications, energy and other services that can support economic activity, while the different national scores indicate that substantial infrastructure deficits remain in some countries.
The employment evidence suggests that the benefits have not translated into equally strong performance in secure employment. Tanzania and Uganda rank in the bottom quarter of African countries on the Ibrahim Index's Secure Employment Opportunities indicator, while Burundi ranks even lower. Kenya performs comparatively better but continues to record employment growth concentrated overwhelmingly in informal activity. The World Bank's 2026 Tanzania assessment, Kenya's national employment statistics and Uganda's latest labour survey all identify problems involving the quality, productivity or adequacy of work, although each uses different measures and reporting periods.
These findings do not imply that infrastructure investment has failed or that the region would have achieved better employment outcomes without it. Roads, railways, electricity and communications can make economic activity possible and reduce costs across numerous industries. Their contribution to employment depends on the businesses that use them, the markets those businesses serve, the skills available to workers and the conditions affecting private investment.
For Tanzania, Kenya, Uganda and Burundi, the next measure of development progress will increasingly concern how expanding infrastructure capacity contributes to productive enterprises, higher earnings and more secure livelihoods. The region has improved many of the physical conditions required for economic activity. Its employment statistics show why the development of those conditions must be accompanied by sustained growth in the businesses and industries capable of converting them into better work.
 Uchumi360
Business Intelligence
Uchumi360 covers business, investment, and economic policy across East, Central, and Southern Africa.
For the serious reader
You read to the end. That places you in a small group.
Uchumi360 is built for readers who demand precision over speed, structure over sentiment, and analysis that holds uncomfortable conclusions rather than softening them. If this work sharpens how you think about Africa's economy, help us keep building the infrastructure behind it.
Institutional Partners
Commission intelligence. Shape the conversation.
Uchumi360 works with development finance institutions, investment firms, sovereign bodies, and strategic organisations across the coverage region. Institutional partnership unlocks:
- Commissioned sector and country intelligence reports
- Branded research series under your institution's authority
- Exclusive data briefings for internal strategy teams
- Speaking and editorial presence at Uchumi360 events
- Co-published investment outlooks for your markets
Support Our Work
Independent analysis has a cost. Help us bear it.
Uchumi360 does not carry advertising. It does not take editorial direction from sponsors. Every article is produced without commercial compromise. Your contribution funds the reporting, research, and editorial infrastructure that keeps this analysis free from influence.
Secure checkout: One-time and monthly support are processed securely. Add payment credentials to enable checkout here.
Stay Connected
Keep up with every new insight.
Follow our latest analysis, policy coverage, and market intelligence as soon as it is published. If you need something specific, reach out directly and we will point you to the right research.
